
AAA term life insurance provides a straightforward financial safety net designed to support your beneficiaries during a specified period of your life. By securing a policy through the AAA network, members and eligible individuals can access death benefit protection that remains fixed for a set term—typically 10, 15, 20, or 30 years—ensuring that loved ones are shielded from financial instability should the unexpected occur during that window.
Defining Term Life Insurance within the AAA Framework
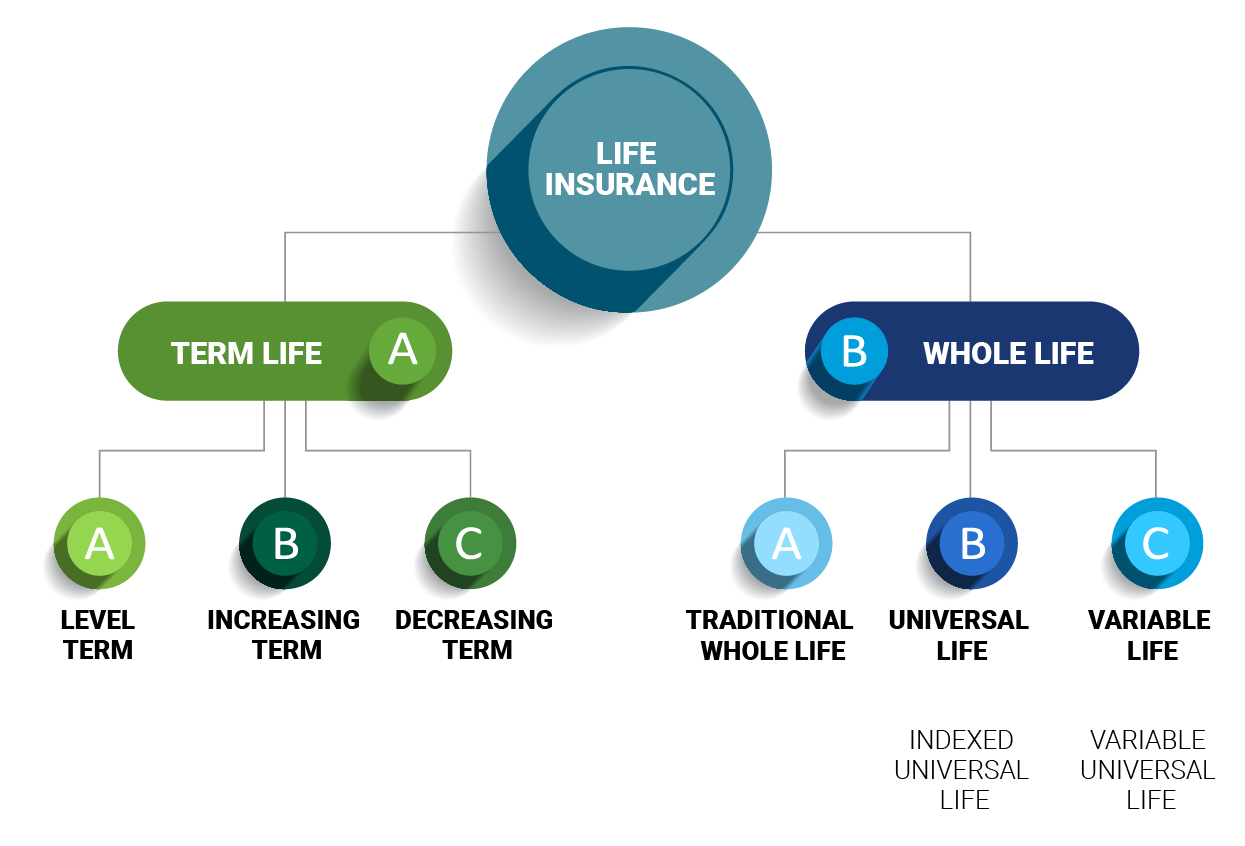
Term life insurance is the most fundamental form of life insurance. Unlike permanent or whole life policies, which incorporate an investment component or cash value accumulation, term life insurance focuses exclusively on the "death benefit." When you purchase a policy through AAA, you are essentially entering into a contractual agreement with an underwriting insurance carrier affiliated with the AAA brand.
The "term" refers to the specific duration the policy remains active. If the insured passes away during this period, the carrier pays the face amount of the policy to the designated beneficiaries. If the term expires and you are still living, the coverage ceases unless you have opted for a renewal or conversion provision. Because term life does not build cash value, it is generally the most cost-effective way to secure a high death benefit, making it a popular choice for families looking to cover specific "need periods," such as the years remaining on a mortgage or the time until children complete their education.
How AAA Insurance Distribution Operates
It is essential to clarify that "AAA" itself acts primarily as a federation of motor clubs. When you visit a website or office to inquire about "AAA term life insurance," you are engaging with an entity that distributes policies underwritten by specific insurance companies.
The underwriting insurance company is the entity legally responsible for paying claims and managing the financial risk of the policy. AAA clubs typically partner with highly rated national insurance carriers to offer these products to their members. This relationship means that while your initial application process might be handled through a AAA-affiliated portal or representative, your policy document—and the ultimate guarantee of the payout—sits with the underwriter. Understanding this distinction is vital for long-term policy management, as all billing, claims, and administrative inquiries regarding the coverage itself will eventually interface with the underwriting carrier.
Eligibility and Prerequisites for Coverage
To obtain term life insurance through the AAA network, you generally must meet specific criteria regarding membership, residency, and health status.
- Membership Status: While many AAA clubs offer insurance products exclusively to members, some programs allow non-members to apply, though membership often provides access to preferred pricing or streamlined processing. You should verify your local club’s specific policy regarding membership requirements.
- Age Restrictions: Most term life policies have entry age limits. For example, you may be able to secure a 30-year term policy if you are under 45, but as you approach the upper limits (often 65–75), you may be restricted to shorter terms (e.g., 10-year term) or forced to consider different life insurance products entirely.
- Medical Underwriting: Unless you are applying for a "guaranteed issue" policy—which is rare for standard term life—you will likely undergo medical underwriting. This involves a review of your health history, which may include:
- Completion of a medical questionnaire.
- Review of prescription drug databases.
- Potentially, a paramedical exam (blood pressure check, height/weight measurement, and blood/urine analysis).
- Residency: Insurance is heavily regulated at the state level. You must reside in a jurisdiction where the underwriting carrier is licensed to conduct business.
Navigating the Application Process
Applying for term life insurance through AAA-affiliated channels is designed to be a digital-first experience, though support is usually available via telephone or in-person at local club offices.
- Needs Assessment: Before applying, calculate your "coverage gap." Determine the total amount of debt (mortgage, loans), future obligations (college tuition), and income replacement your family would require if you were not present.
- The Quote Phase: Utilizing the online quote tool requires providing basic information: age, gender, tobacco use, and the desired coverage amount. This generates a preliminary premium estimate.
- Formal Application: Once you proceed, you will provide detailed personal information. Accuracy is paramount here. Inaccurate information on an application can lead to a denial of claims years down the line during the contestability period.
- The Underwriting Review: After submission, the insurance carrier reviews your data. This process can take anywhere from a few days to several weeks, depending on whether the carrier requires additional medical records from your primary care physician.
Table: Comparison of Common Term Life Concepts
| Feature | Term Life Insurance | Permanent (Whole) Life |
|---|---|---|
| Duration | Specific period (10–30 years) | Lifelong (as long as premiums are paid) |
| Cash Value | None | Yes, accumulates over time |
| Premium Costs | Generally lower | Generally higher |
| Primary Goal | Income replacement / Debt protection | Estate planning / Permanent legacy |
| Renewal | Usually ends at term expiry | Not applicable |
Cost Factors and Premium Structure
The premiums for your AAA term life policy are determined by a complex actuarial assessment. While you may see "starting at" prices, your actual cost will be dictated by the following variables:
- Age at Issue: The younger you are, the lower your mortality risk, and therefore the lower your monthly premium.
- Tobacco Usage: Non-smokers pay significantly less than smokers. If you use nicotine patches or vapes, carriers will often classify these as tobacco use, which increases premiums.
- Health Class: Carriers categorize applicants into risk classes (e.g., Preferred Plus, Standard, Substandard). A clean health history and stable vitals move you into "Preferred" tiers, which offer the lowest rates.
- Coverage Amount (Face Value): Higher death benefits require higher premiums. However, the cost per thousand dollars of coverage often decreases as you select higher face amounts.
Understanding Policy Provisions and Riders
When reviewing your policy offer, look closely at the "riders" or optional add-ons. Riders can customize your coverage but will increase your premium.
- Convertibility: This is a crucial provision. It allows you to convert your term policy into a permanent life insurance policy before the term expires, without having to undergo a new medical exam. This is a valuable hedge against future health declines.
- Waiver of Premium: This rider may allow your premiums to be waived if you become totally disabled and unable to work for a specific period.
- Accidental Death Benefit: This provides an additional payout if death occurs as a result of a qualifying accident, rather than illness or natural causes.
- Child Term Rider: This allows you to add a small amount of term coverage for your children to your own policy.
Important Considerations: The "Contestability Period"
When finalizing your policy, be aware of the "contestability period," which typically lasts for the first two years of the contract. During this window, the insurance company reserves the right to investigate the information provided on your original application. If they discover material misrepresentations—such as failing to disclose a high-risk medical condition or a history of drug use—they may have the legal right to void the policy or deny a death benefit claim. Always ensure your application is 100% accurate, even if you feel a health detail is minor.
Next Steps and Professional Advice
Selecting a life insurance policy is a significant financial commitment. If you are ready to explore your options through the AAA network, follow these recommended steps:
- Gather Financial Documentation: Have a clear picture of your total debt and income.
- Request a Quote: Use the official AAA website to pull a quote, but treat it as an estimate, not a final guarantee of cost.
- Review the Specimen Policy: Ask the representative to provide a "specimen policy" or "sample contract." Reading the fine print regarding exclusions and definitions is the best way to understand exactly what you are purchasing.
- Consult a Professional: If your financial situation is complex (e.g., you own a business, have significant estate tax concerns, or have complicated health needs), consult with an independent financial advisor or a licensed insurance broker. They can help you compare the AAA offering against other market options to ensure the coverage type is truly the best fit for your long-term goals.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
