Who Pays the Highest Auto Insurance Premiums in the US: A Comprehensive Analysis
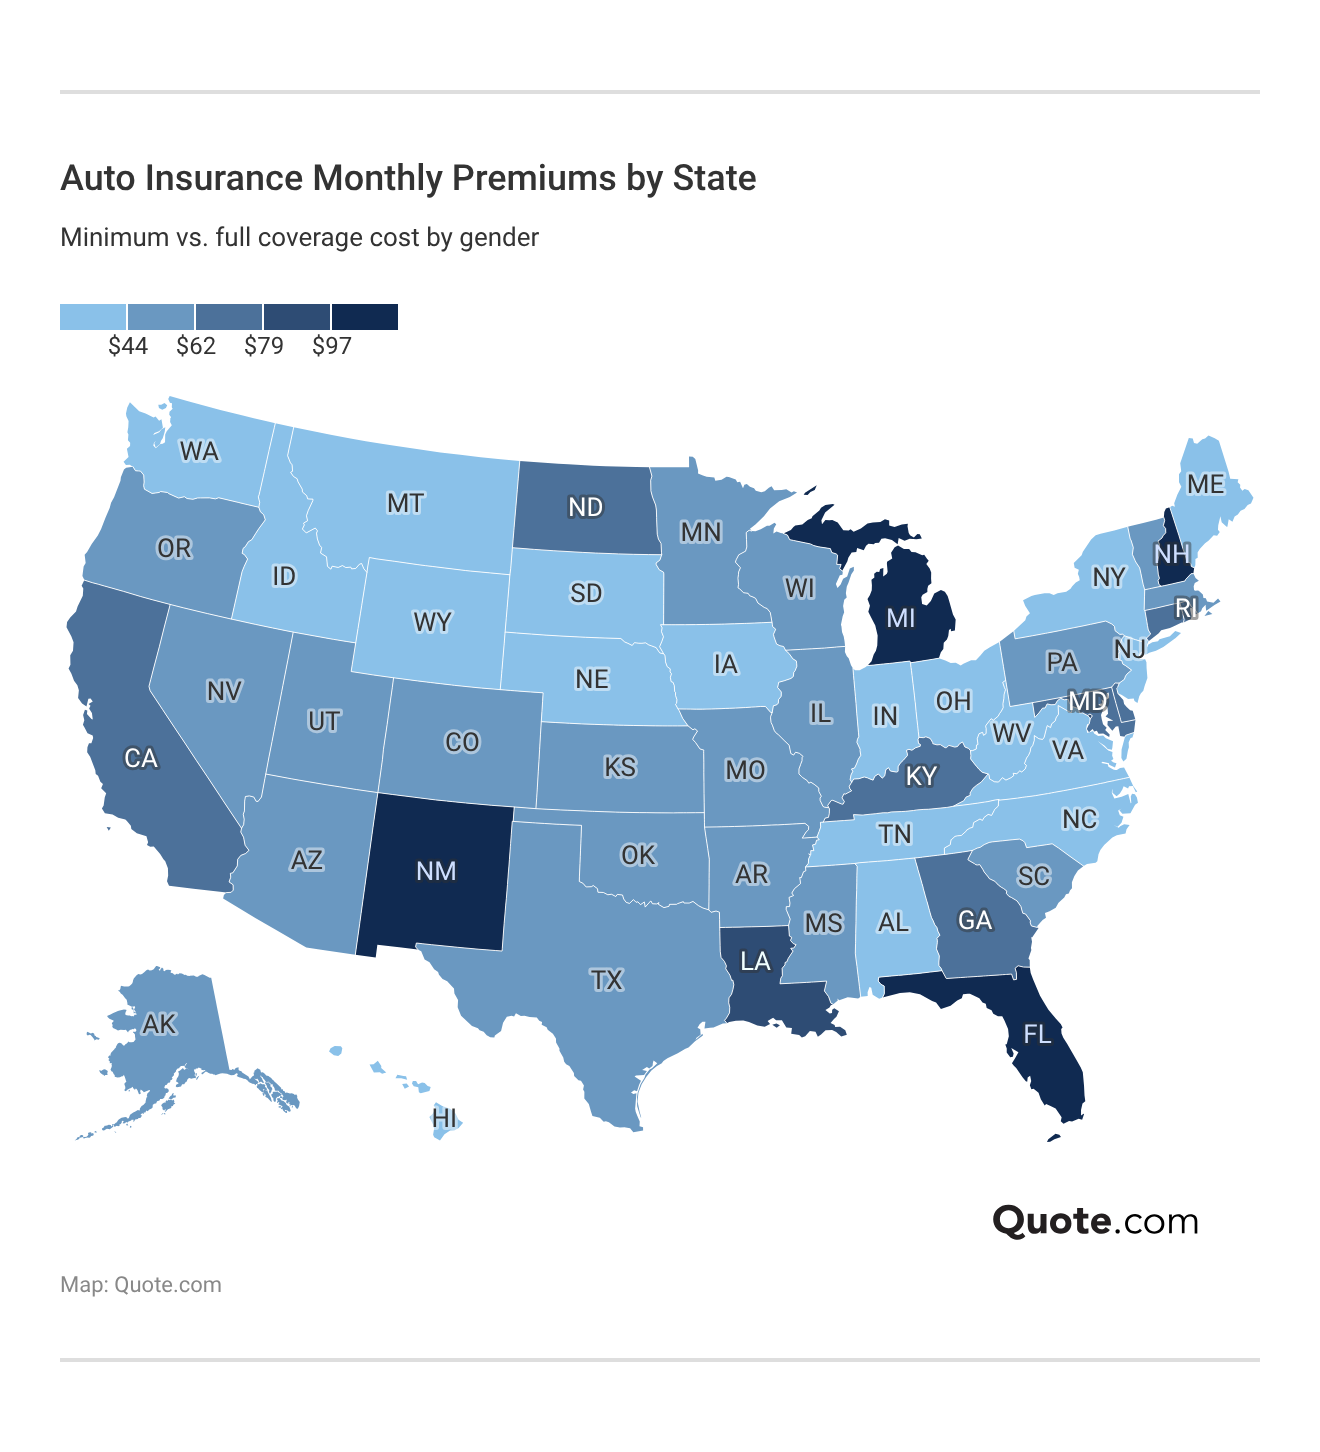
Drivers in the United States face varying insurance costs based on a complex interplay of risk factors, including driving history, location, age, and vehicle type. While there is no single "most expensive" demographic, data consistently identifies younger drivers, individuals with recent accident or violation records, and residents of high-risk urban environments as those paying the highest auto insurance premiums in 2026.
Understanding the Mechanics of Auto Insurance Pricing
Auto insurance premiums are fundamentally a reflection of statistical risk. Insurers calculate the likelihood that a specific policyholder will file a claim and the potential cost of that claim. When a driver falls into a category that data suggests is "high risk," insurers increase premiums to offset the statistical probability of a future payout.
In 2026, the primary factors influencing your premium remain largely consistent with historical underwriting standards, though the weight assigned to each can vary by state and individual insurance carrier. The pricing mechanism is designed to be actuarially sound, meaning it relies on large datasets to predict losses. Understanding these components is the first step in identifying why certain groups face higher financial burdens than others.
Demographic Drivers: Age and Experience
Age remains one of the most significant predictors of claim frequency. Statistically, drivers under the age of 25—and specifically teenagers—are involved in more accidents per mile driven than any other age group.
- Teenage Drivers: Insurance companies view inexperienced drivers as high-risk due to a lack of situational awareness and developmental factors that can lead to distracted or aggressive driving. Consequently, parents adding a teenager to their policy or young adults insuring their own vehicles often face the highest relative premiums.
- The Transition Period: Premiums typically begin to decrease significantly once a driver reaches age 25, provided they have maintained a clean driving record. However, this is not an overnight drop; it is a gradual reduction as the driver accumulates more years of incident-free experience.
The Impact of Driving History
While age is a demographic constant, driving history is a behavioral variable that carries immense weight. An individual's past performance is the strongest indicator of future behavior for insurance companies.
- At-Fault Accidents: A single at-fault accident can cause premiums to spike significantly for three to five years, depending on the state and company policy. Drivers who have multiple accidents on their record are often categorized into "non-standard" insurance markets, where they pay substantially higher rates than the average driver.
- Moving Violations: Speeding tickets, reckless driving citations, and failure to yield are all data points that signal increased risk. Serious infractions, such as Driving Under the Influence (DUI) or Driving While Intoxicated (DWI), are the most severe predictors. These violations do not just result in a rate increase; they can lead to the cancellation of a standard policy, forcing the driver to seek high-risk insurance, which is often drastically more expensive.
Geographic Disparity: Location-Based Premiums
Where you live is as important as how you drive. Insurers analyze the risk profile of specific ZIP codes, factoring in historical data regarding:
- Vehicle Theft Rates: Areas with high rates of car theft or break-ins inherently carry higher insurance costs because the risk of a comprehensive claim is elevated.
- Population Density: Densely populated urban centers often see higher premiums due to the increased frequency of minor traffic collisions and fender-benders compared to rural areas.
- Climate Risks: Regions prone to extreme weather—such as areas with high frequencies of hail, flooding, or hurricanes—will see higher comprehensive insurance costs, as these events lead to massive, localized insurance claims.
Vehicle Selection and Repair Costs
The vehicle itself contributes significantly to the premium. In 2026, the trend of vehicle technology—incorporating advanced sensors, cameras, and specialized alloy materials—has made repairs increasingly expensive.
- Repairability: Luxury vehicles or cars with specialized tech stacks require highly trained technicians and expensive parts. If a vehicle has a high "damage-to-cost" ratio, the collision portion of the insurance premium will be higher.
- Safety Ratings: Conversely, vehicles with excellent safety ratings and anti-theft features may qualify for discounts, though these are often offset by the vehicle's initial value and the cost of the advanced safety systems themselves if they require recalibration after an accident.
Comparative Cost Factors Table
| Factor Type | High-Risk Characteristic | Potential Impact on Premium |
|---|---|---|
| Demographic | Teenager / Young Adult (16–24) | Highest |
| History | Recent DUI or multiple at-fault accidents | Extremely High |
| Location | Densely populated urban area with high theft | Moderate to High |
| Vehicle | High-value, exotic, or specialized tech | High |
| Credit | Poor credit score (where allowed) | Moderate to High |
The Role of Credit Scores
In most states, insurance companies use "insurance-based credit scores" to help predict the likelihood of a future claim. Research has shown a correlation between lower credit scores and a higher frequency of claims. While some states have moved to restrict or ban the use of credit scores in underwriting, in many parts of the U.S., a poor credit score acts as a significant multiplier on auto insurance premiums.
Managing High Premiums: Next Steps
If you fall into one of the categories identified as paying the highest premiums, there are tangible steps to manage or reduce these costs:
- Review Deductibles: Choosing a higher deductible lowers the monthly premium, though it requires you to have more out-of-pocket cash available in the event of an accident.
- Bundle Policies: Many insurers provide significant discounts if you combine your auto insurance with homeowners or renters insurance.
- Telematics Programs: If you are a safe driver, participating in a usage-based insurance (UBI) program—where a device or app tracks your actual driving habits—can allow you to prove your safety and earn discounts, even if your demographic profile is otherwise considered high-risk.
- Shop Around Regularly: Because insurance companies weight risk factors differently, the "most expensive" company for one person may be the most competitive for another. Requesting quotes from multiple carriers every 12 to 24 months is a best practice.
Frequently Asked Questions
Does a DUI permanently increase my insurance premiums? No, it is not permanent. Most insurers look back three to five years for significant violations. While a DUI will lead to a substantial increase in premiums for several years, your rates will eventually trend downward if you maintain a clean record afterward.
Why do young drivers pay more even if they haven't had an accident? Insurance is based on actuarial data. Insurers do not look at just the individual, but the risk pool the individual belongs to. Statistics prove that the 16–24 age demographic as a whole has a much higher rate of claims, and pricing models adjust for that group risk accordingly.
Does my credit score really affect my car insurance? In many states, yes. Insurers use credit-based insurance scores to calculate risk. If you reside in a state where this practice is legal, improving your financial health can indirectly help lower your insurance premiums over time.
Can I get cheaper insurance if I drive an older car? Generally, yes. Older cars have a lower Actual Cash Value (ACV). Since comprehensive and collision insurance are designed to pay out based on the car's value, insuring a lower-value vehicle reduces the insurer's potential liability, often leading to lower premiums for those specific coverages.
Are there state-mandated caps on how much an insurer can charge? Insurance regulators in each state oversee rate filings. While there are no "caps" on the maximum amount a company can charge, all rate increases must be justified to the state's Department of Insurance to ensure they are not unfairly discriminatory or arbitrary.
Final Recommendation
The "highest" insurance premiums are rarely the result of a single factor, but rather the compounding effect of multiple high-risk indicators. To address your specific premium, verify your current driving record and credit profile for errors, and consult with an independent insurance broker who can compare rates across multiple carriers. Focus on long-term habits, such as maintaining a clean driving record and improving your credit score, as these are the most effective levers for reducing costs over time.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
