
Solvent net worth refers to a state of financial health where an individual or entity’s total assets exceed their total liabilities, signifying the ability to meet all long-term financial obligations. Unlike simple liquidity, which measures the availability of cash for immediate needs, being solvent indicates a sustainable balance sheet where the cumulative value of holdings provides enough coverage to settle all debts in full.
Defining Solvency vs. Liquidity
To understand net worth in the context of solvency, one must distinguish between two fundamental financial concepts: solvency and liquidity. While the terms are often used interchangeably in casual conversation, they represent distinct aspects of fiscal stability.
Liquidity is a measure of an individual’s or company’s ability to pay off current liabilities using only current assets—specifically cash or assets that can be converted to cash rapidly. A person might have a high net worth but still struggle with liquidity if their wealth is tied up in illiquid assets, such as real estate or private business equity.
Solvency, by contrast, is a long-term metric. A solvent entity has a positive net worth. If you were to liquidate all your assets—selling your home, investments, vehicles, and personal property—and use that capital to pay off your mortgage, student loans, credit card balances, and other debts, you would still have a positive balance remaining. If your liabilities exceed your assets, you are considered insolvent, even if you currently have enough cash on hand to pay this month’s bills.
The Mathematics of Net Worth Calculation
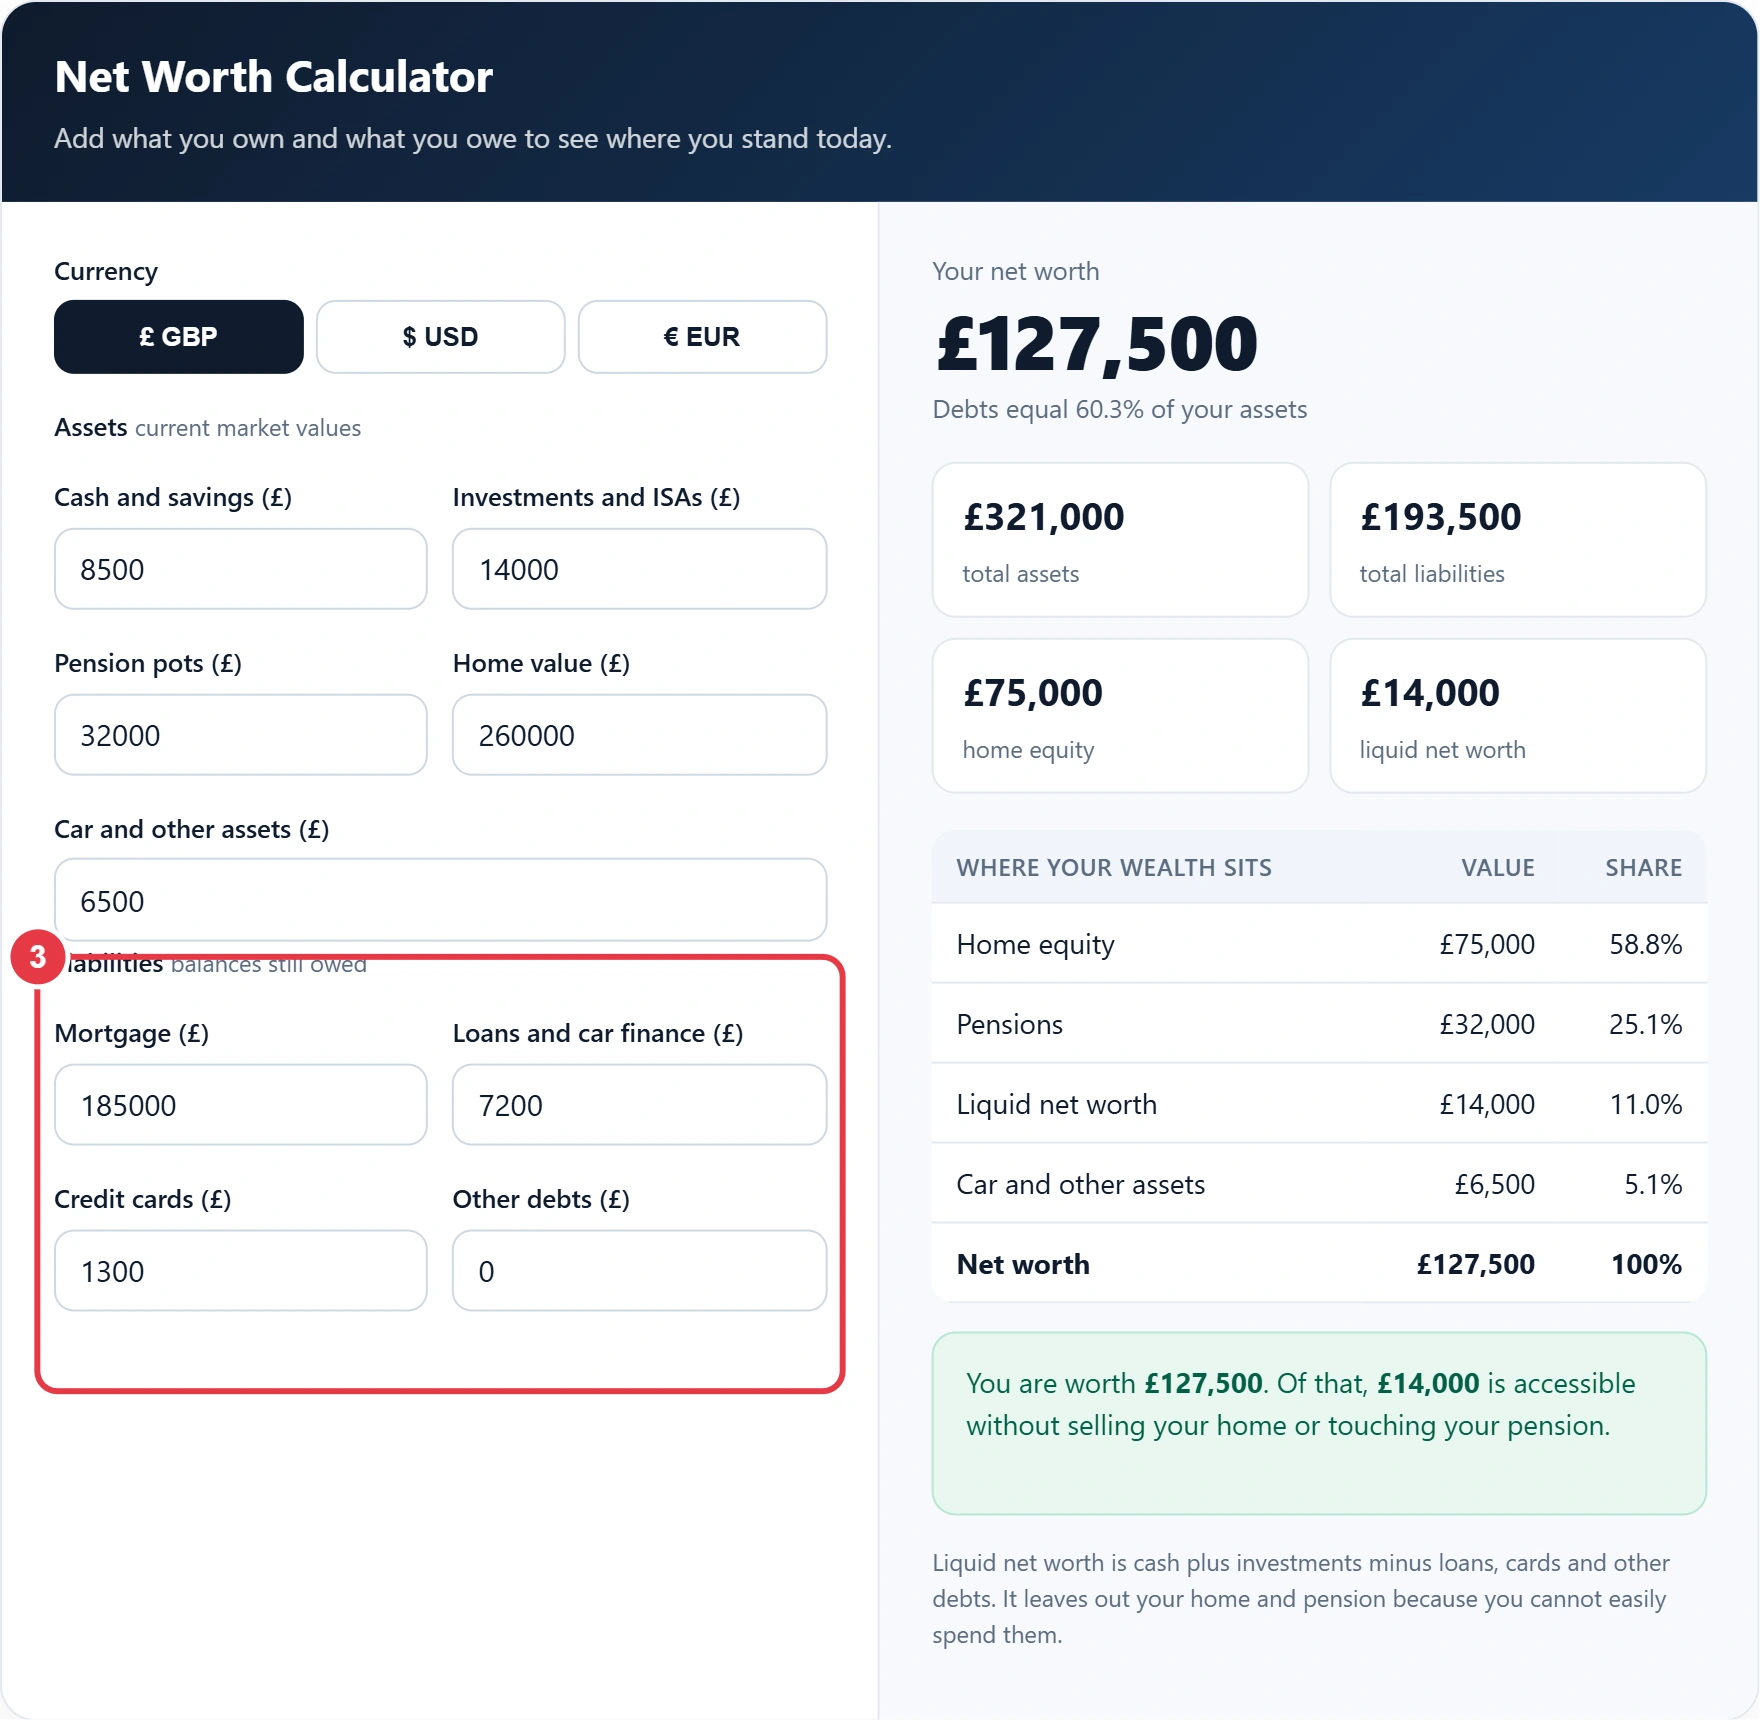
The calculation of net worth is a straightforward arithmetic exercise, though the accuracy of the result depends heavily on the precision of your asset valuations. To determine if you are solvent, you must perform a comprehensive audit of your financial position.
The formula is expressed as: Total Assets – Total Liabilities = Net Worth
1. Enumerating Assets
Assets are anything of value that you own. To gain a true picture of your solvency, these must be categorized by their nature:
- Liquid Assets: Cash, savings accounts, money market funds, and certificates of deposit (CDs).
- Investments: Retirement accounts (401(k), IRA), brokerage accounts, stocks, bonds, and mutual funds.
- Real Assets: Your primary residence, rental properties, land, or business holdings.
- Personal Property: Vehicles, jewelry, collectibles, and high-value household items.
2. Enumerating Liabilities
Liabilities represent your financial obligations to external parties. These must include both short-term and long-term commitments:
- Secured Debt: Mortgages, home equity lines of credit (HELOC), and auto loans.
- Unsecured Debt: Credit card balances, personal loans, and student loans.
- Deferred Obligations: Tax liabilities, unpaid professional fees, or pending legal judgments.
Interpreting Financial Standing
Once you have calculated your net worth, the figure provides a snapshot of your financial position relative to your debt. A positive net worth is the primary indicator of solvency. However, the degree of solvency is equally important for long-term planning.
| Net Worth Status | Financial Implication | Recommended Action |
|---|---|---|
| High Positive | Strong solvency; high financial flexibility. | Focus on tax-efficient growth and estate planning. |
| Low Positive | Technically solvent, but vulnerable to shocks. | Prioritize emergency fund growth and debt reduction. |
| Zero | Break-even status; no margin for error. | Evaluate spending habits and increase income streams. |
| Negative | Insolvent; liabilities exceed assets. | Seek professional debt restructuring or credit counseling. |
The Role of Asset Valuation in Solvency
One of the most common pitfalls when calculating net worth is the overvaluation of assets. It is vital to use market value rather than original purchase price or personal sentiment.
For example, if you purchased a car five years ago for $30,000, its value today is not $30,000; it is the current market value (resale value). Similarly, when assessing the value of a home for solvency purposes, use conservative estimates based on recent comparable sales in your area rather than optimistic market assessments. Overestimating asset values can create a false sense of security, masking an underlying state of insolvency.
Debt-to-Asset Ratios and Long-term Sustainability
While net worth provides the "what," the debt-to-asset ratio provides the "how well." An individual may have a positive net worth but carry a debt load that consumes an unsustainable portion of their monthly cash flow.
A healthy financial profile involves monitoring both your net worth and your debt-to-income ratio. If your liabilities are concentrated in high-interest debt, such as credit cards, your solvency is at risk even if your net worth is positive. Interest payments on high-cost debt can erode your assets over time, turning a solvent position into an insolvent one. True solvency requires that your assets grow at a rate that consistently outpaces the growth of your liabilities.
Common Risks to Solvency
Financial solvency is not a static state; it is subject to change based on market conditions, personal circumstances, and unexpected events. Several factors frequently threaten personal solvency:
- Concentration Risk: Having a high net worth tied entirely to a single asset class, such as a single stock or one real estate property, makes your solvency vulnerable to sector-specific downturns.
- Inflation: If your assets are held in cash or low-yield savings accounts, inflation can reduce their real value over time, while your debt obligations (which are fixed) remain the same.
- Life Transitions: Events such as divorce, medical emergencies, or job loss can drastically reduce asset values or increase debt loads, potentially pushing a previously solvent individual into insolvency.
- Interest Rate Volatility: For those with variable-rate debt, rising interest rates can significantly increase the cost of maintaining current debt, reducing net worth and cash flow simultaneously.
Professional Guidance and Legal Implications
In extreme cases where liabilities consistently exceed assets, individuals may reach a state of technical insolvency that requires legal intervention, such as bankruptcy. Before reaching this point, consulting with a Certified Financial Planner (CFP) or a tax professional can provide a clearer perspective on your options for debt restructuring and asset optimization.
It is important to note that financial advice should be tailored to your specific jurisdictional laws, as regulations regarding bankruptcy, debt collection, and asset protection vary significantly. This article is for informational purposes and does not constitute formal legal or financial advice.
Frequently Asked Questions
Does a high income mean I am solvent? Not necessarily. Income refers to the money coming in, while solvency is based on the balance between what you own and what you owe. You could earn a very high salary but spend it all on debt service and lifestyle costs, resulting in a low or negative net worth.
Should I include my future pension in my net worth? Generally, no. For the purpose of determining current solvency, only assets you currently control and could convert to value should be counted. Future income, such as Social Security or pension payments, is usually excluded from net worth calculations because it is contingent and not a liquid asset.
How often should I calculate my net worth? For most individuals, calculating net worth on an annual basis is sufficient. However, if you are actively managing a debt repayment plan or undergoing significant life changes, quarterly assessments can help you track your progress toward improved solvency.
Does a mortgage affect my net worth? Yes. A mortgage is a liability. However, it is matched by an asset—the home itself. Your net worth is increased only by the "equity" you have in the home, which is the current market value of the property minus the remaining mortgage balance.
What is the difference between personal and business solvency? Personal solvency focuses on individual assets and liabilities. Business solvency assesses the ability of a company to meet its long-term debts. While they are distinct, they often overlap for sole proprietors or business owners who have personally guaranteed company debt.
Next Actions for Financial Health
To move toward a more solvent financial future, start by creating a comprehensive net worth statement. List every asset you own with its current fair market value, and list every debt you owe, including the current payoff balance for each.
Once your statement is complete, compare your total assets to your total liabilities. If your ratio is lower than you would like, develop a strategy to increase your assets through saving and prudent investing, while simultaneously creating a plan to accelerate the payment of high-interest liabilities. Consistent monitoring and disciplined adjustment of this balance sheet will serve as the foundation of your long-term financial security.

Image Gallery
Select an image to open it in a new tab.




Declan O'Connor
Higher Education and Campus Culture Reporter
