Understanding the Life Insurance Policy Landscape in Greenacres: A Comprehensive 2026 Guide

Understanding the life insurance policy landscape in Greenacres, Florida, requires a grasp of state-specific regulations, local economic factors, and the diverse range of products available in 2026. Residents must navigate Florida’s robust consumer protection laws, including the 21-day "free look" period, while selecting coverage that addresses Palm Beach County’s unique cost-of-living requirements and estate planning needs.
The decision to secure life insurance is one of the most significant financial steps a resident of Greenacres can take. Whether you are a young professional moving into a new development near Lake Worth Road or a retiree enjoying the quiet neighborhoods near Okeeheelee Park, your insurance needs are dictated by your specific stage of life and long-term financial goals. As of 2026, the Florida insurance market remains one of the most active in the United States, offering a blend of traditional protection and modern, technology-driven underwriting processes that make obtaining coverage more accessible than ever.
The Regulatory Framework in Greenacres and Florida
While insurance is often discussed in national terms, it is strictly regulated at the state level. In Greenacres, all life insurance activities are governed by the Florida Department of Financial Services (DFS) and the Office of Insurance Regulation (OIR). These bodies ensure that insurance companies operating within the state remain solvent and treat policyholders fairly.
One of the most critical protections for Greenacres residents in 2026 is the Florida Life & Health Insurance Guaranty Association. This entity provides a safety net for policyholders if an insurance company becomes insolvent. While there are limits to the coverage (typically up to $300,000 in death benefits), it offers essential peace of mind in an era of global financial shifts.
Furthermore, Florida law provides a mandatory 21-day "free look" period for life insurance and annuity contracts. This allows a Greenacres resident to receive their policy, review the terms in detail, and return it for a full refund of any premiums paid if they decide the coverage is not right for them. This transparency is a cornerstone of the Florida insurance landscape, protecting consumers from high-pressure sales tactics.
Primary Types of Life Insurance Policies in 2026
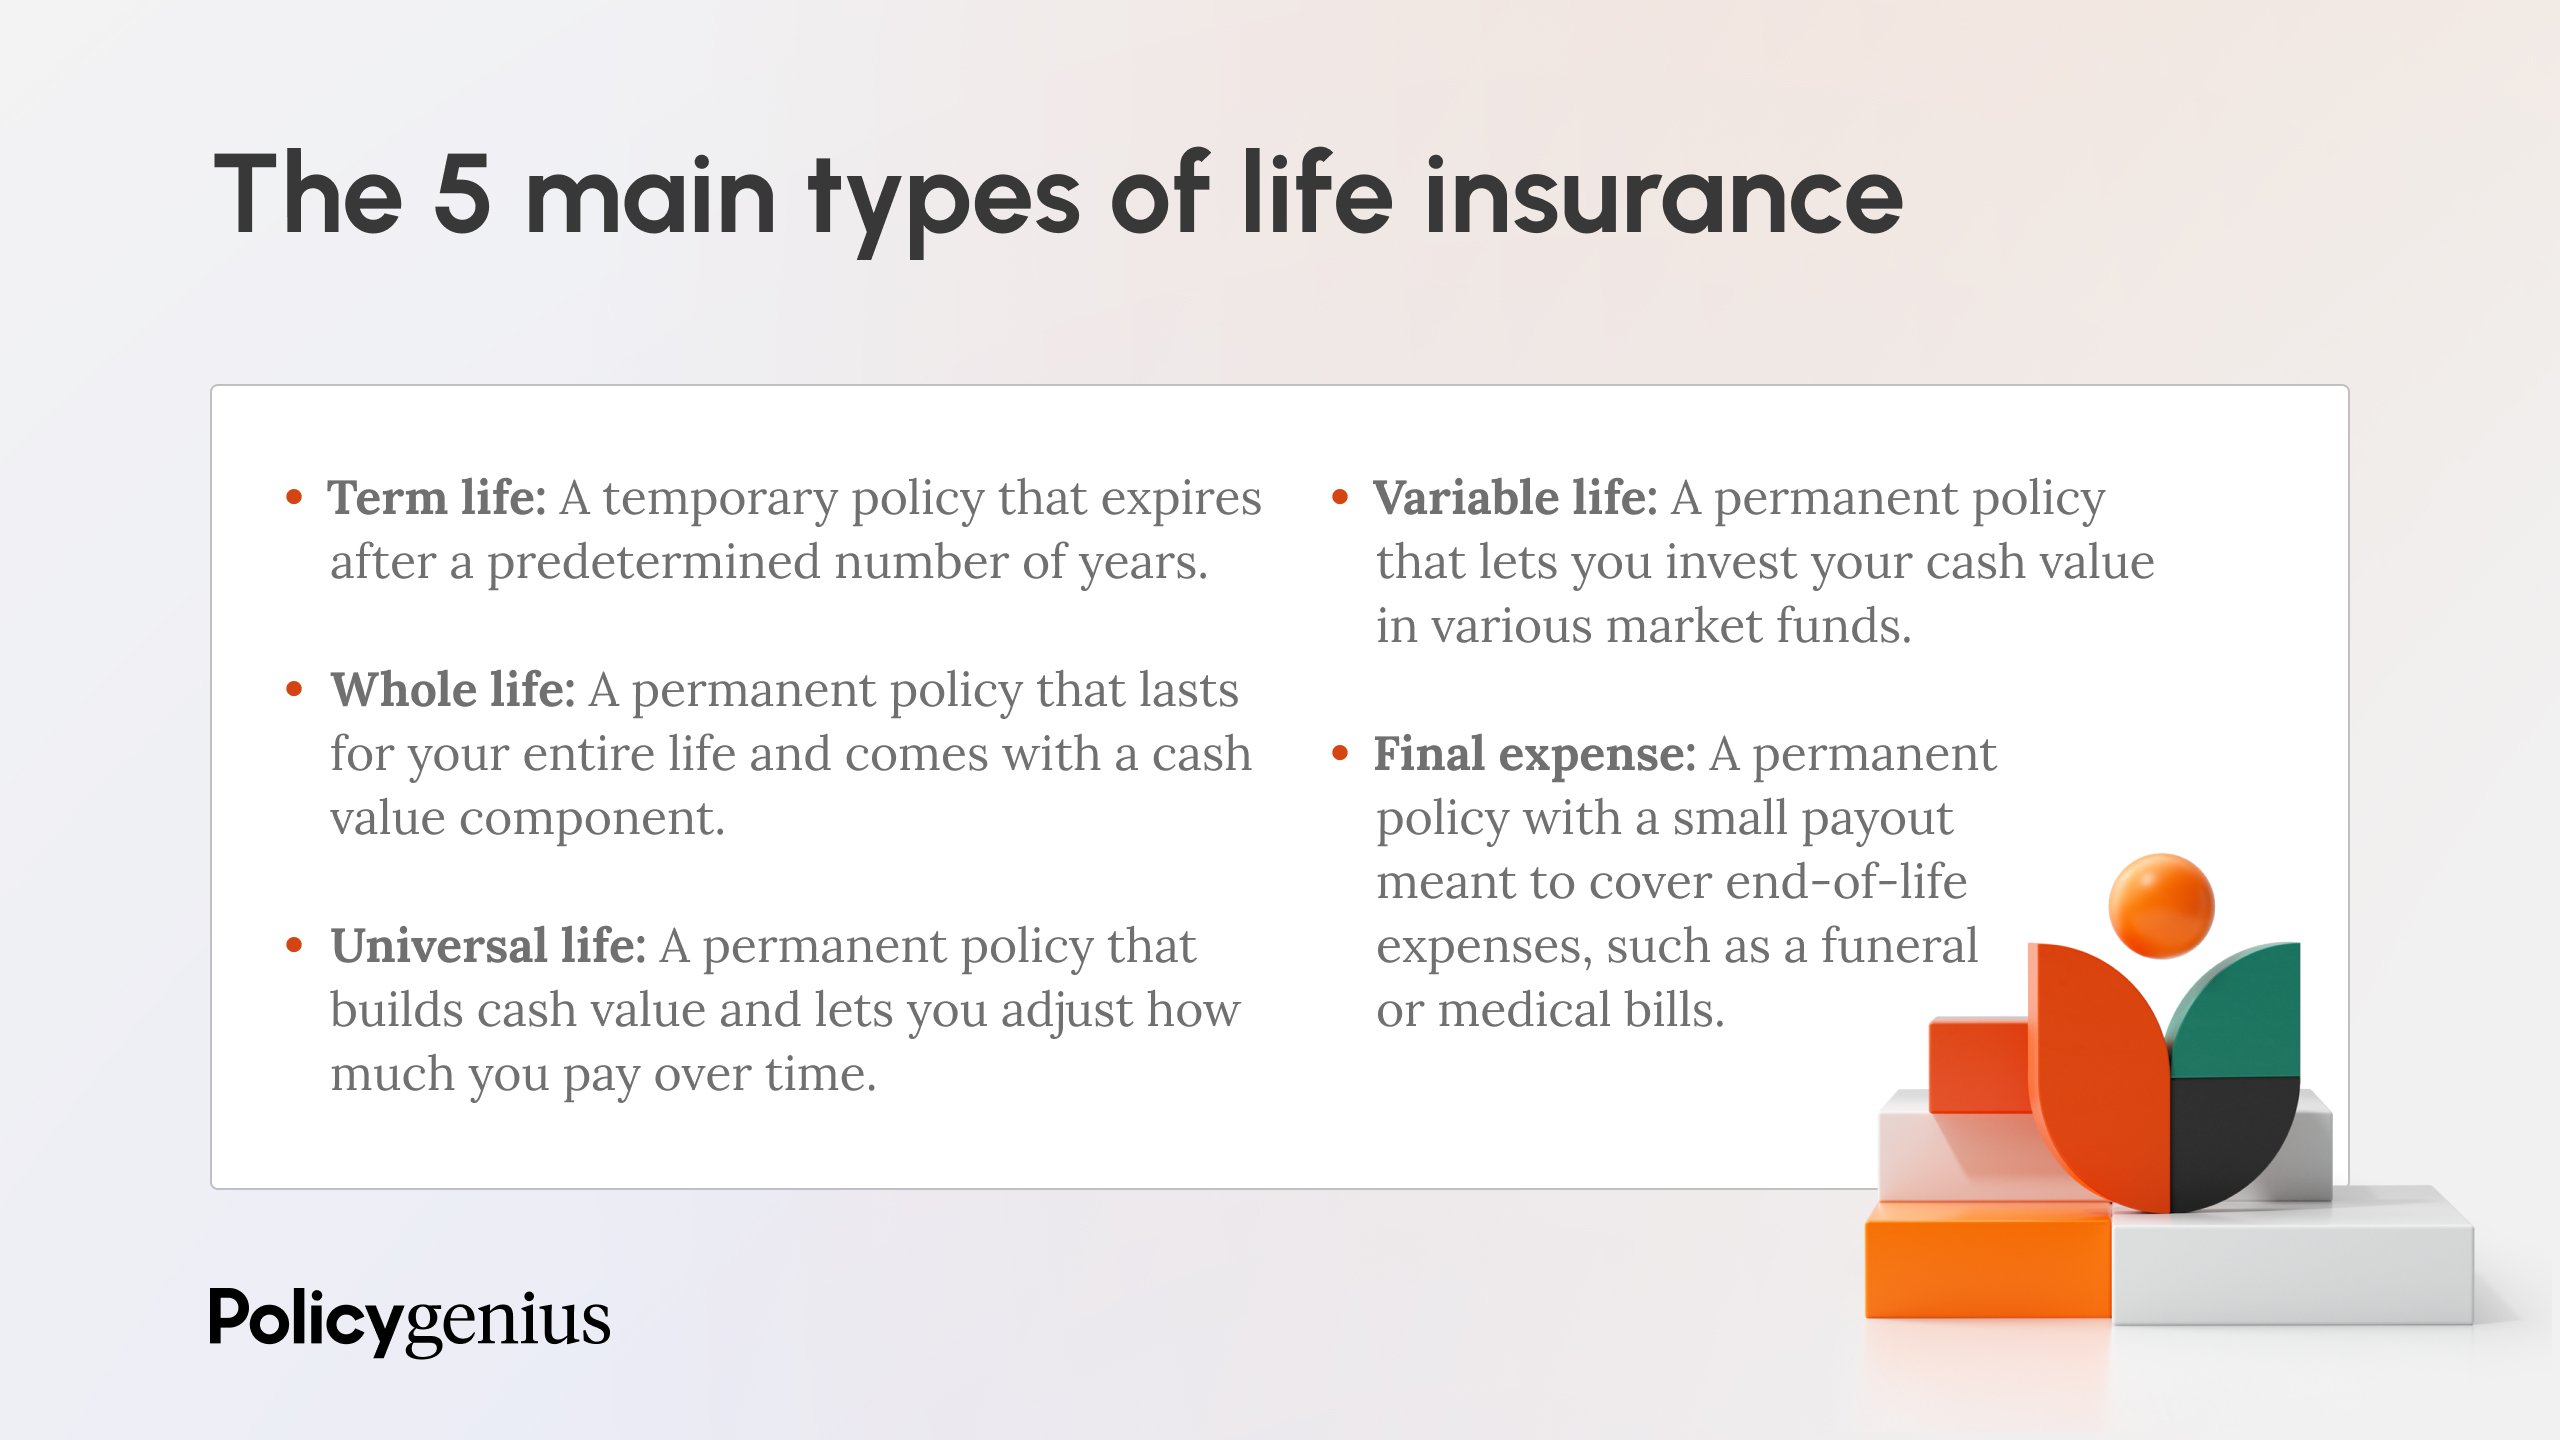
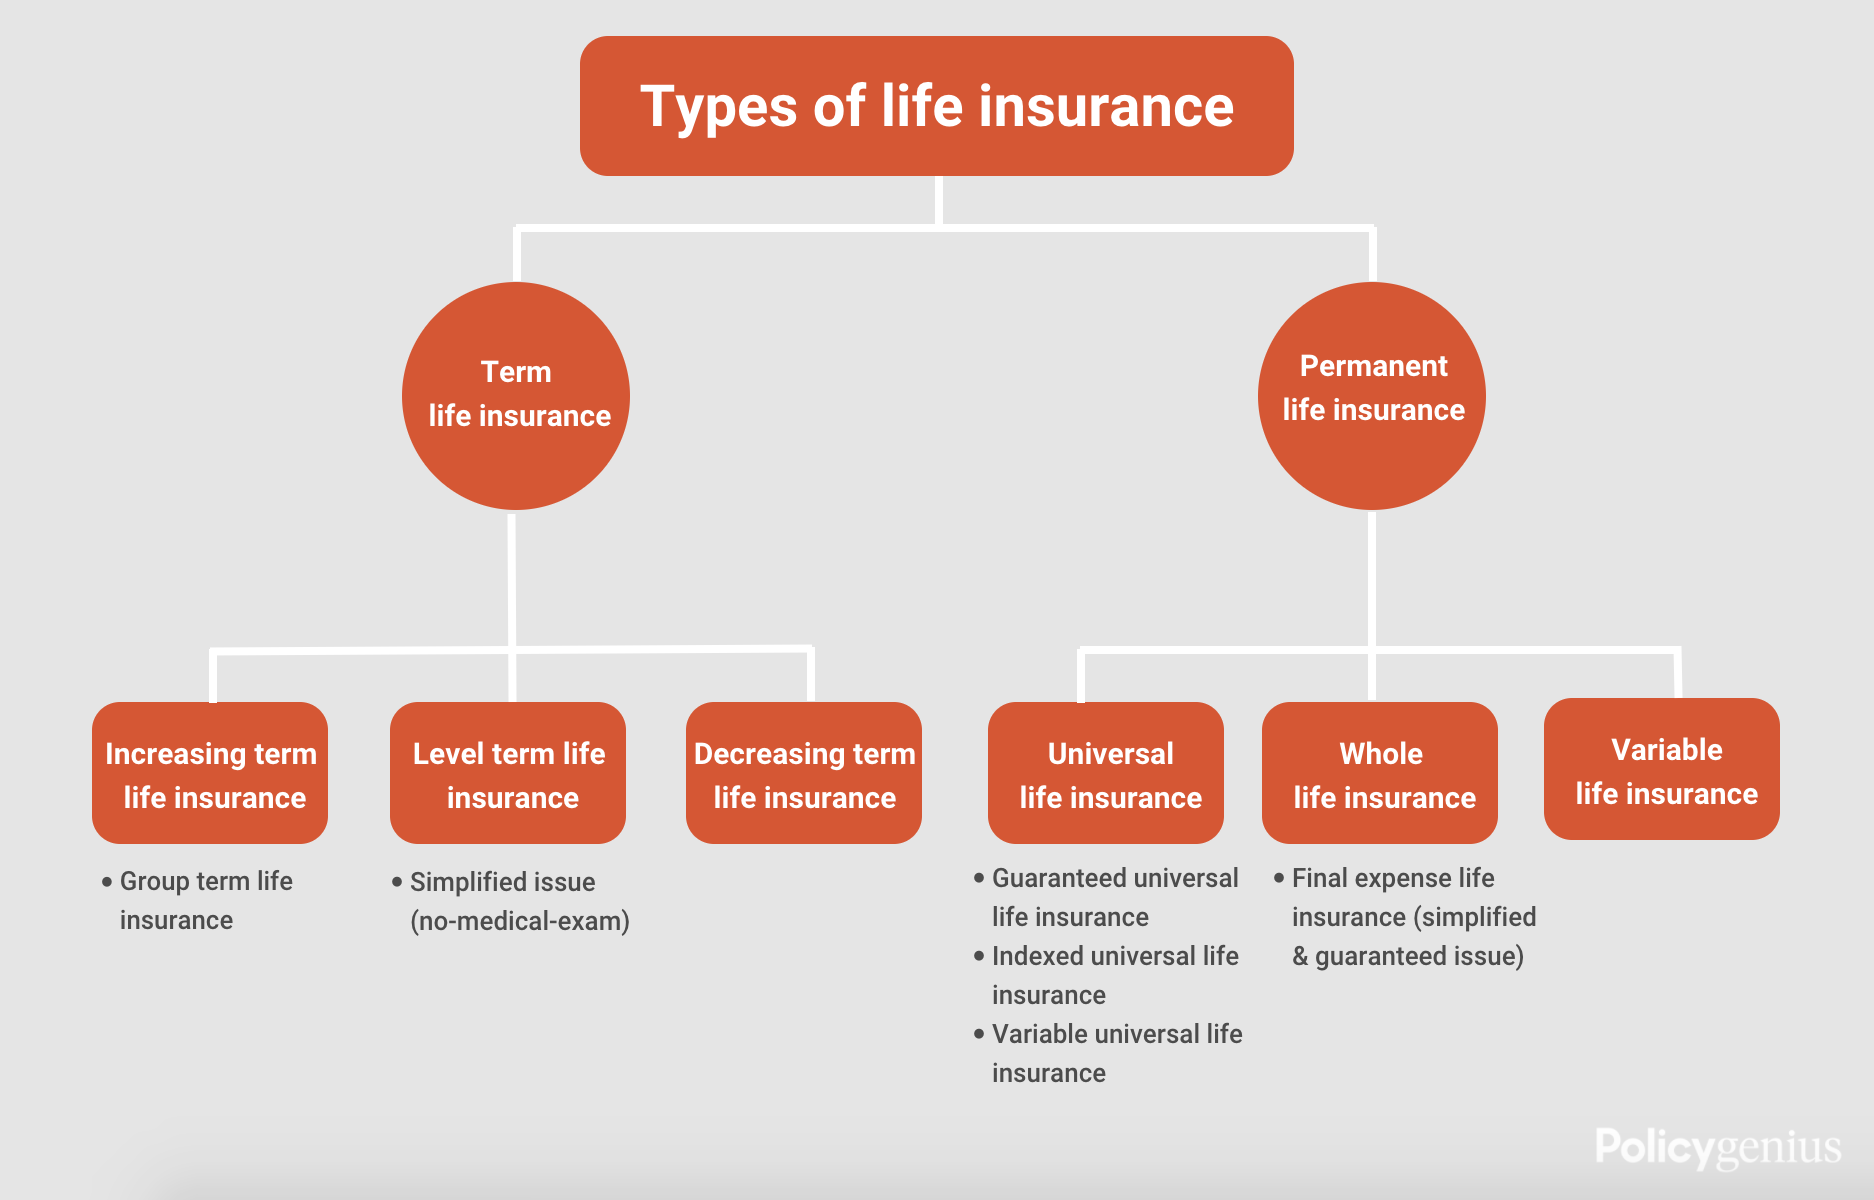
The landscape in Greenacres is populated by several distinct types of life insurance, each serving a different purpose. Choosing the right one depends on whether you need temporary protection or a lifelong financial tool.
Term Life Insurance: The Foundation of Protection
Term life insurance remains the most popular choice for families in Greenacres due to its simplicity and affordability. It provides a death benefit for a specific period—typically 10, 20, or 30 years. In 2026, many Greenacres residents use term insurance to cover the duration of a mortgage or to ensure that children have college tuition covered if a parent passes away prematurely.
The primary advantage of term insurance is that it offers the highest death benefit for the lowest premium. However, it does not build cash value, and once the term expires, the coverage ends unless the policy includes a "conversion rider." This rider, common in modern Florida policies, allows the holder to convert the term policy into a permanent one without undergoing a new medical exam.
Whole Life Insurance: Permanent Security
Whole life insurance is a type of permanent coverage that remains in force for the insured’s entire life, provided premiums are paid. In the Greenacres market, whole life is often utilized as an estate planning tool. It features a guaranteed death benefit and a cash value component that grows at a fixed rate set by the insurer.
For residents looking for "forced savings" or a way to leave a tax-free legacy, whole life is a stalwart option. In 2026, many policies also offer "living benefits," which allow the policyholder to access a portion of the death benefit if they are diagnosed with a chronic or terminal illness—a feature particularly relevant to the senior population in Palm Beach County.
Universal Life Insurance: Flexibility and Growth
Universal Life (UL) insurance offers more flexibility than whole life. It allows Greenacres policyholders to adjust their premiums and death benefits as their financial situation changes. This is particularly useful for business owners in the area whose income may fluctuate annually.
Within the UL category, Indexed Universal Life (IUL) has gained significant traction in 2026. These policies tie the growth of the cash value to a market index, such as the S&P 500, while providing a floor to protect against market losses. This offers a middle ground between the safety of whole life and the growth potential of the stock market.
Local Factors Influencing Life Insurance in Greenacres
The cost and necessity of life insurance are heavily influenced by the local environment. Greenacres, situated in the heart of Palm Beach County, has specific economic markers that residents must consider.
Mortgage Protection and Real Estate
As property values in Greenacres have continued their steady trajectory through 2026, the average mortgage balance for local homeowners is significant. Life insurance acts as a critical hedge against foreclosure. A well-structured term policy can ensure that if a primary breadwinner passes away, the remaining family members can pay off the mortgage and stay in their home.
Cost of Living and Inflation Adjustments
Palm Beach County generally experiences a cost of living slightly higher than the national average. When calculating coverage needs, Greenacres residents must account for the rising costs of healthcare, utilities, and daily essentials. In 2026, it is recommended that residents review their policies every three to five years to ensure the death benefit still provides the same purchasing power it did when the policy was first issued.
The Role of Probate in Florida
Florida’s probate process can be lengthy and expensive. One of the primary benefits of life insurance for Greenacres residents is that the death benefit generally bypasses probate. This means the funds are paid directly to the beneficiaries, often within weeks, providing immediate liquidity to cover funeral expenses and immediate bills while the rest of the estate is settled.
The Application and Underwriting Process in 2026
The way life insurance is purchased in Greenacres has evolved significantly. In 2026, "Accelerated Underwriting" has become the standard for most healthy applicants under age 60.
Digital Underwriting and Biometrics
Gone are the days when every policy required a "paramedical" exam involving blood draws and physical check-ups. Many insurers now use sophisticated algorithms that analyze prescription history, motor vehicle records, and even credit-based insurance scores to approve policies in real-time. For a resident in Greenacres, this means a policy that once took six weeks to issue can now be active in six minutes.
Traditional Medical Exams
For those seeking high-value policies (typically over $2 million) or those with complex health histories, a traditional medical exam may still be required. There are several mobile examiners serving the Greenacres and West Palm Beach area who can conduct these exams at the applicant’s home or office, ensuring the process remains convenient despite the increased scrutiny.
Comparison of Common Life Insurance Options
| Feature | Term Life | Whole Life | Universal Life (IUL) |
|---|---|---|---|
| Duration | Fixed Period (10–30 years) | Lifelong | Lifelong |
| Premiums | Generally Fixed/Low | Fixed/High | Flexible |
| Cash Value | No | Yes (Guaranteed) | Yes (Market-linked) |
| Complexity | Low | Medium | High |
| Best For | Mortgage/Income Protection | Estate Planning/Legacy | Wealth Accumulation/Flexibility |
| 2026 Popularity | High (Families) | Moderate (Seniors) | Rising (High-Net-Worth) |
Enhancing Coverage with Policy Riders
Riders are optional add-ons that customize a life insurance policy to meet specific needs. In the Greenacres landscape, certain riders are particularly valuable:
- Waiver of Premium: If the policyholder becomes totally disabled and cannot work, the insurance company waives the premium payments while keeping the policy in force.
- Accidental Death Benefit: This pays an additional sum if the death is the result of an accident. Given the high traffic volume in the South Florida area, this is a frequent consideration for local commuters.
- Child Term Rider: Provides a small amount of coverage for children, which can later be converted into a permanent policy regardless of their future health status.
- Long-Term Care (LTC) Rider: In 2026, the cost of long-term care in Florida is a major concern. This rider allows the policyholder to use a portion of the death benefit to pay for home health care or facility care if they can no longer perform daily living activities.
Common Mistakes to Avoid for Greenacres Residents
Navigating the insurance landscape can be treacherous without the right information. Residents should be wary of several common pitfalls:
- Relying Solely on Employer-Provided Coverage: Many professionals in Greenacres have life insurance through their jobs. However, this coverage is usually only 1-2 times their salary and is rarely portable. If you lose your job or change careers, you lose your protection.
- Underestimating the "Stay-at-Home" Parent’s Value: The services provided by a non-working parent (childcare, transportation, household management) are expensive to replace. Life insurance should cover both parents, regardless of who brings home a paycheck.
- Waiting Too Long to Buy: Age and health are the primary drivers of insurance costs. In 2026, the price difference between a policy purchased at age 30 versus age 40 can be substantial. Locking in rates early is the most effective way to save money over the life of the policy.
- Naming Minor Children as Beneficiaries: In Florida, insurance companies cannot pay death benefits directly to minors. This often leads to court intervention and the appointment of a guardian, which consumes time and money. It is usually better to name a trust or a legal adult guardian as the beneficiary.
Frequently Asked Questions
Does Greenacres have specific local taxes on life insurance premiums?
No, insurance premium taxes are handled at the state level in Florida. While there are taxes applied to the premiums paid, these are usually baked into the quote provided by the insurance company. There are no additional "city-level" taxes specific to Greenacres for life insurance products.
Can I get life insurance if I am not a U.S. citizen but live in Greenacres?
Yes. Florida is home to many international residents. In 2026, many insurers offer coverage to foreign nationals or those with permanent residency (Green Cards) and even certain visa types (like H-1B or L-1). The requirements typically involve proving a "financial interest" in the U.S., such as owning a home in Greenacres or working for a local company.
What happens if I move away from Greenacres after buying a policy?
Life insurance policies purchased in Florida are generally portable. If you move to another state or even another country, your coverage remains in effect as long as you continue to pay the premiums. However, it is essential to update your address with the insurance carrier to ensure you receive important notices and annual statements.
Is the 21-day "free look" period unique to Florida?
While many states have a 10-day or 15-day free look period, Florida’s 21-day requirement is one of the more consumer-friendly mandates in the country. This specifically applies to life insurance and annuity contracts issued within the state to provide residents with ample time to consult with financial advisors or legal counsel.
Are life insurance proceeds taxable in Florida?
Generally, the death benefit from a life insurance policy is received by the beneficiaries free of federal and state income tax. However, if the death benefit is paid into an estate that exceeds the federal estate tax exemption limits, there may be estate tax implications. As of 2026, most Greenacres residents will find their life insurance proceeds are entirely tax-free.
Final Recommendations for Residents
When approaching the life insurance landscape in Greenacres, the first step is a clear-eyed assessment of your financial liabilities. Calculate your total debt, including mortgages and car loans, and add the projected future costs of your children’s education and your family's daily living expenses.
Next, consult with an independent insurance agent who has access to multiple carriers. Because different companies have different appetites for risk—some might be more lenient with a history of high blood pressure, while others offer better rates for avid runners—shopping around is essential. Ensure any professional you work with is licensed by the Florida Department of Financial Services. Finally, take advantage of the digital tools available in 2026 to compare quotes, but always read the fine print of the policy document during your 21-day free look period to ensure the coverage matches your expectations.
Image Gallery
Select an image to open it in a new tab.





Mateo Castillo
Decentralized Finance and E-Payments Strategist
