Growth mutual funds are essential for investors seeking long-term capital appreciation because they focus on companies demonstrating above-average earnings or revenue growth. In 2026, these funds serve as a primary engine for wealth accumulation, allowing individuals to outsource the complex task of identifying high-velocity businesses to professional managers while maintaining a diversified portfolio.
Understanding the Fundamentals of Growth Investing
To appreciate why top growth mutual funds matter, one must first understand the underlying philosophy of growth investing. Unlike value investing, which seeks "bargains" or undervalued companies, growth investing prioritizes future potential. Managers of these funds look for companies that are expected to grow at a rate significantly faster than the rest of the market or their specific industry peers.
In 2026, the landscape of growth investing has evolved. We are no longer looking just at traditional tech firms, but at a cross-sector integration of high-efficiency business models. A "growth" company typically reinvests its earnings into research and development, acquisitions, or capital expansion rather than paying out dividends. For the investor, this means the primary source of return is the increase in the share price (capital gains) rather than regular income.
Growth mutual funds aggregate capital from thousands of investors to buy shares in these high-performing entities. This structure is particularly important because individual growth stocks can be prohibitively expensive or carry significant idiosyncratic risk. By holding a basket of 50 to 150 different growth companies, a mutual fund mitigates the impact of a single company's failure while capturing the upward trajectory of the winners.
Why Top-Tier Growth Funds Are Crucial in 2026
As we navigate the economic environment of 2026, the gap between "average" and "top-tier" funds has widened. The importance of selecting top-performing growth funds lies in their ability to navigate volatility while capturing the benefits of secular shifts in the global economy.
1. Access to High-Velocity Sectors
Top growth funds often have early and deep access to sectors that are currently driving the global economy. This includes advanced artificial intelligence integration, renewable energy infrastructure, and personalized biotechnology. For an individual investor, identifying which firm will lead in "Edge Computing" or "CRISPR-based therapies" is a full-time job. Growth mutual funds employ teams of analysts who conduct "boots-on-the-ground" research, visiting companies and analyzing supply chains to ensure they are betting on the right horses.
2. The Power of Professional Management
In a market where valuations can fluctuate based on interest rate shifts and geopolitical stability, professional management is a significant advantage. Top fund managers utilize sophisticated risk-management tools to hedge against downsides. They practice "active management," meaning they can pivot the fund’s holdings when a company’s growth narrative changes. This is a stark contrast to passive index funds, which must hold a stock as long as it remains in the index, regardless of its deteriorating fundamentals.
3. Capital Appreciation vs. Inflation
With the ongoing adjustments in global monetary policy, growth mutual funds remain one of the most effective hedges against inflation. Because growth companies possess "pricing power"—the ability to raise prices without losing customers—their earnings often outpace inflationary pressures. For investors in 2026, maintaining the purchasing power of their savings is a top priority, and growth funds provide the necessary "alpha" (excess return) to stay ahead of rising costs.
Analyzing the Metrics: What Makes a Growth Fund "Top"?
Not all growth funds are created equal. To understand why the top ones matter, we must look at the technical specifications that separate elite performers from the pack. When evaluating these funds, several key performance indicators (KPIs) come into play.
Earnings Per Share (EPS) Growth
The hallmark of a growth fund is the underlying EPS growth of its holdings. Top funds typically target companies with projected EPS growth of 15% or higher over a three-to-five-year horizon. This metric is a direct indicator of a company’s profitability and its ability to scale operations efficiently.
Revenue Velocity and Sales Growth
While earnings are important, top-tier growth managers also look at sales growth. In 2026, many high-growth companies in the "Scale-Up" phase may prioritize market share over immediate bottom-line profits. Managers analyze the "Price-to-Sales" (P/S) ratio in conjunction with revenue acceleration to ensure they aren't just buying hype, but real-world adoption of a product or service.
The Role of Expense Ratios
The "cost of admission" matters significantly. A top growth fund isn't necessarily the one with the lowest fee, but the one that provides the best net return. However, in 2026, an expense ratio exceeding 1.25% for an actively managed growth fund is often scrutinized unless the fund consistently delivers significant alpha. Investors should look for funds that balance high-quality management with competitive pricing structures.
Comparing Growth Fund Categories
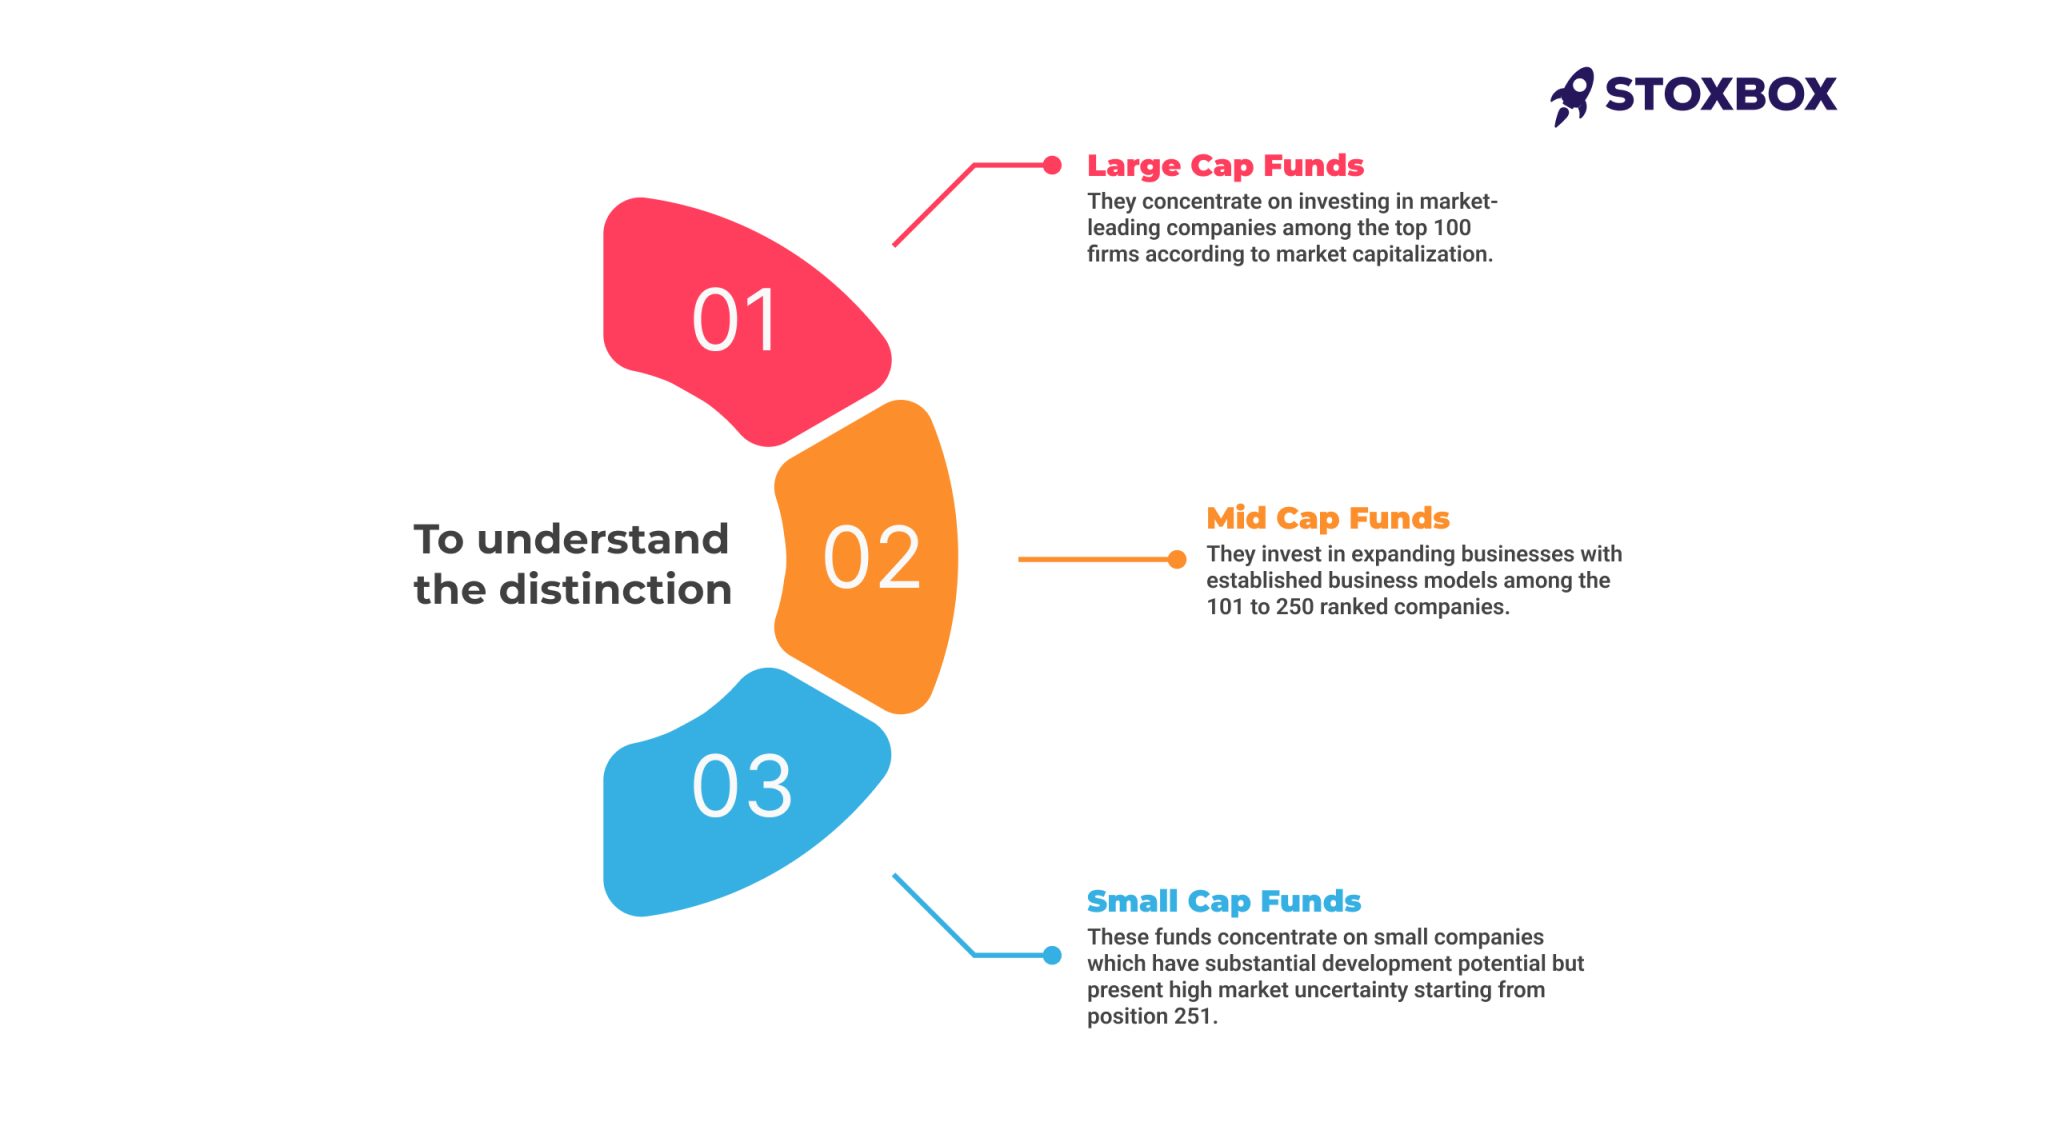
Growth funds are not a monolith; they are categorized by the size of the companies they invest in. Understanding these distinctions helps you decide which type of growth fund matters most for your specific risk tolerance.
| Fund Category | Typical Company Market Cap | Risk Profile | Primary Objective |
|---|---|---|---|
| Large-Cap Growth | $100 Billion+ | Moderate/High | Stability + Steady Growth |
| Mid-Cap Growth | $10 Billion - $100 Billion | High | Significant Capital Gains |
| Small-Cap Growth | Under $10 Billion | Very High | Explosive Growth Potential |
| Aggressive Growth | Varies (often Tech/Biotech) | Maximum | Maximum Capital Appreciation |
Large-Cap Growth Funds
These funds focus on established giants. These companies are often household names that have moved past their initial volatile phases but still innovate enough to grow faster than the S&P 500. They provide a "smoother" ride than smaller funds while still offering better returns than traditional "Value" or "Income" funds.
Small and Mid-Cap Growth Funds
This is where the "Top" managers really prove their worth. Finding a small company that will become a large-cap leader in ten years is the "Holy Grail" of investing. These funds are more volatile; they can drop 20% in a month just as easily as they can rise 20%. However, for a younger investor with a 20-year horizon, these funds are vital for significant wealth creation.
The Risks and Volatility Management
It is a mistake to view growth funds as a "sure thing." Their importance is balanced by the risks they carry, and a sophisticated investor must understand these mechanics.
Sensitivity to Interest Rates
Growth stocks are traditionally sensitive to interest rate hikes. This is because their valuations are based on "discounted future cash flows." When rates rise, the value of those future dollars decreases in today's terms. In the 2026 economic environment, top growth fund managers are distinguished by their ability to select "rate-resilient" companies—those with low debt and high cash reserves that can fund their own growth without relying on expensive borrowing.
Valuation Risk
Growth funds often trade at high Price-to-Earnings (P/E) ratios. The risk is that if a company misses an earnings estimate by even a small margin, the stock price can collapse as investors re-evaluate its growth trajectory. Top funds mitigate this by diversifying across sectors, ensuring that a slump in "SaaS" (Software as a Service) is offset by gains in "FinTech" or "Green Infrastructure."
How to Integrate Growth Funds into Your Portfolio
Growth funds matter because they fulfill a specific role in a diversified "Core and Satellite" strategy. For most investors in 2026, growth mutual funds should not be 100% of their portfolio, but they should be a significant "satellite" or even a portion of the "core."
- Determine Your Allocation: Depending on your age and goals, growth funds usually comprise 20% to 50% of an equity portfolio. A 30-year-old might lean toward 50%, while someone nearing retirement in 2028 or 2030 might scale back to 20% to preserve capital.
- Tax Considerations: Because growth funds focus on capital gains, they can be "tax-inefficient" in taxable accounts due to frequent trading by the manager (turnover). It is often more beneficial to hold high-turnover growth funds in tax-advantaged accounts like a 401(k) or an IRA.
- Consistency Over Timing: The "Top" funds matter most when held through full market cycles. Trying to "time" when to enter a growth fund often leads to missing the biggest days of gains. In 2026, the strategy remains: buy quality and stay invested.
Historical Context and the 2026 Outlook
Looking back at the early 2020s, we saw a massive surge in growth investing, followed by a period of consolidation. The "Top" funds that survived and thrived into 2026 are those that moved away from "growth at any cost" and toward "GARP" (Growth at a Reasonable Price).
In the current year, 2026, we see a stabilized market where the "froth" has been removed. This makes the selection of a growth fund even more important. You are no longer just "buying the market"; you are buying into the specific expertise of a fund family (such as Fidelity, Vanguard, or T. Rowe Price) that has the institutional memory to navigate complex global cycles.
Frequently Asked Questions
What is the main difference between a growth mutual fund and a value mutual fund?
A growth mutual fund invests in companies that are expected to grow earnings at an above-average rate compared to the market, often reinvesting all profits into the company. A value fund looks for companies that are currently "on sale" or undervalued by the market, often providing higher dividend yields. Growth funds aim for higher share price increases, while value funds aim for stability and income.
Are top growth mutual funds safe for retirement accounts?
They are considered a vital component of retirement accounts for those who have at least 10 years until retirement. While they are more volatile than bond funds or value funds, their higher historical returns are necessary to build a large enough nest egg to combat inflation over a 20- to 30-year retirement period. However, they should be balanced with more conservative investments as you approach your retirement date.
How do I check the "track record" of a growth fund?
In 2026, investors should look at the "10-year rolling return" and the "manager tenure." A fund might have a great one-year return due to luck or a single lucky stock pick, but a top fund demonstrates consistency over a decade. Check resources like Morningstar or the SEC’s EDGAR database for the fund's Prospectus and "Statement of Additional Information" (SAI) to see historical performance against its benchmark index, such as the Russell 1000 Growth Index.
What is an "Expense Ratio," and why does it matter for growth funds?
The expense ratio is the annual fee that all mutual funds charge their shareholders, expressed as a percentage of assets. For example, a 1% ratio means you pay $10 for every $1,000 invested. Because growth funds require more intensive research and active trading, their fees are often higher than passive index funds. It matters because high fees can compound over decades, significantly eating into your total returns. Always ensure the "alpha" provided by the manager justifies the fee.
Should I choose an actively managed growth fund or a growth index fund?
This depends on the market segment. In the "Large-Cap" space, it is very difficult for managers to beat the index consistently, so a low-cost growth index fund (like those tracking the Nasdaq-100) might be better. However, in "Mid-Cap" and "Small-Cap" growth sectors, active managers often provide significant value by avoiding "zombie companies" and finding hidden gems that the indices haven't picked up yet.
Final Recommendation: Your Next Steps
Top growth mutual funds matter because they represent the "engine" of your financial vehicle. Without them, your portfolio may struggle to outpace inflation and provide the significant capital required for a comfortable future.
Your next action: Review your current brokerage or retirement account. Identify the percentage of your assets currently in "Growth" categories. If you are under-allocated relative to your long-term goals, research three top-rated growth funds with a manager tenure of at least five years and an expense ratio below the category average. Consult with a financial advisor to ensure any new investment aligns with your specific risk tolerance and 2026 financial outlook.
Disclaimer: This article is for informational purposes only and does not constitute professional financial, investment, or legal advice. Investing in mutual funds involves risk, including the potential loss of principal. Past performance is not indicative of future results.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
