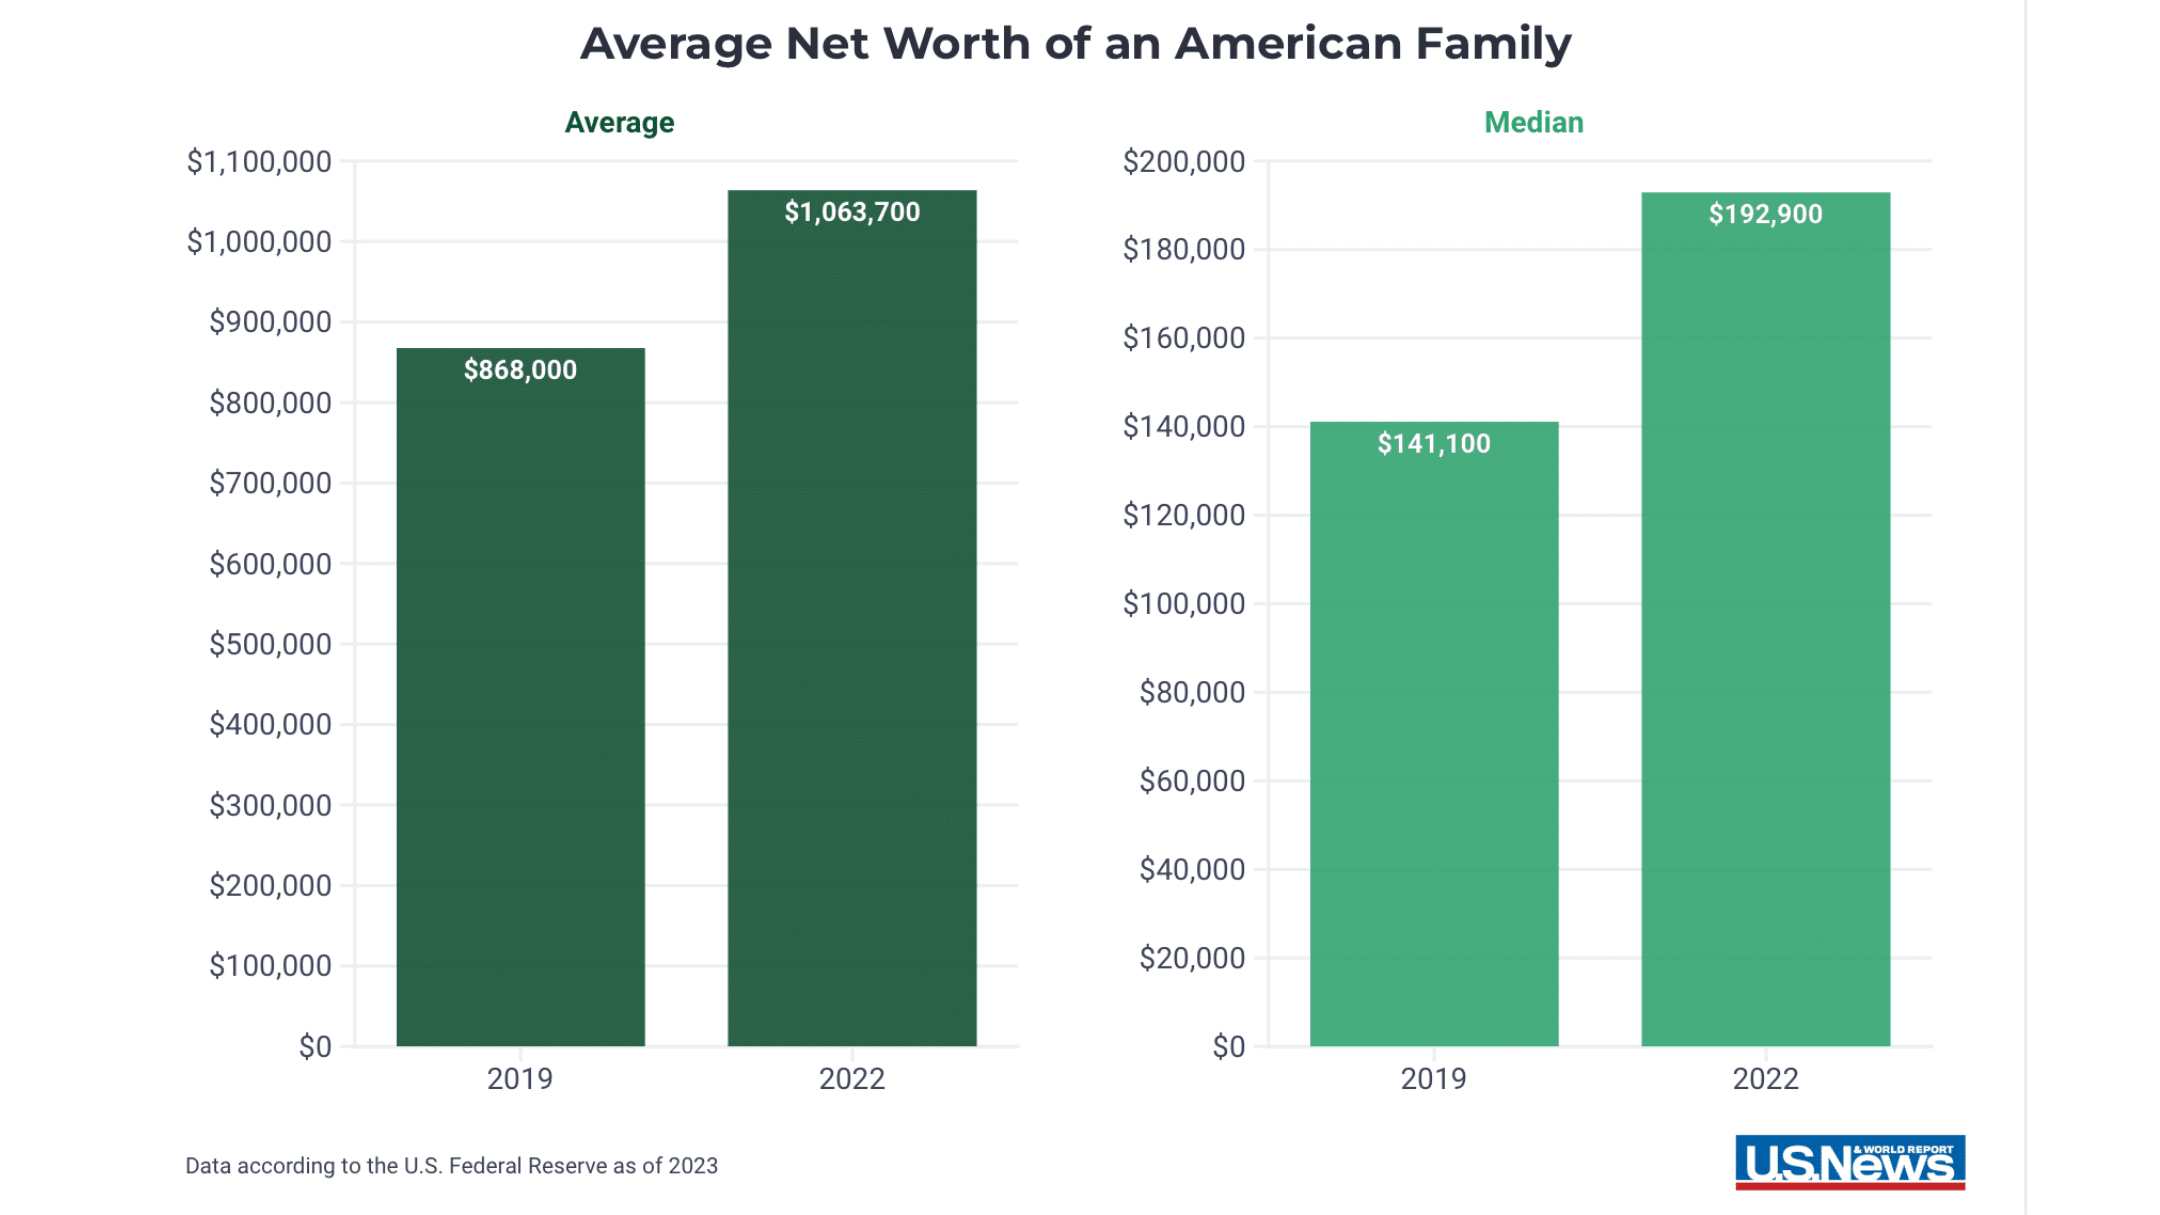
Net worth is a fundamental accounting equation representing the difference between what an individual or entity owns and what they owe. While often associated with wealth accumulation, net worth is not inherently a positive number; it can be zero or negative, reflecting a state where liabilities exceed assets.
In the realm of personal and corporate finance, net worth serves as a primary snapshot of financial health. It is calculated by subtracting all liabilities—such as credit card debt, mortgage balances, student loans, and other financial obligations—from the total value of all assets, including cash, investments, real estate, and personal property. When an individual’s or a business's debt burden surpasses the liquidation value of their assets, the result is a negative net worth, often referred to as being "underwater" or having a deficit.
The Accounting Equation: Assets Minus Liabilities
At its core, net worth is derived from the basic accounting equation: Assets - Liabilities = Net Worth (Equity). To understand why net worth can fall below zero, one must first deconstruct these two primary components.
Assets represent items of economic value that an individual or entity owns with the expectation that they will provide a future benefit. These are categorized into liquid assets, such as checking and savings accounts, and illiquid assets, such as retirement accounts (like a 401(k) or IRA), primary residences, automobiles, and business interests.
Liabilities are the claims against these assets. They include any form of debt or financial commitment that must be settled in the future. Common liabilities include:
- Secured Debt: Mortgages and auto loans where the asset itself serves as collateral.
- Unsecured Debt: Credit card balances, personal loans, and medical debt.
- Contingent Liabilities: Potential obligations that depend on the outcome of future events, such as lawsuits or guarantee obligations.
Because the total value of assets is not bounded by the total value of liabilities, the resulting difference can mathematically be any real number. If a recent graduate holds $50,000 in student loan debt but owns only $5,000 in personal property, their net worth is -$45,000. This is a common financial phase for many people early in their careers and does not necessarily indicate a permanent lack of financial viability, but rather a reflection of the current imbalance between debt and equity.
Why Negative Net Worth Occurs
Negative net worth is a reality for millions of households and many start-up businesses. It is not an error in calculation, but rather a functional status that changes over time as debts are paid down and assets are acquired or appreciate in value.
1. The Impact of Leverage
Leverage, or the use of borrowed capital, is a common driver of negative net worth. When an individual purchases a home with a small down payment, they have high initial debt relative to the equity they own in the property. If the property value declines (a state known as negative equity), the homeowner may owe more on their mortgage than the home is worth.
2. Education and Human Capital
In the modern economy, individuals often take on significant debt to finance education. While this debt is a clear liability, the "asset" created—human capital, or future earning potential—is difficult to quantify on a traditional balance sheet. Consequently, young professionals often display a negative net worth even though they possess a high potential for future income.
3. Business Startup Phases
Businesses frequently operate with a negative net worth in their early stages. Founders may invest heavily in research, development, and infrastructure before generating significant revenue. These start-up costs are often financed through debt, causing liabilities to significantly outweigh the company's tangible assets until the business model scales and profitability is achieved.
Measuring Financial Progress Over Time
Tracking net worth periodically provides a clearer picture of financial trajectory than looking at income alone. An individual with a high income but even higher spending and debt service may have a lower net worth than an individual with a modest income who maintains low debt levels and consistent savings.
| Metric | Purpose | Effect on Net Worth |
|---|---|---|
| Debt Repayment | Reduces total liabilities | Increases Net Worth |
| Asset Appreciation | Increases value of existing assets | Increases Net Worth |
| New Debt Acquisition | Increases total liabilities | Decreases Net Worth |
| Asset Depreciation | Reduces value of physical goods | Decreases Net Worth |
By analyzing these changes annually, individuals can determine if their financial strategies are working. A move from a negative net worth toward a positive one is a clear indicator of financial progress, even if the absolute number has not yet crossed the zero threshold.
Common Misconceptions Regarding Net Worth
A prevalent myth in financial discourse is that net worth is a measure of current liquidity or monthly cash flow. This is a significant misunderstanding. A person can have a high, positive net worth while struggling to pay their monthly bills if their assets are entirely illiquid, such as being locked in a primary residence or a retirement fund.
Conversely, someone with a negative net worth might have a very high, positive cash flow, allowing them to service their debt comfortably while steadily increasing their equity. It is crucial to view net worth as a stock variable—a snapshot at a specific point in time—rather than a flow variable, which would describe the movement of money over a period, such as income or expenses.
Another misconception is that negative net worth is a sign of financial failure. While persistent and growing negative net worth (especially if driven by high-interest consumer debt) can lead to insolvency, it is often a structural component of life-cycle finance. For instance, using debt to acquire assets that appreciate, such as real estate or business capital, is a strategic use of debt. The key distinction lies in the nature of the debt: productive debt versus consumption-based debt.
Strategic Management of Financial Equity
To manage net worth effectively, one must look at both sides of the balance sheet. Simply focusing on increasing income is often insufficient if the cost of living—and the debt incurred to maintain it—rises at a commensurate rate.
- Debt Restructuring: Consolidating high-interest debt can reduce the monthly cost of liabilities, allowing for faster principal repayment.
- Asset Allocation: Ensuring that assets are growing faster than the cost of the liabilities used to purchase them is essential for wealth creation.
- Inflation Awareness: In inflationary environments, the real value of fixed-rate debt actually decreases over time. This is a subtle but important factor in why negative net worth is not always as detrimental as it may appear on paper; if you owe money at a low, fixed interest rate, inflation is effectively reducing the "real" value of your debt.
Professional Financial Guidance
While calculating net worth is a straightforward arithmetic task, interpreting it and formulating a strategy based on that number can be complex. Financial advisors often suggest that individuals use net worth as a compass rather than a scorecard. If your net worth is negative, the goal should be to identify the root cause. Is it a temporary result of investment in education or a home? Or is it the result of chronic deficit spending?
For those with significant assets and complex liabilities, professional assistance can help in tax planning and optimizing the structure of debt. Jurisdictional tax laws in the United States and abroad often treat different types of debt and assets uniquely; for example, the interest on mortgage debt may be tax-deductible under certain conditions, which can alter the effective cost of that liability.
Limitations of the Net Worth Calculation
The traditional net worth formula has limitations, particularly when it comes to intangible assets. Most net worth calculations do not include the value of a person's future earning power, their professional network, or the value of their education and skills. These "intangible assets" are often the most valuable components of an individual's financial reality but are excluded because they are difficult to value objectively.
Similarly, personal property—such as clothing, electronics, or furniture—is often included at "liquidation value" rather than replacement cost. This leads to a conservative estimate of net worth, as these items lose value rapidly but are essential for daily functioning.
Frequently Asked Questions
Does a negative net worth mean I am bankrupt? No. Bankruptcy is a legal status involving a court process to discharge or reorganize debts. A negative net worth simply means your debts currently exceed the total value of your assets. Many people maintain a negative net worth for years while successfully meeting all their financial obligations.
Should I include my home in my net worth calculation? Yes, but you must include both the estimated market value of the home and the remaining balance on your mortgage. This gives you your "home equity," which is the amount you would theoretically have if you sold the home and paid off the loan today.
How often should I calculate my net worth? An annual calculation is typically sufficient for most people. Tracking it too frequently, such as weekly or monthly, can lead to unnecessary anxiety over minor market fluctuations in your investments or changes in property value that do not affect your long-term financial security.
Is it possible for net worth to be zero? Yes. A net worth of zero means your assets and liabilities are exactly equal. This is often referred to as "breaking even." It is a neutral financial state that rarely persists, as even small changes in interest, asset prices, or debt payments will tip the balance in one direction or the other.
Does a high net worth guarantee financial security? Not necessarily. If your net worth is tied up in a single, illiquid asset, you could have a high net worth but lack the cash flow required to cover basic living expenses during an emergency. Liquidity is just as important as total net worth.
Final Recommendation
To effectively utilize the concept of net worth in your financial planning, perform an annual audit of your balance sheet. List your total assets and total liabilities, ensuring that your asset valuations are realistic and based on current market data rather than original purchase price. If you find your net worth is negative, do not be discouraged; view it as a baseline to improve upon. Focus on the actionable steps of reducing high-interest liabilities and prioritizing the acquisition of income-generating or appreciating assets. By consistently monitoring this metric over the coming years, you will gain a clearer understanding of your progress toward your long-term financial objectives.

Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
