A $500,000 life insurance policy provides a half-million-dollar tax-free death benefit to designated beneficiaries upon the insured's passing. It bridges the financial gap for replacement income, debts, and future expenses, functioning primarily through either temporary term insurance or permanent coverage structures tailored to distinct budgetary and estate planning goals.
The Core Concept and Purpose of a Half-Million-Dollar Policy
Securing a financial safety net is one of the most critical steps in long-term household and business planning. When individuals look into a $500,000 life insurance policy, they are typically evaluating a mid-tier coverage amount designed to replace a multi-decade income stream, cover a substantial mortgage balance, and fund future educational milestones for dependents.
At its core, life insurance is a contract between an individual and an insurance provider. In exchange for regular payments—known as premiums—the insurer agrees to pay a lump-sum financial benefit to the policyholder's beneficiaries upon the insured’s death. A half-million-dollar face value represents a significant cushion, making it essential to understand how different policy structures operate, what they cost, and how underwriting affects approval.
Term Life Insurance vs. Permanent Life Insurance
Before committing to a policy, applicants must choose between two primary categories: term life insurance and permanent life insurance. Each serves vastly different timelines and financial strategies.
Term Life Insurance
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. If the insured passes away during this timeframe, the beneficiaries receive the $500,000 payout. If the term expires and the policy has not been renewed or converted, the coverage ends, and no benefits are paid.
- Affordability: Term policies offer the highest death benefit per dollar of premium, making a $500,000 policy accessible for young families and individuals on tight budgets.
- Simplicity: These policies feature straightforward structures with fixed premiums that do not change over the selected term length.
- Lack of Cash Value: Unlike permanent options, standard term policies do not build cash value or equity over time.
Permanent Life Insurance
Permanent life insurance, which includes whole life and universal life policies, provides lifetime coverage as long as premiums are paid. These policies also include a cash-value component that grows on a tax-deferred basis, allowing policyholders to borrow against it or withdraw funds under specific conditions.
- Lifelong Security: The coverage never expires, ensuring that beneficiaries will eventually receive the $500,000 payout regardless of how long the insured lives.
- Cash Value Accumulation: A portion of each premium payment enters a savings or investment vehicle, building tangible monetary value over decades.
- Higher Costs: Premiums for permanent coverage are substantially higher—often five to ten times more expensive than term insurance for the same face value—making affordability a primary constraint.
How Underwriters Determine Eligibility and Rates
Insurance companies do not offer $500,000 policies arbitrarily. They evaluate risk through a rigorous underwriting process to determine the likelihood of a payout during the policy term or expected lifespan. Several key factors directly influence approval and pricing:
- Age: Younger applicants represent a lower statistical risk, securing significantly lower rates. Securing a policy in your 20s or 30s locks in rates that are fractions of what they would cost in your 50s or 60s.
- Health History: Medical exams, blood work, and prescription history checks assess current health and predisposition to chronic illnesses such as cardiovascular disease, diabetes, or cancer.
- Lifestyle and Occupation: High-risk hobbies (such as skydiving or private aviation) and dangerous occupations (such as commercial fishing or structural ironwork) can increase premiums or lead to exclusions.
- Family Medical History: Insurers review the medical history of parents and siblings to gauge hereditary health risks.
- Driving Record: Frequent speeding tickets, DUIs, or major moving violations indicate behavioral risk, impacting overall rates.
Cost Factors for a $500,000 Policy
The monthly or annual cost of a $500,000 life insurance policy varies wildly depending on the type of policy and the profile of the insured. For a healthy 30-year-old nonsmoker, a 20-year term policy might cost between $20 and $30 per month. Conversely, a whole life policy for the same individual could easily exceed $300 to $400 per month due to the lifetime guarantee and cash-value accumulation.
Smokers or individuals with controlled medical conditions like hypertension can expect rates to double or triple. Working with an independent insurance broker allows applicants to shop multiple carriers, ensuring they find a company whose underwriting guidelines look favorably upon their specific health profile.
Comparing Policy Types: Term vs. Permanent
| Feature | Term Life Insurance | Whole Life Insurance (Permanent) | Universal Life Insurance (Permanent) |
|---|---|---|---|
| Duration | Specific period (10–30 years) | Lifetime (To age 100 or death) | Lifetime (Flexible structure) |
| Cash Value | None | Yes (Guaranteed growth) | Yes (tied to interest or market indexes) |
| Premium Cost | Low and level | High and fixed | Flexible adjustments possible |
| Best For | Income replacement, mortgage protection | Estate planning, lifelong dependents | Flexible long-term wealth accumulation |
Common Misconceptions About Life Insurance Payouts
Policyholders and beneficiaries often misunderstand how life insurance interacts with taxes, creditors, and legal processes. Clarifying these details prevents unexpected complications during emotionally difficult times.
Tax Treatment of the Death Benefit
In most jurisdictions, the $500,000 payout from a life insurance policy is received by beneficiaries completely income-tax-free. However, if the policy is owned improperly—such as if the policyholder is also the insured and names their estate as the beneficiary—the funds may become subject to probate fees and potential estate taxes. Setting up proper ownership or utilizing an irrevocable life insurance trust (ILIT) can mitigate large estate tax liabilities.
Creditor Protection
Depending on local state or provincial laws, life insurance death benefits paid to named beneficiaries are generally shielded from the deceased person's creditors. This ensures that the financial safety net remains intact for dependents rather than being redirected to settle outstanding consumer debts or credit cards.
Steps to Choosing and Applying for Coverage
Navigating the marketplace for a $500,000 policy requires a methodical approach to ensure adequate protection without overpaying.
- Calculate Financial Needs: Assess total outstanding debts, mortgage balances, immediate final expenses, and the number of years dependents will need income replacement. A $500,000 policy is a solid benchmark, but larger households may require more.
- Select the Right Term or Permanent Structure: Balance your budget against your timeline. If the financial obligation diminishes in 20 years (e.g., children graduate college, mortgage is paid off), a 20-year term policy is typically the most efficient choice.
- Get Multiple Quotes: Request pricing from at least three different insurers to compare underwriting offers.
- Complete the Medical Examination: Prepare for the paramedical exam by staying hydrated, avoiding heavy meals or caffeine beforehand, and gathering a complete list of current medications.
- Review and Finalize the Contract: Carefully read the policy provisions, grace periods, conversion options, and rider details before signing.
Frequently Asked Questions
Is a $500,000 life insurance policy enough for an average family?
Whether $500,000 is sufficient depends on current income, debt obligations, and future expenses. Financial planners often recommend a coverage amount equal to 10 to 15 times your annual salary, making a half-million-dollar policy ideal for individuals earning between $35,000 and $50,000 annually with moderate debt. Higher earners or larger families may need to supplement this with additional coverage or a larger policy.
Can I convert a term policy into a permanent policy later?
Many term life insurance policies include a conversion rider that allows the policyholder to switch to a permanent policy—such as whole life—without undergoing a new medical exam. This is a valuable feature for individuals who initially buy term for affordability but anticipate wanting lifelong coverage later in life.
What happens if I outlive my term life insurance policy?
If you outlive a term policy, the coverage simply expires. You will no longer pay premiums, but your beneficiaries will no longer receive a payout if you pass away. Options at expiration include letting the policy lapse, renewing it on a year-to-year basis (usually at significantly higher rates), or converting it if your policy allows.
Are premiums tax-deductible?
For personal life insurance policies, premiums are generally not tax-deductible. The trade-off is that the death benefit is paid out to your beneficiaries completely free of income tax. Business-owned life insurance policies follow entirely different tax rules and require consultation with a qualified tax professional.
What is an accelerated death benefit rider?
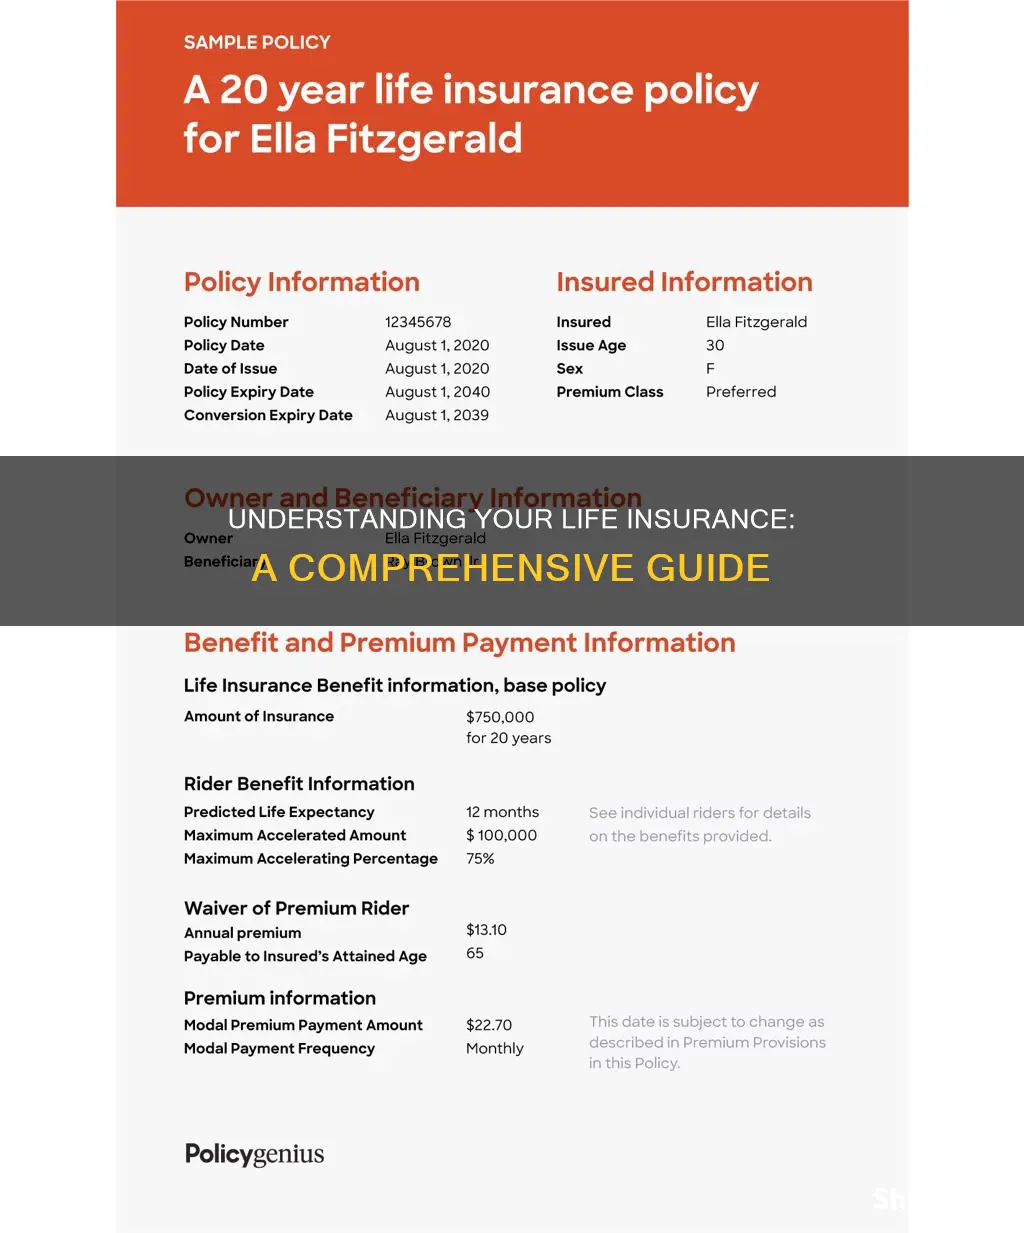
An accelerated death benefit rider allows the insured to access a portion of the $500,000 face value while still alive if they are diagnosed with a terminal illness with a limited life expectancy. This money can be used to pay for medical treatments, home care, or end-of-life expenses, reducing the final payout received by beneficiaries.
Next Actions for Secure Financial Planning
Evaluating a $500,000 life insurance policy begins with an honest assessment of your family's financial obligations if your income were to disappear tomorrow. Gather your financial statements, calculate your long-term liabilities, and speak with an independent insurance professional to compare term and permanent options tailored to your specific life stage and budget.
Image Gallery
Select an image to open it in a new tab.

Declan O'Connor
Higher Education and Campus Culture Reporter
