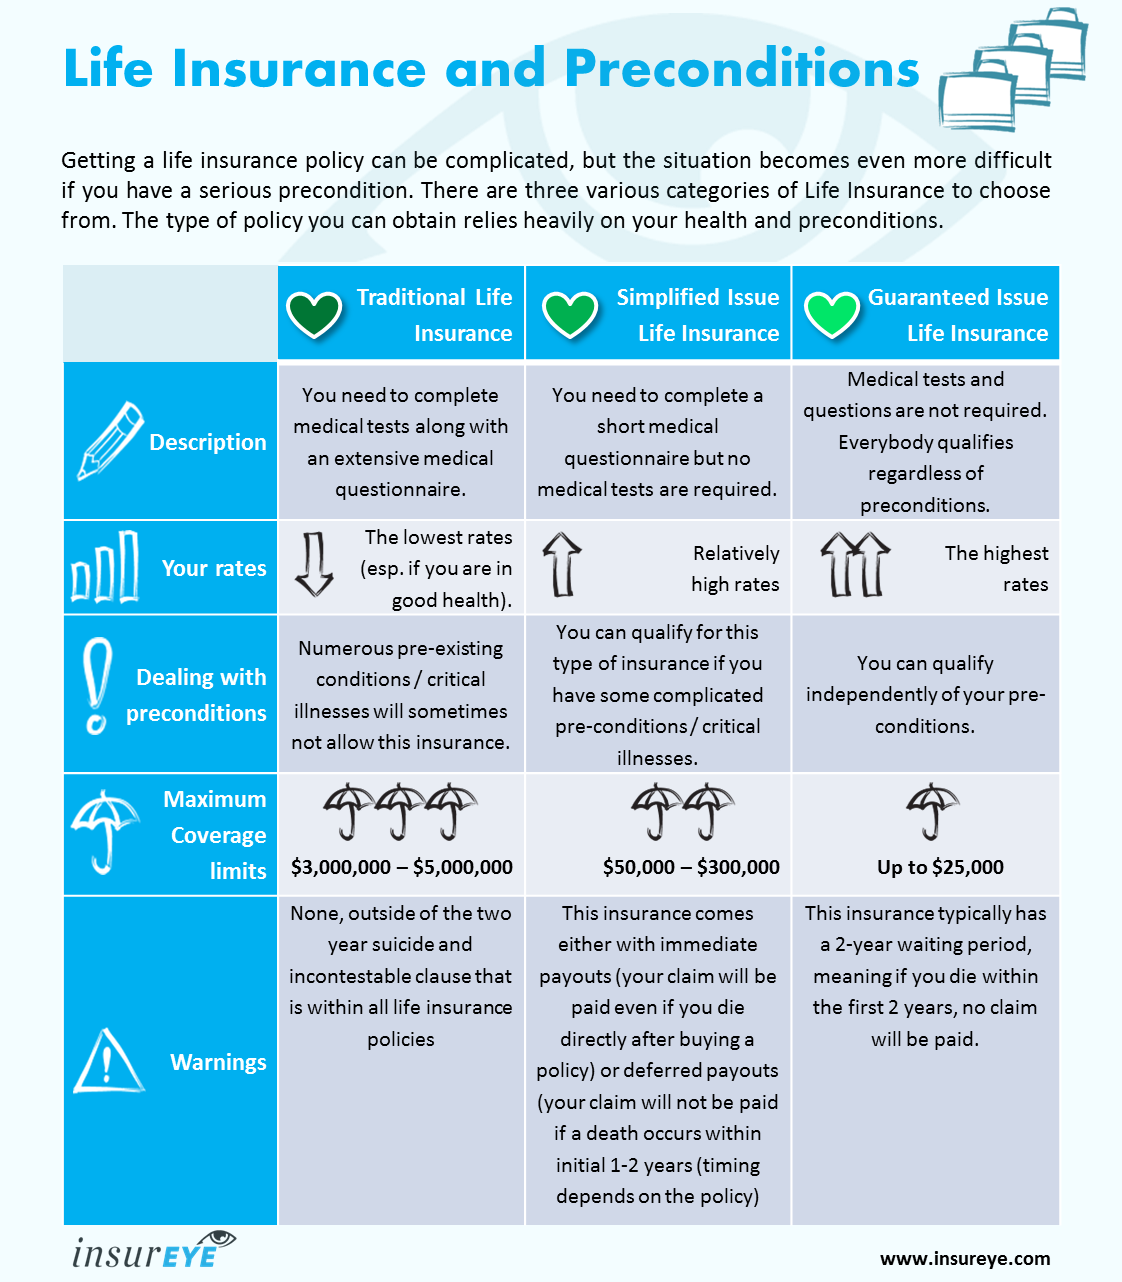
Life insurance policies are primarily categorized into term life insurance, which provides coverage for a specific period (such as 10, 20, or 30 years), and permanent life insurance, which offers lifelong protection and a cash value component. Within these categories, common variations include whole life, universal life, and variable life insurance, each offering different levels of premium flexibility, investment potential, and death benefit guarantees.
Selecting a life insurance policy is one of the most significant financial decisions an individual can make. As of 2026, the insurance market has evolved to offer highly specialized products tailored to diverse economic needs, ranging from simple debt protection to complex estate planning tools. To choose the right policy, one must understand the structural differences between these products, their long-term cost implications, and how they align with specific financial goals.
Term Life Insurance: The Foundation of Temporary Protection
Term life insurance is the most straightforward and often the most affordable form of life insurance. It is designed to provide financial protection for a specific "term" or duration. If the insured individual passes away during this period, the insurance company pays a death benefit to the designated beneficiaries. If the term expires while the policyholder is still living, the coverage simply ends unless the policy includes a renewal or conversion option.
Level Term Life Insurance
Level term is the most common variety. The "level" refers to both the premium and the death benefit remaining constant throughout the entire duration of the policy. For example, if you purchase a 20-year, $500,000 policy in 2026, your monthly premium and the $500,000 payout remain identical in year one and year twenty. This predictability makes it a favorite for families looking to cover specific milestones, such as the duration of a mortgage or the years until children graduate from college.
Decreasing Term Life Insurance
Often used as "mortgage protection insurance," decreasing term policies feature a death benefit that reduces over time, usually in monthly or annual increments. The logic behind this structure is that as you pay down your large debts (like a home loan), your need for high-level coverage diminishes. While the premiums usually remain level, they are typically lower than those of a standard level term policy because the insurer’s total risk decreases over time.
Increasing Term Life Insurance
Conversely, increasing term insurance allows the death benefit to grow over time. This is often used as a hedge against inflation or to match an expected increase in financial responsibilities. These policies are less common for individuals and are more frequently found in business contexts or as specialized riders attached to other policies.
Renewable and Convertible Term
Two critical features of modern term policies are renewability and convertibility. Guaranteed renewability allows the policyholder to extend their coverage at the end of the term without undergoing a new medical exam, though premiums will increase based on the insured's attained age. Convertibility allows the policyholder to change their term policy into a permanent policy (like whole life) without a medical exam. This is an invaluable feature for individuals who may develop health issues during their term that would otherwise make them uninsurable or prohibitively expensive to cover under a new policy.
Whole Life Insurance: Guaranteed Permanent Coverage
Whole life insurance is the most traditional form of permanent life insurance. It is designed to cover the insured for their entire life, provided the premiums are paid. Unlike term insurance, whole life includes a "cash value" component that grows over time on a tax-deferred basis.
The Mechanics of Cash Value
A portion of every premium payment in a whole life policy is diverted into a cash value account. The insurance company guarantees that this account will grow at a minimum interest rate. Policyholders can eventually borrow against this cash value or even surrender the policy to receive the accumulated funds. However, it is vital to understand that loans against the policy reduce the death benefit if they are not repaid before the insured's death.
Fixed Premiums and Death Benefits
One of the primary selling points of whole life insurance is its absolute stability. Premiums are locked in at the time of purchase and never increase, regardless of changes in health or age. Similarly, the death benefit is guaranteed. For individuals who want a "set it and forget it" solution for final expenses or legacy planning, whole life provides a level of certainty that other policies cannot match.
Participating vs. Non-Participating Policies
When exploring whole life, you will encounter "participating" policies. These are typically offered by mutual insurance companies. In a participating policy, the policyholder may receive "dividends" if the insurance company performs better than expected (lower mortality rates, better investment returns, or lower expenses). These dividends are not guaranteed but can be used to purchase additional coverage, reduce premium payments, or be taken as cash. Non-participating policies do not pay dividends but often feature lower initial premiums.

Universal Life Insurance: Flexibility and Control
Universal life (UL) insurance is a type of permanent life insurance that offers more flexibility than whole life. It allows the policyholder to adjust their premium payments and death benefits within certain limits set by the insurer. This makes it a popular choice for individuals whose income or financial needs fluctuate over time.
Flexible Premiums
In a universal life policy, as long as the cash value is sufficient to cover the monthly "cost of insurance" (COI) and administrative fees, the policyholder can choose to pay more, less, or even nothing at all for a period. This can be a lifesaver during times of financial hardship. However, if the cash value is exhausted, the policy will lapse, meaning the coverage ends.
Interest Rate Sensitivity
The growth of the cash value in a universal life policy is tied to current market interest rates. When rates are high, the cash value grows faster; when they are low, growth slows. This introduces a level of risk not found in whole life insurance. By 2026, many UL policies have evolved to include "no-lapse guarantees," which ensure the policy remains in force even if the cash value drops to zero, provided a specific minimum premium is paid.
Indexed Universal Life (IUL)
A subset of universal life that has gained significant traction is Indexed Universal Life. In an IUL policy, the cash value growth is tied to a specific stock market index, such as the S&P 500. While the policyholder does not directly invest in the stock market, the insurer credits interest based on the index's performance, usually subject to a "cap" (maximum return) and a "floor" (usually 0%, protecting against market losses). This allows for higher growth potential than traditional UL while maintaining a safety net against market downturns.
Variable and Variable Universal Life Insurance
Variable life insurance products are designed for those who want to take an active role in the investment of their policy's cash value. These products are considered securities and are regulated by both insurance departments and the Securities and Exchange Commission (SEC).
Investment Options
Unlike whole or universal life, where the insurer manages the underlying investments, variable life allows the policyholder to allocate their cash value among various "sub-accounts," which function similarly to mutual funds. These sub-accounts can include stocks, bonds, and money market funds.
Risk and Reward
The death benefit and cash value in a variable policy can fluctuate based on the performance of the chosen investments. While there is the potential for significant wealth accumulation, there is also the risk that the cash value could decrease. Variable Universal Life (VUL) combines the investment options of variable life with the premium flexibility of universal life, creating the most complex and potentially rewarding (or risky) type of life insurance available.
Specialized Life Insurance Policies
Beyond the standard categories, several specialized policies exist to address specific needs or group settings.
- Final Expense Insurance: Also known as "burial insurance," these are small whole life policies (typically $5,000 to $25,000) designed specifically to cover funeral costs and small debts. They often feature "graded death benefits," meaning if the insured dies within the first two years, the beneficiaries receive only a return of premiums plus interest.
- Group Life Insurance: This is coverage offered by an employer or association. It is usually term insurance and is often provided for free or at a very low cost up to a certain limit (e.g., 1x annual salary). The primary disadvantage is that coverage typically ends when the employee leaves the company.
- Accidental Death and Dismemberment (AD&D): This is not traditional life insurance. It only pays out if the insured dies or is severely injured due to a covered accident. It does not cover death by natural causes or illness.
- Joint Life Insurance: These policies cover two people (usually spouses). First-to-die policies pay out when the first person passes, helping the survivor with immediate expenses. Second-to-die (survivorship) policies pay out only after both individuals have passed, and are primarily used for estate tax planning.
Comparison Table: Key Differences Between Major Policy Types
The following table compares the primary characteristics of the most common life insurance types to help you identify which might suit your financial profile.
| Feature | Term Life | Whole Life | Universal Life | Variable Life |
|---|---|---|---|---|
| Duration | Fixed term (e.g., 10-30 years) | Lifelong | Lifelong | Lifelong |
| Premium Cost | Lowest initial cost | Higher initial cost | Flexible/Moderate | Varies with market |
| Cash Value | None | Guaranteed growth | Market-linked interest | Investment-based |
| Death Benefit | Fixed | Guaranteed | Flexible/Adjustable | Can fluctuate |
| Best For | Income replacement, debts | Final expenses, legacy | Flexible budgets | High-net-worth/Investors |
| Complexity | Low | Low to Moderate | Moderate to High | High |
Riders: Customizing Your Policy
Riders are optional add-ons that allow you to customize a policy to your specific needs. While they often come with an additional cost, they provide essential protections that a standard policy might lack.
- Waiver of Premium: If you become totally disabled and cannot work, the insurance company waives your premium payments while keeping the policy in force.
- Accelerated Death Benefit: This allows a terminally ill policyholder to access a portion of the death benefit while they are still alive to pay for medical care or hospice.
- Child Term Rider: Provides a small amount of life insurance for the policyholder’s children. This can usually be converted to a permanent policy when the child reaches adulthood.
- Long-Term Care (LTC) Rider: Increasingly popular in 2026, this rider allows the policyholder to use part of the death benefit to pay for long-term care services, such as a nursing home or in-home health aide.
Factors to Consider When Choosing a Policy
The "best" life insurance policy is entirely subjective and depends on your current financial stage. When evaluating your options, consider these four pillars:
- Financial Goals: Are you trying to protect a 30-year mortgage (Term), or are you trying to leave a tax-free inheritance to your grandchildren (Whole/Universal)?
- Budget Sustainability: A permanent policy is only effective if you can afford the premiums for decades. If there is a risk that high premiums will force you to drop the policy in five years, a more affordable term policy is the safer choice.
- Risk Tolerance: Are you comfortable with your cash value fluctuating with the stock market (Variable), or do you require a guaranteed rate of return (Whole)?
- Health Status: Your current health significantly impacts your "rating" and premium costs. Those in excellent health can qualify for "Preferred Plus" rates, making permanent insurance more accessible. Those with chronic conditions may find "Simplified Issue" or "Guaranteed Issue" policies (which require no medical exam) to be their only viable options.
Frequently Asked Questions
Can I have more than one type of life insurance policy at the same time? Yes, it is common and often recommended to "ladder" policies. For example, you might carry a large 20-year term policy to protect your children during their school years, while simultaneously maintaining a smaller whole life policy to cover final expenses later in life.
What happens if I stop paying premiums on a permanent policy? Unlike term insurance, which simply cancels, permanent policies have "non-forfeiture options." You may be able to use the accumulated cash value to pay the premiums (Automatic Premium Loan), convert the policy to a smaller "paid-up" policy with no further premiums due, or surrender the policy for its current cash value (minus any fees).
Is the death benefit from life insurance taxable? In most cases, the death benefit paid to beneficiaries is not subject to federal income tax. However, if the death benefit is paid to your estate rather than a named beneficiary, it may be subject to federal estate taxes if the total estate value exceeds certain thresholds. As of 2026, it is wise to consult a tax professional regarding current state-level inheritance taxes.
What is the difference between "Level Term" and "Increasing Term"? In a Level Term policy, the payout stays the same (e.g., $1 million) for the duration of the policy. In an Increasing Term policy, the payout grows every year. Increasing term is usually more expensive because the insurer's potential payout grows as you get older and the statistical likelihood of death increases.
What is "Convertible" life insurance? Convertible life insurance is a feature on many term policies that allows you to change the term policy into a permanent one (like whole life) within a certain timeframe. You do not have to provide proof of good health or take a medical exam to convert, which is a major benefit if your health has declined since you first bought the policy.
Next Action: To determine the exact amount of coverage you need, perform a "DIME" analysis. Calculate your Debt, Income (multiplied by the number of years you want to replace it), Mortgage balance, and Education costs for your children. Once you have this total, consult with an independent insurance agent who can compare quotes from multiple carriers to find the policy type that fits your specific 2026 financial outlook.
Disclaimer: This article provides general information and is not intended as financial, legal, or tax advice. Life insurance regulations and product availability can vary by jurisdiction. Always consult with a licensed financial professional before making insurance decisions.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
