Refinancing a mortgage typically costs between 2% and 6% of the new loan’s principal amount. These expenses, collectively known as closing costs, include lender fees, third-party services like appraisals and title insurance, and government taxes. Understanding these upfront expenditures is essential for determining the break-even point and overall financial benefit.
The Comprehensive Breakdown of Refinance Closing Costs
When you refinance your mortgage in 2026, you are essentially replacing your existing loan with a new one. This process requires many of the same administrative and legal steps as your original home purchase. Because these services involve multiple professional entities—lenders, appraisers, title companies, and local governments—the costs can accumulate quickly.
Lender-Related Fees
Lender fees represent the administrative costs of processing your application and securing the new loan. These are often the most negotiable parts of the refinance process.
- Application Fee: This covers the initial processing of your request and the cost of pulling your credit report. While some lenders waive this to attract business, others charge between $100 and $500.
- Loan Origination Fee: This is usually the largest lender fee, often calculated as 0.5% to 1.5% of the loan amount. It covers the evaluation and preparation of your mortgage. For a $400,000 loan, an origination fee of 1% would cost $4,000.
- Discount Points: Homeowners often choose to pay "points" to lower their interest rate. One point equals 1% of the loan amount. While this increases your upfront cost, it reduces your monthly payment and total interest paid over the life of the loan.
- Mortgage Broker Fee: If you use a broker to find the best rate, they may charge a fee, typically 1% to 2% of the loan amount, though this is often paid by the lender and built into the interest rate.
Third-Party Professional Services
Lenders require several third-party evaluations to ensure the property’s value and legal standing justify the new loan.
- Appraisal Fee: A licensed appraiser must determine the current market value of your home. In 2026, standard residential appraisals generally cost between $400 and $900, though unique properties or high-demand areas may see higher rates. This ensures the lender is not providing a loan for more than the home is worth.
- Title Search and Insurance: Even though you already own the home, the lender requires a new title search to ensure there are no new liens or legal encumbrances. You will also need to purchase a lender’s title insurance policy. Unlike the owner's policy you bought when you purchased the home, the lender's policy protects the bank's interest in the property. These costs vary significantly by state but often range from $700 to $2,000.
- Credit Report Fee: Lenders pull a comprehensive "tri-merge" credit report from Equifax, Experian, and TransUnion. This usually costs between $30 and $100.
- Attorney or Escrow Fees: Depending on your state's laws, a real estate attorney or an escrow company may be required to oversee the closing. These fees cover the handling of documents and the distribution of funds, typically costing $500 to $1,500.
Government and Regulatory Fees
These costs are non-negotiable and are dictated by local and state jurisdictions.
- Recording Fees: Your local county or municipal government charges a fee to update public records with the new deed of trust or mortgage information. This is usually a flat fee or a per-page charge, typically totaling $50 to $250.
- Transfer Taxes: Some states or municipalities charge a tax on the transfer of property or the recording of a new mortgage. In high-tax jurisdictions, this can be a significant expense, sometimes reaching 1% of the loan value.
Summary of Estimated Refinance Costs
The following table provides a generalized estimate of what a homeowner might expect to pay when refinancing a $350,000 mortgage in 2026.
| Fee Category | Estimated Cost Range | Description |
|---|---|---|
| Origination Fee | $1,750 – $3,500 | Lender's administrative and processing fee (0.5% - 1%). |
| Appraisal | $450 – $850 | Professional valuation of the property. |
| Title Services | $800 – $2,200 | Title search and lender’s title insurance policy. |
| Credit Report | $30 – $100 | Cost to pull comprehensive credit history. |
| Recording Fees | $50 – $250 | Local government fee for updating public records. |
| Application Fee | $0 – $500 | Initial fee to start the loan process. |
| Attorney/Closing | $500 – $1,200 | Professional oversight of the document signing. |
| Total Estimated | $3,580 – $8,600 | Total typically falls between 2% and 5% of loan value. |
Hidden Costs and Prepaid Items
Beyond the standard closing costs, homeowners must account for "prepaids" and potential penalties that can impact the total cash needed at closing.
Prepaid Interest and Escrow
When you close your loan, you will likely need to pay the interest that accrues between the closing date and the end of the month. Additionally, if your lender manages your property taxes and homeowners insurance through an escrow account, you may need to provide an initial deposit to "seed" the new account. While this isn't a fee for the refinance itself—as you would have paid these taxes and insurance anyway—it does increase the amount of capital required at the time of closing.
Prepayment Penalties
Before initiating a refinance, review your current mortgage contract for a prepayment penalty clause. While less common on modern conventional loans, some older or non-qualified mortgages charge a fee if you pay off the balance early. This penalty can be a flat fee or a percentage of the remaining balance, potentially negating the benefits of a lower interest rate.
Mortgage Insurance Adjustments
If your home's value has decreased or if you are doing a cash-out refinance that leaves you with less than 20% equity, you may be required to pay Private Mortgage Insurance (PMI). Conversely, if your home has appreciated significantly, refinancing could allow you to cancel your current PMI, which would be a major cost-saving benefit.
Analyzing the Break-Even Point
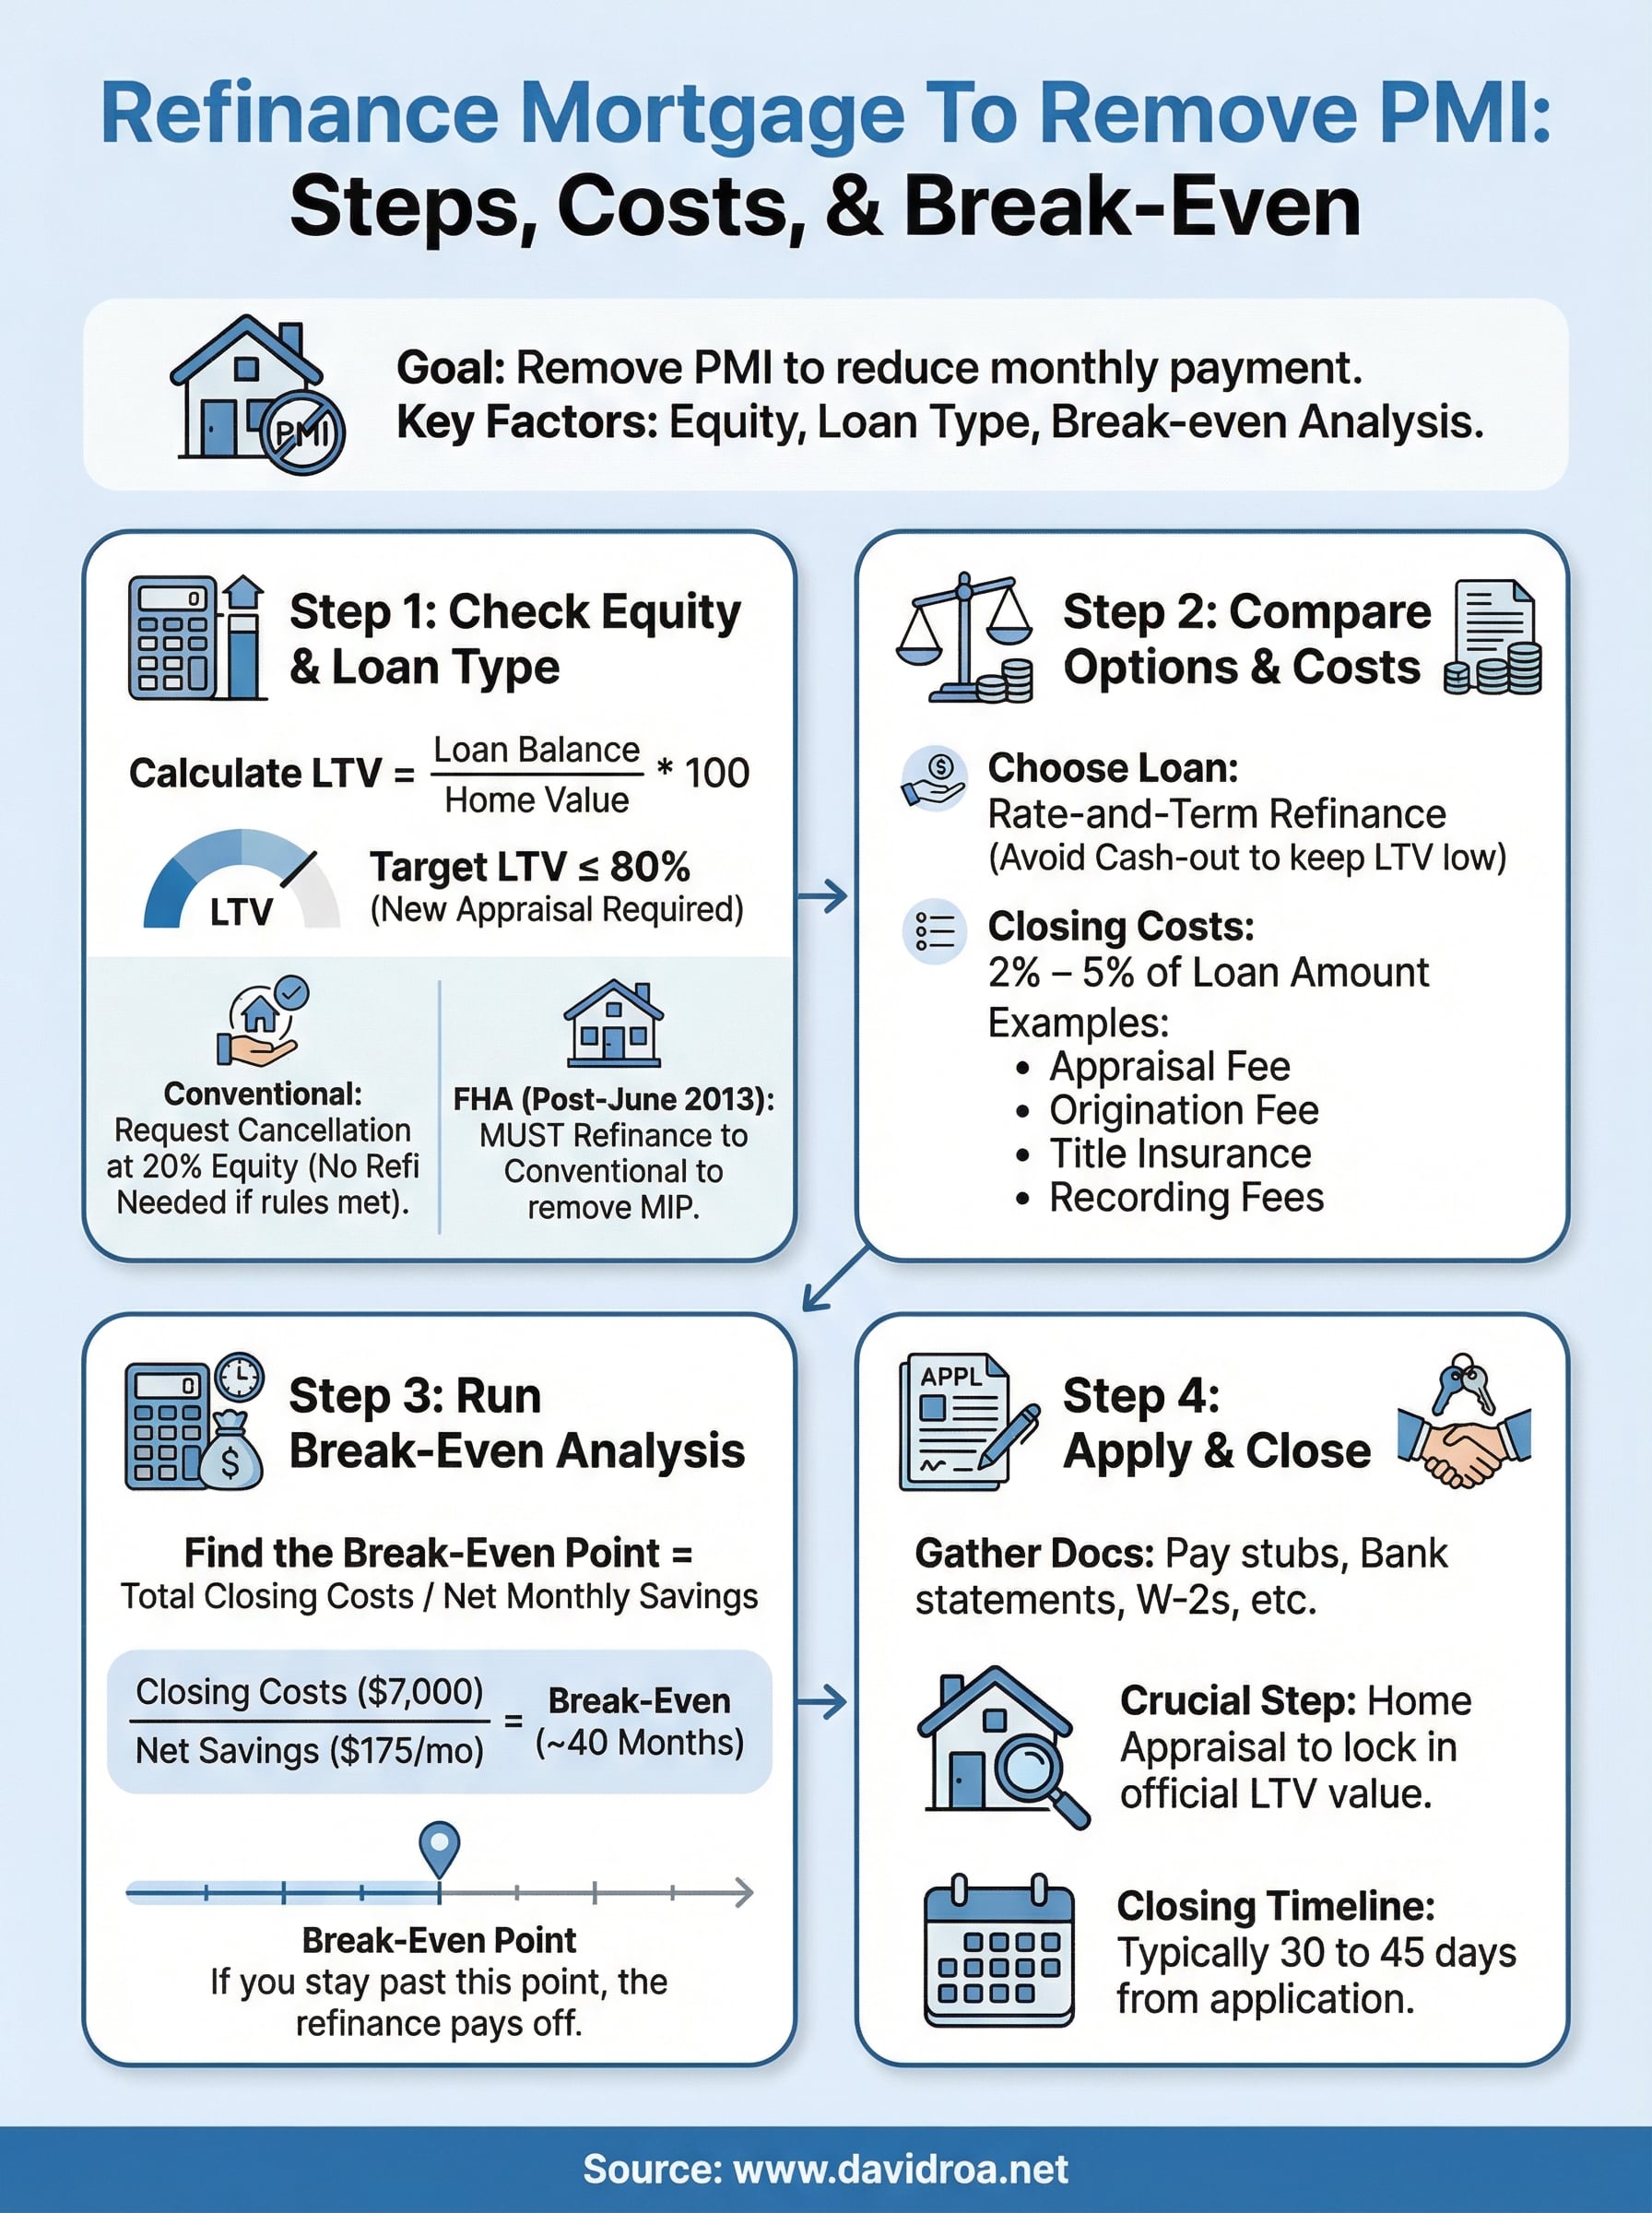
The most critical calculation in any refinance is the break-even analysis. This determines how many months it will take for your monthly savings to cover the total cost of the refinance.
To calculate this, divide the total closing costs by the monthly savings. For example, if your refinance costs $6,000 and reduces your monthly payment by $200, your break-even point is 30 months ($6,000 / $200 = 30). If you plan to sell the home or pay off the mortgage in less than 30 months, the refinance would result in a net loss.
In the 2026 market, with fluctuations in property values and interest rates, homeowners should aim for a break-even point of 36 months or less to ensure the move is financially sound.
The Reality of "No-Closing-Cost" Refinancing
Lenders frequently advertise "no-closing-cost" mortgages. It is important to understand that these are not "free" loans. Instead of paying the costs upfront, the lender covers them in exchange for a higher interest rate or by "rolling" the costs into the principal balance of the loan.
- Higher Interest Rate: If the market rate is 5.5%, a lender might offer a no-closing-cost option at 5.875%. Over the 30-year life of the loan, you will likely pay significantly more in interest than the original closing costs would have been.
- Financed Costs: Rolling the $6,000 in closing costs into a $400,000 loan means you are now paying interest on a $406,000 balance. This increases your monthly payment and reduces the equity you have in your home.
This option is often best for homeowners who lack the immediate cash for closing but intend to stay in the home for a short period, or for those who prioritize immediate cash flow over long-term interest savings.
Factors That Influence Your Specific Costs
Several variables can shift your refinance costs toward the higher or lower end of the 2% to 6% spectrum.
- Credit Score: Borrowers with scores above 760 typically receive better terms and lower Loan Level Price Adjustments (LLPAs). Lower credit scores can lead to higher fees or higher interest rates.
- Loan Type: Government-backed loans, such as FHA or VA loans, have specific fee structures. VA loans, for instance, often feature a "Funding Fee" but may have lower third-party costs. FHA refinances require an Upfront Mortgage Insurance Premium (UFMIP).
- Loan Amount: Since many fees are percentage-based, higher loan amounts naturally result in higher total costs. However, fixed costs like appraisals and credit reports become a smaller percentage of the total as the loan size increases.
- Property Location: States like New York, Florida, and Maryland have higher mortgage recording taxes compared to states like Arizona or Idaho.
Frequently Asked Questions
Can I negotiate the closing costs on a refinance?
Yes, many lender fees are negotiable. You can specifically ask for a reduction in the origination fee or ask the lender to match a competitor's lower fee structure. Third-party fees like the appraisal or government taxes are generally fixed and non-negotiable. It is highly recommended to obtain a Loan Estimate from at least three different lenders to compare these costs side-by-side.
Is an appraisal always required in 2026?
Not always. If you are performing a "Rate-and-Term" refinance and the lender has sufficient data on your property through automated valuation models, you may qualify for an appraisal waiver. This is more common in established neighborhoods with recent comparable sales. If granted, this can save you $500 or more and speed up the closing process.
How much equity do I need to refinance?
Generally, lenders prefer that you have at least 20% equity in your home to avoid PMI and access the best interest rates. However, it is possible to refinance with as little as 3% to 5% equity through certain conventional and FHA programs. For a cash-out refinance, most lenders require you to maintain at least 20% equity after the new loan is issued.
Are refinance closing costs tax-deductible?
In most cases, refinance closing costs are not immediately deductible in the year they are paid. However, points paid to reduce your interest rate can usually be deducted over the life of the loan. If you use a portion of a cash-out refinance for home improvements, that interest may also be deductible. You should consult a tax professional or refer to IRS Publication 936 for specific guidance.
Does a refinance affect my credit score?
The process involves a "hard inquiry" on your credit report, which can cause a temporary dip of a few points. However, if the refinance lowers your monthly debt obligation and you continue to make timely payments, it can improve your credit profile over the long term.
Practical Recommendation
Before moving forward with a mortgage refinance in 2026, conduct a thorough audit of your current loan terms and your long-term housing goals. If you plan to stay in the home for at least five years and can reduce your interest rate by at least 0.75% to 1%, the upfront costs are likely a sound investment. Always request a detailed breakdown of fees in the form of a Loan Estimate before committing to a lender. Use the break-even calculation as your primary decision-making tool: if the time it takes to recoup the $4,000 to $8,000 in costs exceeds your planned tenure in the home, the refinance is not financially beneficial regardless of the lower interest rate.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
