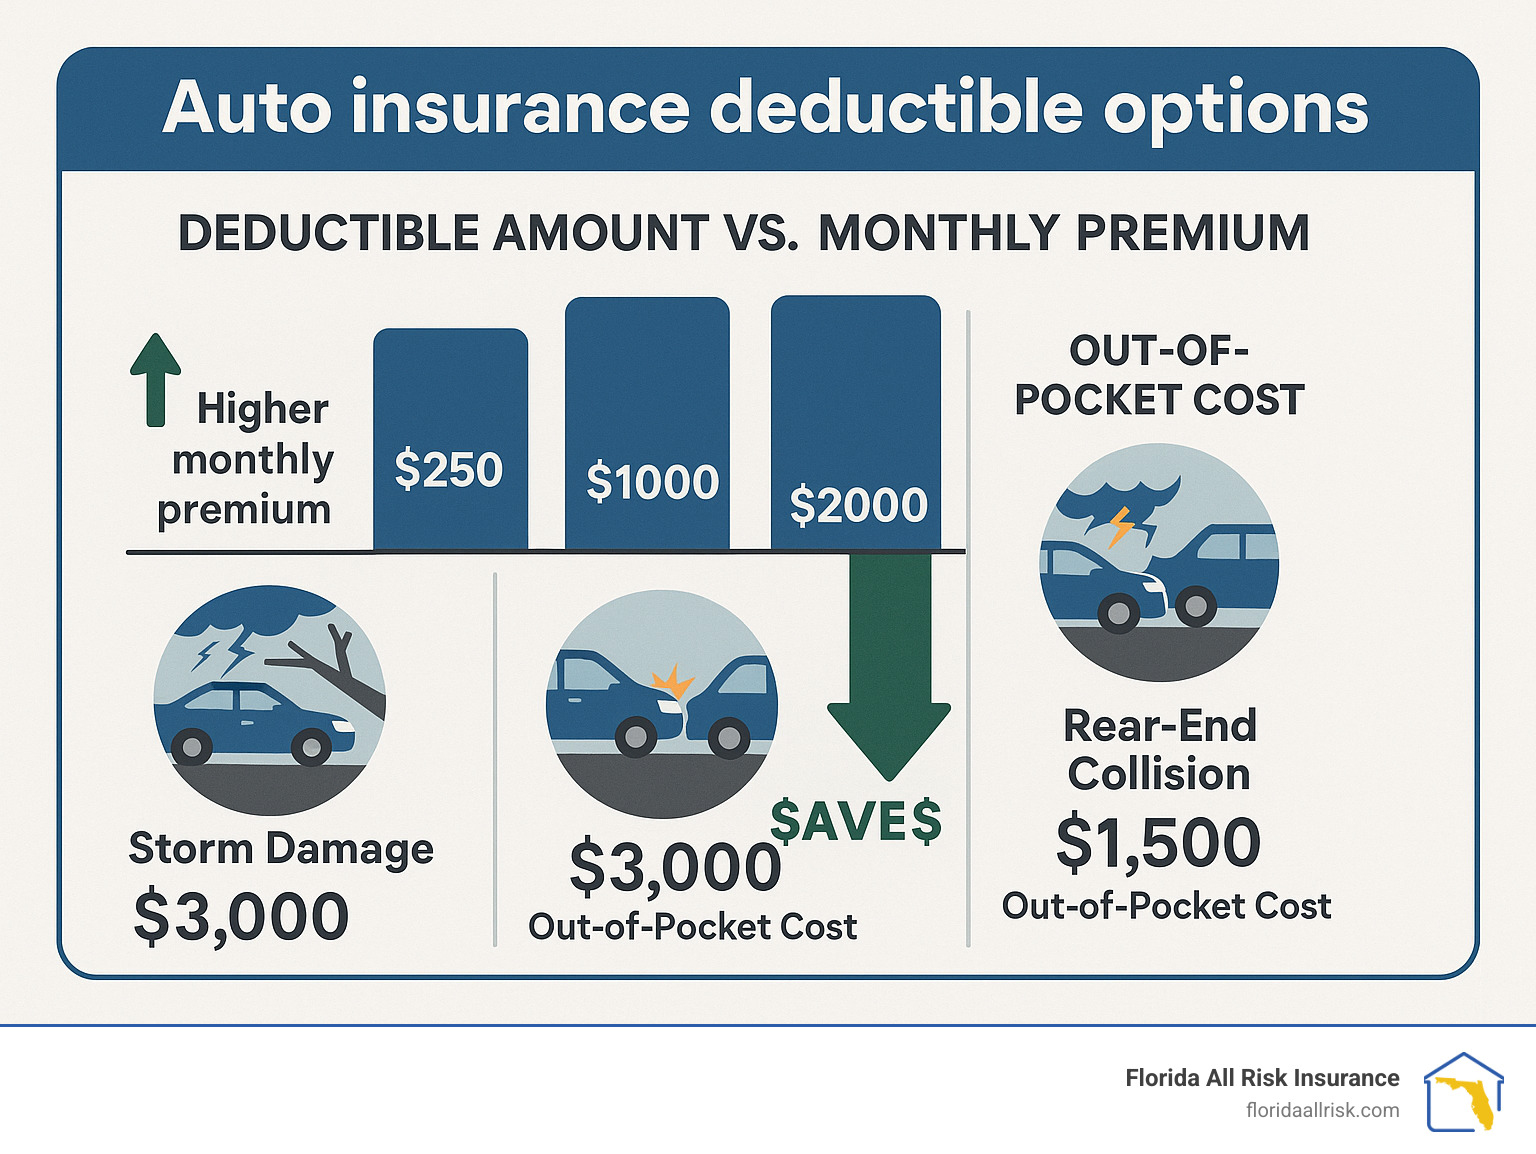
Certified auto repair insurance, often formally known as Mechanical Breakdown Insurance (MBI) or a vehicle service contract, provides financial protection against the high costs of mechanical and electrical failures. Unlike standard auto insurance, which covers accident-related damage, this coverage ensures that repairs are performed by certified technicians using approved parts, specifically targeting non-accident malfunctions.
As we navigate 2026, the landscape of automotive technology has shifted significantly. With the ubiquity of advanced driver-assistance systems (ADAS), high-capacity electric vehicle (EV) batteries, and complex software-defined vehicle architectures, the "certified" aspect of repair insurance has become more critical than ever. Owners can no longer rely on generalist mechanics for specialized repairs; insurance that mandates and pays for certified expertise is now a pillar of responsible vehicle ownership.
Understanding the "Certified" Distinction
In the context of auto repair insurance, the term "certified" carries two distinct but related meanings. Understanding these is essential for any vehicle owner looking to secure their investment.
1. The Certified Technician and Facility
First, "certified" refers to the credentials of the person or shop performing the work. In 2026, the standard for certification usually involves ASE (Automotive Service Excellence) badges or, increasingly, OEM (Original Equipment Manufacturer) Certifications. OEM certification means the shop has been vetted by the vehicle’s manufacturer (such as Ford, Tesla, or Toyota) to have the specific tools, training, and diagnostic equipment required to return the vehicle to factory specifications.
Certified auto repair insurance typically mandates that repairs be performed at these qualified facilities to ensure the validity of the warranty and the safety of the vehicle. This is particularly vital for modern sensor calibration and battery thermal management systems that require specialized environments.
2. The "Certified Auto Repair" Network
Second, there is a specific nationwide brand and network known as Certified Auto Repair (CAR). This is a program supported by major parts distributors (like O'Reilly Auto Parts) that provides a standardized nationwide warranty. When a consumer buys "Certified Auto Repair Insurance" or a protection plan through one of these shops, they are gaining access to a network of thousands of independent repair centers that honor each other's work and warranties across North America.
Mechanical Breakdown Insurance vs. Vehicle Service Contracts
To fully explain certified auto repair insurance, one must distinguish between the two primary legal structures used to provide this coverage. While they offer similar benefits, their regulation and acquisition methods differ.
Mechanical Breakdown Insurance (MBI)
MBI is a true insurance product, regulated by state insurance commissions. In 2026, it is most commonly offered by major carriers (such as Geico, Progressive, or specialized niche insurers) as an add-on to a standard policy.
- Eligibility: Usually restricted to newer vehicles (e.g., less than 15,000 miles and under 15 months old).
- Regulation: Subject to strict state filing requirements regarding rates and forms.
- Payment: Often paid as a small monthly premium added to your existing auto insurance bill.
Vehicle Service Contracts (VSC)
Often colloquially called "extended warranties," VSCs are not technically insurance but rather service agreements. They are the most common form of "certified repair" protection found at dealerships or through third-party providers like Endurance or CarShield.
- Eligibility: Available for a wider range of vehicles, including older models and high-mileage cars.
- Regulation: Governed by different consumer protection laws than insurance, though many states now require these contracts to be "clipt" (backed by an insurance company).
- Payment: Typically paid as a lump sum upfront or through a dedicated financing plan.
Core Coverage Components in 2026
Modern certified repair insurance is designed to address the specific failure points of 2026-era vehicles. Coverage levels are generally split into three tiers:
Powertrain Coverage
This is the most basic level of protection. It covers the "internally lubricated parts" of the engine, transmission, and drive axle. For electric vehicles, this tier has evolved to include the electric drive motors and the primary reduction gearboxes. While it is the most affordable option, it does not cover the high-tech components that are most likely to fail in newer cars.
Stated Component Coverage
This mid-tier plan lists every specific part that is covered. If a part is not on the list, it is not covered. This typically includes the cooling system, fuel system, steering, and basic air conditioning components. In 2026, these plans often include specific riders for infotainment systems and dashboard displays, which have become high-failure items.
Exclusionary Coverage (Bumper-to-Bumper)
This is the gold standard of certified auto repair insurance. Instead of listing what is covered, it lists only what is not covered (typically maintenance items like tires, brake pads, and windshield wipers). If a mechanical or electrical component fails and it isn’t on the exclusion list, the insurance pays for the repair. This is the only recommended level for vehicles equipped with comprehensive ADAS suites or complex luxury features.
Comparing Certified Auto Repair Insurance Options
The following table outlines the key differences between the primary types of repair protection available in 2026.
| Feature | Mechanical Breakdown Insurance (MBI) | Vehicle Service Contract (VSC) | Manufacturer Warranty |
|---|---|---|---|
| Provider | Standard Insurance Companies | Dealerships/Third Parties | Vehicle Manufacturer |
| Cost Structure | Monthly Premium | Upfront or Financed | Included in Sale Price |
| Repair Location | Any Certified Shop | Specified Network/Certified | Authorized Dealerships |
| Duration | Renewable Annually | Set Term (e.g., 5yr/100k) | Set Term (e.g., 3yr/36k) |
| Best For | New vehicle owners | Used/High-mileage vehicles | Original buyers of new cars |
| Parts Used | OEM or Certified Equivalent | OEM or Certified Equivalent | Strictly OEM |
The Impact of Modern Vehicle Technology on Claims
In 2026, the process of "explaining" repair insurance must account for the astronomical rise in diagnostic and calibration costs. A minor fender bender or a simple sensor failure now often requires a pre-scan and post-scan of the vehicle’s computer systems.
Certified repair insurance is unique because it specifically covers these "soft" costs. If a blind-spot monitor fails, the insurance doesn't just pay for the $400 sensor; it pays for the three hours of labor required to calibrate that sensor using specialized targets and software. Without a certified repair policy, these calibration fees—which can exceed $1,000—are often out-of-pocket expenses for the consumer.
How the Claim Process Works
When a mechanical failure occurs, following the correct procedure is vital to ensure the claim is not denied. Most certified repair insurance policies follow a strict four-step process:
- Protect the Vehicle from Further Damage: As soon as a warning light appears or a failure is felt, you must stop operating the vehicle. Continuing to drive a vehicle with a known issue (like overheating) can result in a claim denial for "consequential damage."
- Take the Vehicle to a Certified Facility: Ensure the shop accepts your specific insurance or service contract. Provide them with your policy number before they begin work.
- The Diagnosis and Authorization Phase: The shop will perform a diagnostic test. Crucially, you should not authorize the repair until the insurance company has approved the claim. The insurance company may send an inspector to the shop to verify the failure.
- Payment and Deductible: Once the repair is authorized and completed, the insurance company pays the shop directly (in most cases). You are responsible only for your agreed-upon deductible, which in 2026 typically ranges from $100 to $500.
Common Exclusions and Limitations
No insurance policy covers everything. Even the most comprehensive "certified" plans have limitations that owners must understand to avoid surprises at the repair counter.
- Pre-existing Conditions: No policy will cover a problem that existed before you purchased the coverage. Most plans have a 30-day and 1,000-mile "waiting period" to prevent fraud.
- Negligence and Maintenance: If a component fails because you failed to change the oil or coolant according to the manufacturer’s schedule, the claim will be denied. You must keep all maintenance records.
- Non-Mechanical Items: Interior upholstery, paint, glass, and body panels are almost never covered by repair insurance; these fall under standard collision/comprehensive insurance or the owner's responsibility.
- Modified Vehicles: Aftermarket performance modifications (like "chips" or lift kits) can void your certified repair coverage entirely.
Evaluating Costs: Is It Worth It in 2026?
The cost of certified auto repair insurance varies based on the vehicle's age, make, and the level of coverage chosen. On average, a comprehensive plan for a mid-sized SUV in 2026 costs between $450 and $900 per year.
To determine if the cost is justified, consider the "Single Failure Rule." In 2026, the average cost to replace an EV battery module or a sophisticated infotainment head unit often exceeds $3,000. If the insurance premium over five years is $3,500, and it covers just one major failure, the policy has nearly paid for itself while providing five years of peace of mind.
For owners of vehicles out of their factory warranty, especially those with high-tech features or electric drivetrains, this insurance is increasingly viewed as a necessary line item in the household budget rather than an optional luxury.
FAQ
Does certified auto repair insurance cover routine maintenance like oil changes?
No. Certified auto repair insurance is designed for unexpected mechanical failures, not predictable maintenance. However, some high-end vehicle service contracts in 2026 offer "maintenance wraps" as an optional add-on, which may cover oil changes, tire rotations, and brake pads for an additional fee.
Can I go to any mechanic with this insurance?
It depends on the policy, but most require the shop to be ASE Certified or a licensed repair facility. To ensure the highest level of coverage and to guarantee that the insurer pays the shop's labor rates, it is always best to choose a shop that is part of the insurer’s preferred network or holds OEM certifications for your specific brand.
How does "Certified Auto Repair" insurance handle software updates?
In 2026, many mechanical issues are actually software bugs. If a software glitch causes a physical component (like a transmission or a battery controller) to malfunction, most exclusionary policies will cover the "re-flashing" or updating of the vehicle's computer. However, standard updates that merely add new features are not covered.
Is the insurance transferable if I sell my car?
Most vehicle service contracts and some MBI policies are transferable to the next private owner for a small administrative fee (usually around $50). This can significantly increase the resale value of your vehicle, as the new buyer gains the same peace of mind and protection.
What is the difference between a deductible and a "disappearing deductible"?
A standard deductible is the amount you pay per repair visit. A "disappearing deductible" is a feature where the deductible is waived (reduced to $0) if you return to the specific dealership or shop where you purchased the policy for all your repairs.
Practical Recommendation
If you are purchasing a vehicle in 2026 that is no longer covered by the manufacturer's original warranty, or if you plan to keep a new vehicle for more than three years, secure a Mechanical Breakdown Insurance (MBI) policy through your primary auto insurer first. MBI typically offers the lowest premiums and the most transparent regulation. If your vehicle is too old to qualify for MBI, seek an Exclusionary Vehicle Service Contract from a reputable provider that allows repairs at OEM-certified facilities. Always verify that the policy covers "diagnostic fees" and "fluid disposal," as these common charges can otherwise lead to unexpected out-of-pocket costs during a claim.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
