
Yes, you need a beneficiary for a life insurance policy even when you are single. Without a named beneficiary, the death benefit payout will bypass your intended recipients and go directly to your estate, where it faces probate court delays, legal fees, and potential taxation before distribution under state intestacy laws.
Navigating life insurance policies while single often leads to a common misconception: because you do not have a spouse or children depending on your daily income, the intricacies of beneficiary designations matter less. In reality, purchasing or maintaining a life insurance policy as a single adult involves strategic planning. Choosing whom to name, understanding what happens in the absence of a designated individual, and recognizing the difference between primary and contingent designations remain critical steps. This guide examines why designation choices matter for single policyholders, how policies function without them, and the alternatives available to secure your financial legacy.
Understanding the Role of a Beneficiary in Life Insurance
A life insurance beneficiary is the individual, institution, trustee, or entity legally designated to receive the death benefit payout when the insured person passes away. This designation acts as a binding legal contract between the policyholder and the insurance company. When you purchase a policy, selecting a beneficiary dictates precisely who receives the financial proceeds, bypassing the traditional will-making process for those specific funds.
For single individuals, the definition of a beneficiary extends far beyond traditional family units. While married policyholders frequently name their spouses, single policyholders must evaluate their broader financial ecosystem. This includes aging parents, siblings, business partners, charitable organizations, or trusts established for specific purposes.
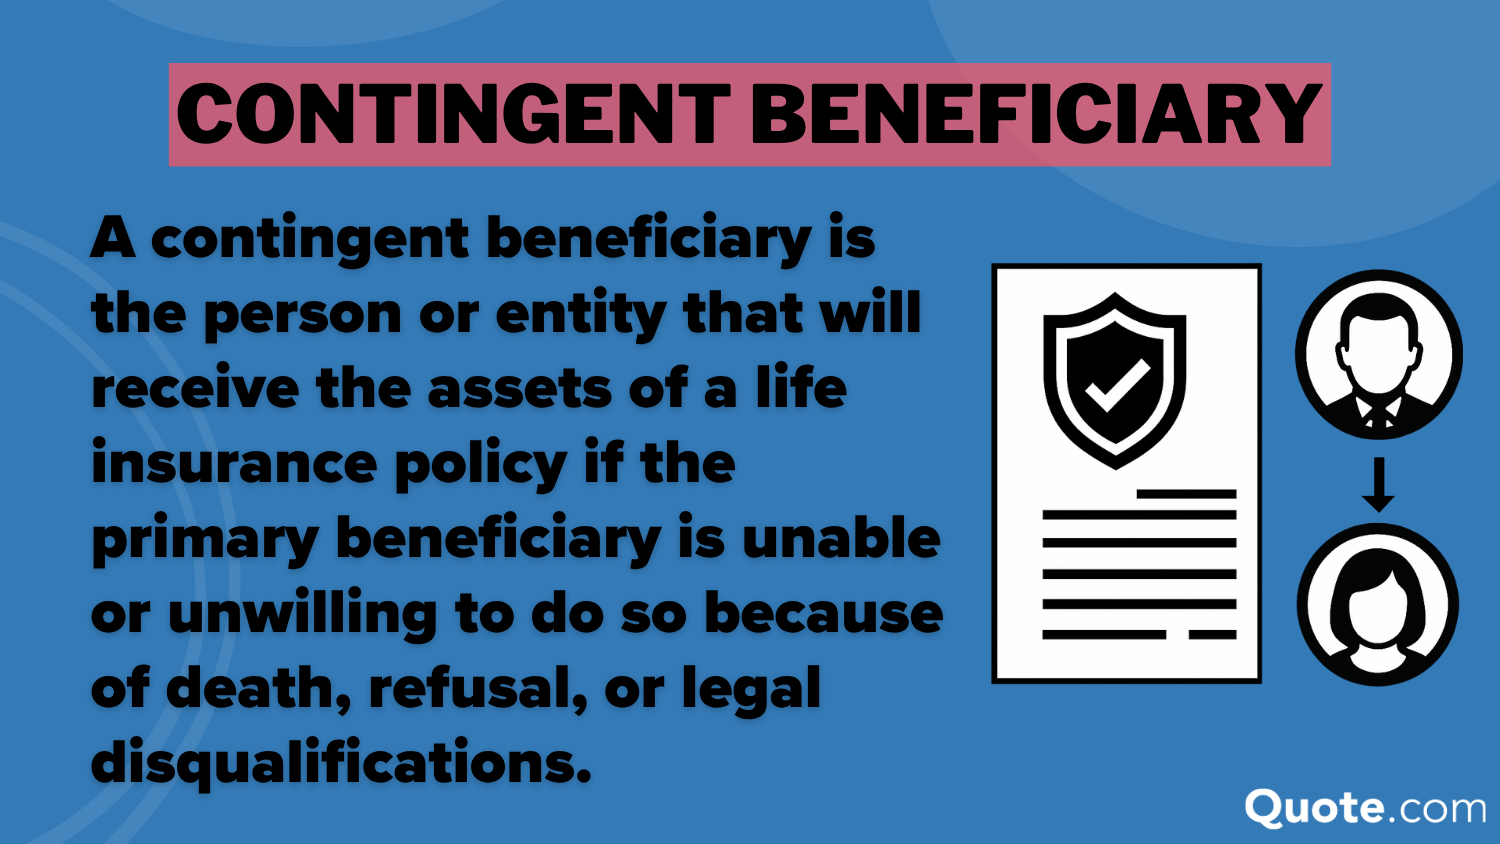
Designations are split into two primary categories: primary and contingent. The primary beneficiary is first in line to receive the death benefit. If the primary beneficiary predeceases the policyholder or disclaims the payout, the contingent (or secondary) beneficiary steps in to claim the funds. Failing to name either leaves the policy vulnerable to legal complications.
What Happens If You Do Not Name a Beneficiary?
Leaving a life insurance policy without a named beneficiary—or outliving all named beneficiaries without updating the policy—triggers a default legal process. The insurance proceeds are paid directly to your estate. Once funds enter your estate, they become subject to several administrative hurdles that can diminish the value of your policy.
Probate Court Delays
When funds are paid to an estate rather than a named individual, the distribution of the money must go through probate. Probate is the legal process through which a court validates a will, settles debts, and distributes remaining assets. This process can take anywhere from several months to over a year, leaving your intended heirs or final expenses unfunded during a critical window.
Legal Fees and Administrative Costs
Estate administration is not free. Executor fees, court costs, and legal counsel fees accumulate during probate. A portion of your life insurance payout will likely be consumed by these administrative expenses before any remaining balance reaches your relatives.
Exposure to Creditors
When a life insurance payout goes directly to a named beneficiary, it is generally protected from the deceased person’s creditors. However, once the funds are funneled into an estate, they become part of the general pool of assets. Creditors can make claims against the estate to settle your remaining debts, meaning your life insurance money could be used to pay off credit cards or medical bills rather than supporting your loved ones.
State Intestacy Laws
If you die without a valid will and without a named beneficiary, state intestacy laws dictate who receives your estate. These rigid statutes follow a strict hierarchy—typically parents, siblings, or more distant relatives. The state's formula may distribute your assets to family members you are estranged from or prefer not to support, completely overriding your personal wishes.
Common Beneficiary Options for Single Individuals
Being single provides immense flexibility in choosing who benefits from your financial safety net. Without spousal obligations, you can tailor your policy to reflect your personal values, familial responsibilities, and long-term goals.
| Beneficiary Type | Description | Best Suited For | Key Consideration |
|---|---|---|---|
| Parents or Siblings | Immediate family members who may need financial support or help covering final expenses. | Supporting aging parents or helping siblings with educational or housing costs. | Requires updating if family dynamics or support needs change. |
| Trust | A legal entity that holds and manages assets for a designated purpose or person. | Maintaining control over payout distribution, especially for younger heirs or pets. | Involves legal setup and ongoing maintenance costs. |
| Charitable Organization | A registered non-profit, educational institution, or religious group. | Leaving a philanthropic legacy to causes you championed during your lifetime. | Must include the organization's exact legal name and tax ID. |
| Estate | The legal entity representing all your possessions and debts upon death. | Directing funds to pay off complex final debts or fund a complex will. | Triggers probate, court fees, and creditor exposure. |
Naming Family Members
Many single adults choose to name their parents or siblings as primary beneficiaries. If your parents rely on you for partial financial support, or if you want to ensure your siblings have a financial cushion, this is a straightforward choice. You can also split the payout percentages among multiple family members, such as dividing the benefit equally among three siblings.
Establishing a Trust
If you want strict control over how and when the money is distributed, you can name a trust as your beneficiary. For example, if you want to ensure your nieces and nephews receive funds for college only after turning 21, a trust dictates those terms. Trusts are also frequently used by single pet owners to fund pet trusts, ensuring dedicated care for companion animals after the owner's death.
Supporting Charitable Causes
Single policyholders frequently utilize life insurance to support philanthropic initiatives. Designating a registered charity as a beneficiary allows you to make a substantial financial impact that might not be possible through standard savings alone. When doing so, coordinate closely with the charity to ensure you have their precise legal name and tax identification number.
Key Factors Single Adults Should Consider
When structuring a life insurance policy as a single person, evaluating your financial obligations and future trajectory ensures your policy serves its intended purpose.
Final Expense Coverage
Even without dependents, a single person incurs final expenses upon death, including funeral costs, medical bills, burial or cremation services, and potential legal fees. Naming a trusted friend or family member as a beneficiary—with the explicit understanding that the funds will cover these expenses—prevents these financial burdens from falling on grieving relatives.
Outstanding Debt Liabilities
While unsecured debts like credit cards typically do not pass on to family members, they must be paid out of your estate. If you co-signed a private student loan, a car loan, or a mortgage with a parent or friend, that co-signer becomes legally responsible for the remaining balance after your death. A life insurance policy with a designated beneficiary can provide the liquidity needed to clear these debts entirely, protecting your co-signers from financial distress.
Future Life Changes
Life insurance is not a static financial product. Being single today does not mean your status will remain unchanged over the 10-, 20-, or 30-year lifespan of a term life policy. Review your beneficiary designations following major life milestones, such as marriage, the birth of children, purchasing property, or experiencing a falling out with a previously named beneficiary.
How to Update or Designate Your Beneficiaries
Updating or establishing a beneficiary on an existing life insurance policy is a straightforward administrative process, but it requires adherence to formal procedures. Insurance companies do not accept verbal updates or informal notes written in a personal diary; everything must be documented through official channels.
- Contact Your Insurance Provider: Reach out to your insurance company’s customer service department or log into your online policy portal to request a Change of Beneficiary form.
- Gather Accurate Information: Collect full legal names, dates of birth, Social Security numbers (or tax ID numbers for charities/trusts), current physical addresses, and telephone numbers for all primary and contingent beneficiaries.
- Specify Percentages: If you are naming multiple beneficiaries, clearly define the percentage allocation for each. Ensure the total equals exactly 100%.
- Complete and Sign the Form: Fill out the document accurately. Many insurers require the signature to be witnessed or notarized to prevent fraud.
- Submit and Confirm Receipt: Mail, fax, or upload the completed form back to the insurer. Request a written confirmation or endorsement from the insurance company verifying that the update has been officially recorded in your policy file.
Frequently Asked Questions
Can I name a friend as my life insurance beneficiary if I am single?
Yes, you can legally name a friend, partner, or any individual with whom you have an insurable interest or personal relationship as your beneficiary. Insurance companies do not require beneficiaries to be blood relatives. However, keeping contact information current is vital, as the insurer will look for the named individual directly upon your passing.
What happens if my sole beneficiary dies before I do?
If your primary beneficiary passes away before you and you never named a contingent beneficiary, your policy effectively has no valid beneficiary at the time of your death. In this scenario, the death benefit defaults to your estate, subjecting the funds to probate court, potential creditor claims, and state distribution laws. Regularly auditing your policy prevents this scenario.
Do I need life insurance at all if I am single and have no dependents?
Many single individuals purchase life insurance to cover final expenses, pay off shared debts, lock in lower premium rates while young and healthy, or support charitable organizations. If you have no debts and your savings comfortably cover potential end-of-life costs, you may not need a policy. However, if you have co-signed loans or want to provide a financial cushion for aging parents, a policy remains useful.
Can I change my beneficiary designations at any time?
As long as your policy is an irrevocable designation—meaning you hold standard ownership rights—you can change your beneficiaries as often as you like during your lifetime. You simply need to complete the insurer's change-of-beneficiary paperwork. Irrevocable beneficiaries, which are less common, require the current beneficiary's explicit consent to make changes.
Are life insurance payouts to a beneficiary taxable?
Generally, life insurance death benefits paid to a designated individual beneficiary are received completely income tax-free. However, if the payout goes to your estate because you failed to name a beneficiary, the funds may become subject to state inheritance taxes or federal estate taxes depending on the total value of your estate.
Conclusion and Next Actions
Being single does not eliminate the need for a designated life insurance beneficiary; rather, it places the responsibility entirely on you to decide where your financial legacy goes. Leaving a policy without a named beneficiary exposes the payout to probate delays, legal fees, and state-dictated distribution that may conflict with your wishes.
To secure your policy, review your current documentation today. Verify whether a primary and contingent beneficiary are correctly listed, ensure their personal details are up to date, and contact your insurance provider immediately if changes are required.
Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
