
Securing the best auto insurance in the 74116 ZIP code of Tulsa, Oklahoma, requires balancing state-mandated liability minimums with the specific risk profile of the North Tulsa area. By comparing providers based on local claims processing, premium transparency, and coverage flexibility, drivers can effectively protect their assets while meeting Oklahoma’s financial responsibility laws.
Understanding Oklahoma Auto Insurance Requirements
In Oklahoma, every driver is legally required to maintain a minimum amount of financial responsibility for the operation of a motor vehicle. As of 2026, the state mandates "25/50/25" liability coverage. This means your policy must provide at least $25,000 for bodily injury per person, $50,000 for total bodily injury per accident, and $25,000 for property damage per accident.
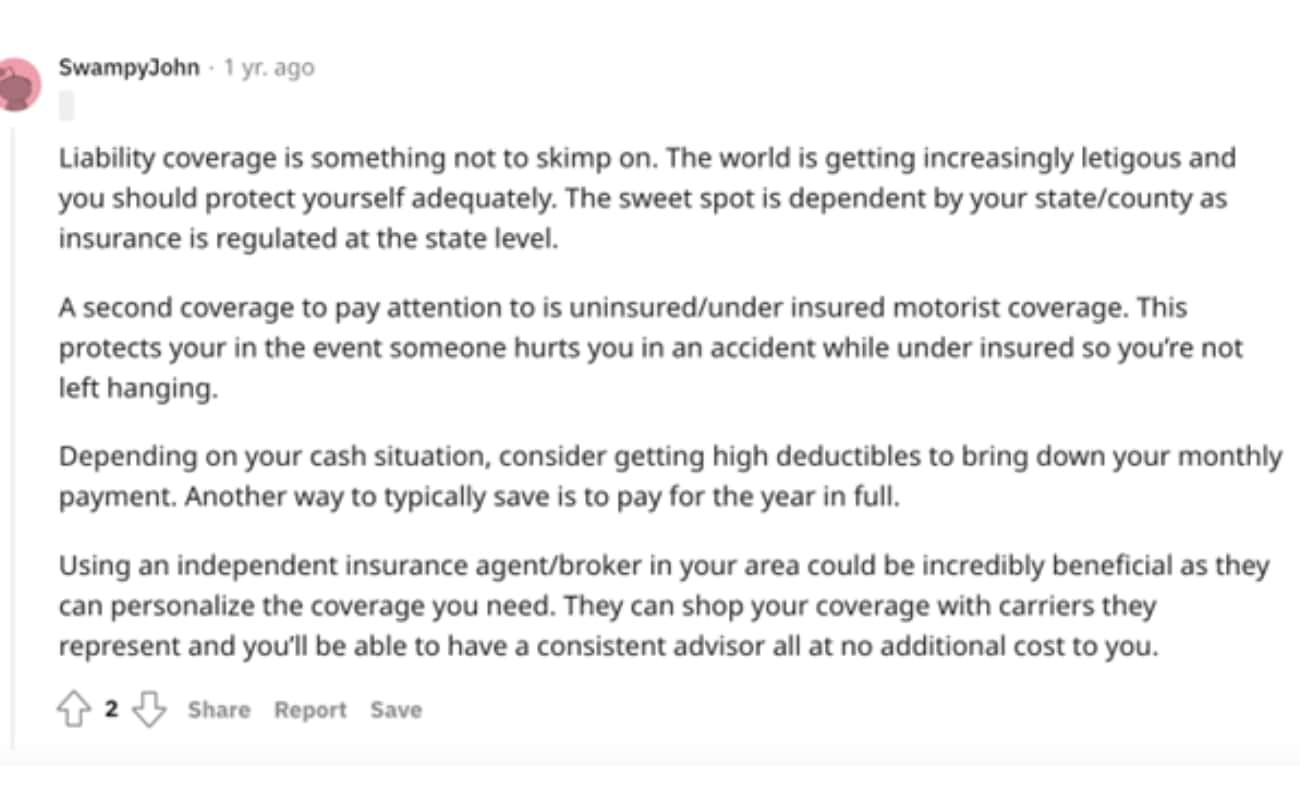
While these limits satisfy the state, they are rarely sufficient to protect a driver's personal assets in the event of a significant collision. Because the cost of vehicle repairs and medical expenses has risen, many insurance experts recommend carrying higher limits—often 100/300/100—to ensure that if you are found at fault, your personal savings and property remain shielded from legal judgments.
Factors Influencing Insurance Rates in 74116
Your ZIP code is a significant variable in the underwriting process. Insurance companies analyze data specific to the 74116 area to determine the likelihood of claims. This includes factors such as:
- Traffic Density and Road Infrastructure: The proximity of 74116 to major transit corridors in Tulsa influences accident frequency. Higher traffic volumes often correlate with an increased risk of fender-benders.
- Theft and Vandalism Rates: Insurers utilize crime statistics for specific ZIP codes to set premiums for Comprehensive coverage. If a neighborhood has a higher incidence of auto theft, rates for Comprehensive, which covers non-collision events, will reflect that elevated risk.
- Weather Patterns: Oklahoma is prone to severe weather, including hail, high winds, and tornadoes. In 74116, the prevalence of these events makes Comprehensive coverage a vital component of any robust insurance portfolio, as it protects against weather-related vehicle damage.
Types of Coverage to Consider
Beyond the state-mandated liability, there are several "optional" coverages that function as essential safeguards in the 74116 area:
- Uninsured/Underinsured Motorist (UM/UIM): Given the number of drivers who may be operating vehicles without proper insurance, UM/UIM coverage is critical. It pays for your medical bills and property damage if the at-fault driver has no insurance or insufficient limits to cover your damages.
- Collision Coverage: This pays for repairs to your vehicle regardless of who caused the accident. If you are financing or leasing your vehicle, your lender will almost certainly require this.
- Comprehensive Coverage: As noted previously, this covers events outside of your control, including theft, fire, vandalism, and damage from falling objects or storms.
- Medical Payments (MedPay): This covers medical expenses for you and your passengers regardless of fault, providing immediate relief for out-of-pocket costs following an accident.
Comparing Insurance Providers
When evaluating the "best" company, you should look beyond just the monthly premium. The best insurer for a Tulsa resident is one that offers a balance of price, financial stability, and responsive service.
| Feature | Importance | What to Look For |
|---|---|---|
| Financial Strength | Critical | AM Best or S&P ratings (A or higher) |
| Claim Satisfaction | High | Positive consumer complaints record in Oklahoma |
| Discount Availability | Moderate | Multi-policy, defensive driving, and telematics |
| Mobile Integration | Moderate | Real-time app access for claims and ID cards |
Strategies to Lower Your Premiums
Reducing your insurance costs without sacrificing necessary coverage is a common goal. In Tulsa, consider these evidence-based strategies:
- Bundling Policies: Most major insurers offer a significant discount if you purchase both your auto and homeowners (or renters) insurance from the same carrier.
- Telematics Programs: Many companies now offer "Usage-Based Insurance" (UBI). By installing a mobile app or a small device that monitors your driving habits—such as hard braking, speed, and time of day—you may earn a discount for safe driving behaviors.
- Increased Deductibles: Choosing a higher deductible (e.g., $1,000 instead of $500) lowers your monthly premium. Only do this if you have the savings available to cover that deductible in the event of an accident.
- Maintaining a Clean Record: While this is a long-term strategy, the absence of tickets and moving violations remains the single most effective way to keep premiums low over several years.
The Role of Independent Agents vs. Captive Agents
In Tulsa, you will find both independent insurance agents and "captive" agents. A captive agent works for one specific company and can only sell products from that carrier. An independent agent, by contrast, represents multiple insurance companies.
For many 74116 residents, an independent agent can be an advantage because they can perform a comparative analysis across several carriers, effectively doing the "shopping" for you. They can highlight which companies provide the best coverage for Oklahoma’s specific risk factors, such as the aforementioned hail risk.
Common Mistakes to Avoid
When shopping for auto insurance, residents often fall into common traps that lead to inadequate protection:
- Focusing Only on Premiums: Choosing the cheapest policy often means selecting the lowest liability limits or failing to include necessary coverage like UIM. Always compare the coverage "buckets" across quotes, not just the final dollar amount.
- Misrepresenting Information: Providing inaccurate information about your driving record, vehicle usage, or where the car is garaged is considered insurance fraud and can lead to policy cancellation or denial of claims.
- Ignoring Policy Updates: Life changes, such as moving to a different neighborhood, getting married, or changing your commute, should be communicated to your insurer. These changes can often result in lower premiums.
Frequently Asked Questions
Does my credit score affect my auto insurance rate in Oklahoma? Yes. In Oklahoma, insurers are permitted to use credit-based insurance scores as a factor in determining premiums. They correlate statistical patterns in credit data with the likelihood of future claims. Improving your credit score over time is one way to eventually qualify for better rates.
How does the 74116 ZIP code specifically impact my risk? Insurers look at localized data. This includes high-traffic volume on nearby arterial roads, the frequency of weather-related incidents in the Tulsa metropolitan area, and regional theft patterns. These variables are aggregated to help the insurer calculate the risk of insuring a vehicle in that specific quadrant of the city.
If I have an old car, do I still need full coverage? Not necessarily. If your vehicle’s market value is low—roughly less than ten times the annual cost of your premium for collision and comprehensive coverage—it may be more economical to drop those specific coverages and carry only liability. However, you must be prepared to pay for vehicle repairs out-of-pocket if you are at fault.
Are there discounts for young drivers in Tulsa? Yes, most insurers offer "Good Student" discounts for drivers under 25 who maintain a certain grade point average (usually a B average or higher). Additionally, completing an accredited defensive driving course can often lead to a reduction in premiums for drivers of all ages.
How do I verify if an insurance company is licensed in Oklahoma? You can verify the status of any insurance provider by consulting the Oklahoma Insurance Department’s online portal. Ensure the company is authorized to conduct business in the state, which ensures you have legal recourse through the state regulator if you ever have a dispute regarding a claim.
Next Steps for Tulsa Residents
To find the best insurance for your specific needs, begin by gathering your vehicle’s VIN, your current policy declarations page, and your driving history. Request quotes from at least three different carriers—including both large national brands and regional Oklahoma-based providers. Review the declarations page of each quote carefully to ensure the liability limits match your financial comfort level. If you are unsure about the nuances of your coverage, consult with a licensed local insurance agent who understands the specific environmental and legal landscape of the Tulsa 74116 area.

Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
