
The best senior life insurance plan depends on your financial goals, health status, and budget. For debt protection, Term Life is often ideal. If you require permanent coverage with cash value, Whole Life is better. For those with health concerns seeking to cover only funeral costs, Final Expense or Guaranteed Issue policies offer the most accessible path.
Navigating the insurance market as a senior in 2026 requires a clear understanding of how age affects premiums and how different policy structures serve specific end-of-life goals. Unlike insurance for younger adults, which focuses largely on income replacement for dependents, senior life insurance is often tailored toward estate planning, debt clearance, or "final expenses"—the costs associated with funerals, burials, and medical bills.
Assessing Your Primary Need for Coverage
Before comparing specific plans, you must identify why you are seeking insurance at this stage of life. The "best" plan is the one that solves your specific financial vulnerability without overextending your monthly budget.
Legacy and Heritage Planning
If your goal is to leave a specific inheritance to children or grandchildren, or to provide a donation to a charity, you generally require a permanent policy. Term insurance is risky for this purpose because if you outlive the term, the "legacy" disappears. Whole Life or Universal Life policies ensure that as long as premiums are paid, a tax-free death benefit will be delivered to your beneficiaries.
Debt and Mortgage Protection
Seniors who still carry a mortgage or significant personal debt often choose Term Life insurance. Because these debts have a projected "end date," it makes little sense to pay the high premiums of a permanent policy. A 10-year or 15-year term policy can cover the remaining balance of a mortgage, ensuring that a surviving spouse is not forced to sell the family home.
Final Expenses and Burial Costs
As of 2026, the average cost of a traditional funeral and burial has risen significantly due to inflationary pressures on the death care industry. Many seniors find that they don't need $500,000 in coverage, but rather $10,000 to $25,000 to prevent their children from inheriting funeral debt. Final Expense insurance (often called "Burial Insurance") is a specialized form of whole life insurance with lower face values and more lenient underwriting.
Comparing Senior Life Insurance Plan Types
To determine which plan is best for you, it is essential to understand the mechanics of the three primary categories available to seniors today.
1. Term Life Insurance for Seniors
Term insurance provides coverage for a specific period, typically 10, 15, or 20 years. In 2026, many carriers allow new term policies for applicants up to age 75, though the available terms shorten as you age.
- The Pros: It is significantly cheaper than permanent insurance for the same amount of coverage. It is straightforward and does not involve complex investment components.
- The Cons: It accumulates no cash value. Once the term ends, you have no coverage. Renewing at the end of a term is often prohibitively expensive because rates are based on your attained age.
- Suitability: Best for seniors in relatively good health who have a specific timeframe for their financial obligations.
2. Whole Life Insurance
Whole life insurance is a type of permanent coverage that stays in effect for your entire life, provided you pay the premiums. It also includes a "cash value" component that grows over time at a guaranteed rate.
- The Pros: Premiums are fixed; they will never increase, regardless of your age or health changes. The death benefit is guaranteed. You can potentially borrow against the cash value for emergencies.
- The Cons: It is the most expensive type of life insurance. For a senior starting a policy at 65 or 70, the premiums can be a heavy burden on a fixed income.
- Suitability: Best for those who want absolute certainty and can afford the higher premiums to ensure a payout regardless of when they pass away.
3. Final Expense and Guaranteed Issue Plans
These are "Simplified Issue" or "Guaranteed Issue" whole life policies. They are designed specifically for the senior market.
- Simplified Issue: Requires you to answer a few health questions but does not require a medical exam. If you are relatively healthy but don't want a nurse coming to your house for a blood draw, this is an excellent middle ground.
- Guaranteed Issue: No health questions and no medical exam. You cannot be turned down. However, these policies almost always have a "graded death benefit" for the first two years. If you pass away from natural causes during this waiting period, your beneficiaries only receive the premiums paid plus a small amount of interest.
- Suitability: Best for seniors with chronic health conditions (like diabetes, heart disease, or past strokes) who need a small policy to cover funeral costs.
Key Factors Influencing Your Choice in 2026
The insurance landscape in 2026 is influenced by increased life expectancy and more sophisticated medical data. Here are the technical factors you must weigh.
Underwriting and Health Classes
Insurance companies categorize you into "risk classes" such as Preferred Plus, Preferred, Standard, and Substandard. As a senior, even minor health issues like well-controlled high blood pressure can move you from "Preferred" to "Standard." In 2026, many companies use "Accelerated Underwriting," which uses algorithms to scan your electronic health records and prescription history, often providing an approval in minutes without a physical exam.
The Impact of Inflation on Coverage Amounts
When calculating how much insurance you need, consider that $20,000 today will not have the same purchasing power in 15 years. If you are buying a policy for final expenses, it is often wise to build in a "buffer" to account for the rising costs of services. According to the National Association of Insurance Commissioners (NAIC), consumers should regularly review their coverage to ensure it still meets their original goals.
Riders and Living Benefits
Modern policies in 2026 frequently include "living benefits." These are riders that allow you to access a portion of your death benefit while you are still alive if you are diagnosed with a terminal or chronic illness. For seniors, an Accelerated Death Benefit Rider can be a lifeline, helping to pay for long-term care or hospice services, effectively reducing the financial strain on the family before the policyholder passes.
Comparison Table: Senior Life Insurance Options
The following table summarizes the key differences between the most common plans available to seniors.
| Plan Type | Typical Age Limit | Medical Exam? | Coverage Amount | Premium Structure | Best Use Case |
|---|---|---|---|---|---|
| Term Life | Up to 75-80 | Often Required | $50k - $1M+ | Fixed for the Term | Mortgages, temporary debt |
| Whole Life | Up to 85+ | Usually Required | $25k - $1M+ | Fixed for Life | Legacy, estate taxes |
| Simplified Issue | Up to 85 | Health Questions | $5k - $50k | Fixed for Life | Fast approval, small debts |
| Guaranteed Issue | Up to 80-85 | None | $2k - $25k | Fixed for Life | Poor health, funeral costs |
| Guaranteed UL | Up to 80 | Often Required | $50k - $500k+ | Flexible/Fixed | Permanent at lower cost |
Common Mistakes to Avoid
Choosing the wrong plan can result in wasted premiums or, worse, a denied claim for your beneficiaries.
1. Ignoring the Graded Period in Guaranteed Issue Policies Many seniors buy guaranteed issue plans without realizing that if they pass away in the first 24 months, the full death benefit isn't paid. If you are healthy enough to pass a few medical questions, always opt for a "Level Benefit" policy (Simplified Issue) instead of Guaranteed Issue to ensure immediate full coverage.
2. Over-Insuring and Straining the Budget Lapsing a policy is a major risk for seniors. If you buy a policy with a $200 monthly premium but your Social Security cost-of-living adjustments don't keep up with your other expenses, you might be forced to cancel the policy later. It is better to have a smaller, $10,000 policy that you can definitely afford than a $50,000 policy that you might lose in three years.
3. Waiting Too Long Life insurance costs increase every year you age. Furthermore, a sudden health diagnosis can move you from being eligible for a low-cost term policy to only being eligible for a high-cost guaranteed issue policy. In 2026, the cost of waiting even 12 months can result in a 10% to 15% increase in monthly premiums.
Understanding the Role of the Social Security Death Benefit
It is a common misconception that Social Security provides significant funeral assistance. As of 2026, the Social Security Administration (SSA) continues to provide a one-time lump-sum death payment of only $255, and only to eligible surviving spouses or children. This amount has remained unchanged for decades and is nowhere near sufficient to cover modern end-of-life costs, which underscores the necessity of private life insurance.
Frequently Asked Questions
Can I get life insurance if I am over 80 years old? Yes, but your options are generally limited to Whole Life or Final Expense policies. Most carriers stop issuing new Term Life policies after age 75 or 80. At age 80+, you will likely look at "Guaranteed Issue" plans which do not require medical exams but have lower coverage limits, typically capped at $25,000.
Is Whole Life insurance better than Term for seniors? "Better" depends on the goal. Term is better if you want the highest amount of coverage for the lowest price to cover a temporary risk. Whole Life is better if you want a guaranteed payout regardless of how long you live and want to build a small cash reserve. Most seniors find that a small Whole Life policy for final expenses provides the most peace of mind.
What happens if I outlive my Term Life policy? If you reach the end of the term (e.g., your 15-year policy expires when you are 82), the coverage simply ends. You may have the option to renew it on an annual basis, but the premiums will skyrocket, often becoming five to ten times more expensive. Some policies allow for a "Return of Premium" rider, but these are rare and expensive for seniors to initiate.
Do I have to take a medical exam for senior life insurance? Not necessarily. In 2026, "No-Exam" policies are very common. These use simplified underwriting where the company checks your medical databases and pharmacy records instead of requiring a physical. However, if you are in excellent health, taking a medical exam can often secure you a lower premium because you are proving to the company that you are a low-risk client.
How does tobacco use affect senior insurance rates? Tobacco use—including cigarettes, cigars, and increasingly, vaping—can double or even triple premiums for seniors. Most insurance companies require you to be tobacco-free for at least 12 months to qualify for "Non-Smoker" rates. If you have quit recently, it may be worth waiting until that 12-month mark to apply for a permanent policy.
Final Recommendation for Seniors
To choose the best plan for you in 2026, start by calculating your "must-pay" end-of-life expenses. If you have no major debts and only wish to cover burial costs, a Final Expense (Simplified Issue) policy is the most efficient choice; it offers fixed premiums and a permanent death benefit without the hassle of a medical exam.
However, if you have a surviving spouse who relies on your income or if you have an outstanding mortgage, a 10-year or 15-year Term Life policy provides the necessary "safety net" at a much lower cost than a whole life plan. Always work with an independent agent who represents multiple carriers to compare the underwriting nuances of each company, as one carrier might be much more lenient toward your specific health history than another.
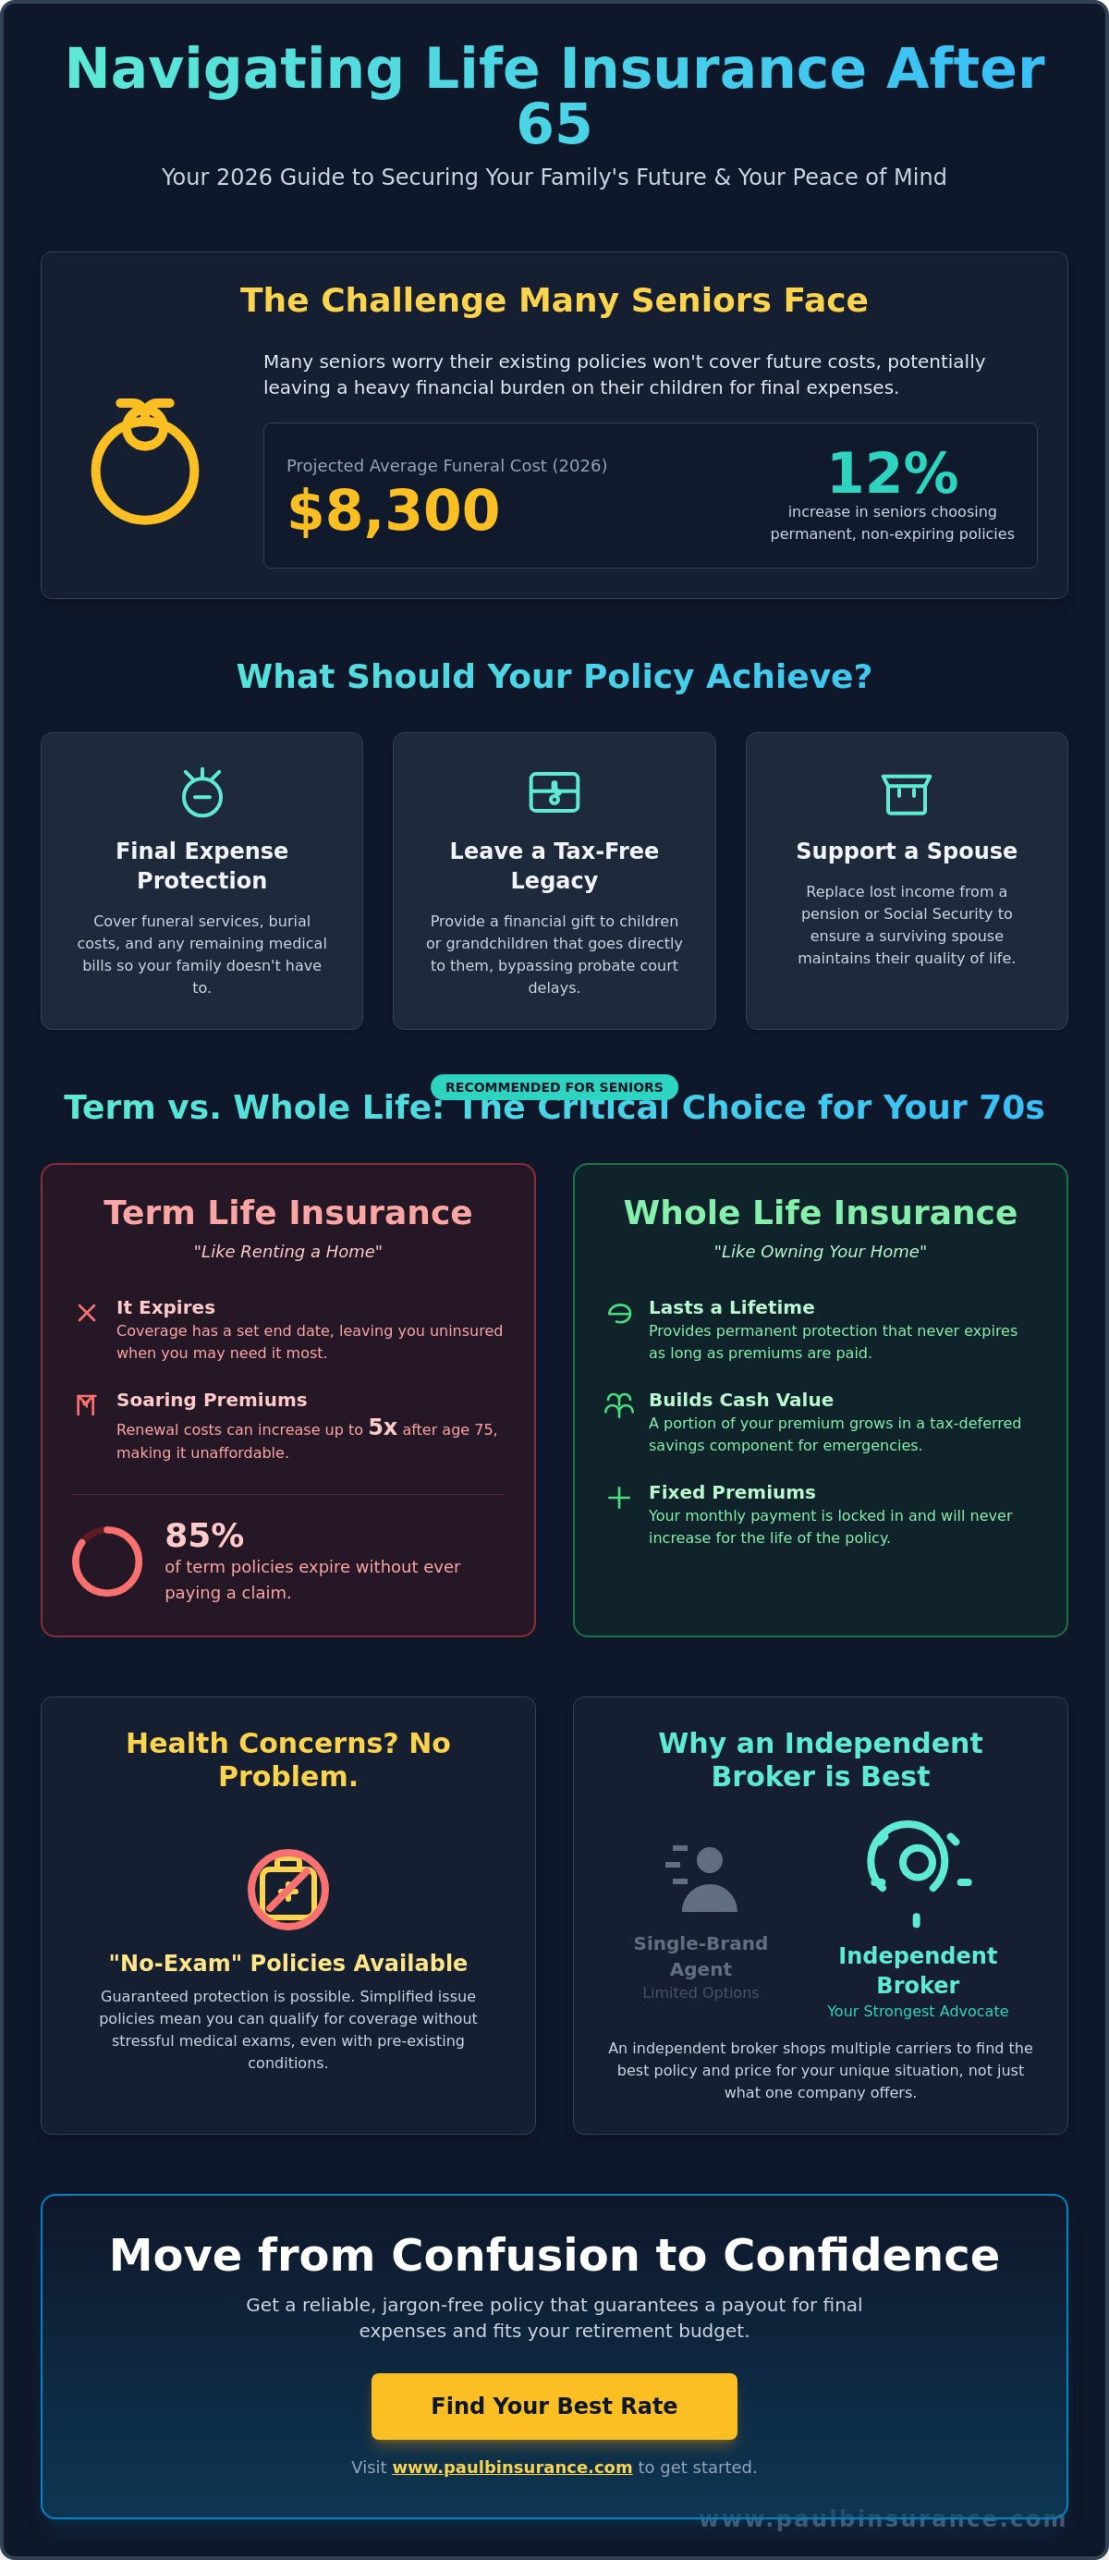
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
