Finding cheap life insurance Tulsa options in 2026 requires comparing local independent agencies with national carriers to leverage Oklahoma’s competitive insurance market. The most affordable path involves choosing a 10-to-30-year term life policy, utilizing accelerated underwriting for faster approval, and maintaining a healthy lifestyle to secure "Preferred Plus" rating tiers.
Securing financial protection for your family should not be a burden on your monthly budget. In Tulsa, the insurance landscape has evolved significantly by 2026, offering more digital-first options and localized discounts that reward residents for everything from their occupation to their zip code. Whether you are a young professional in the Pearl District or a growing family in South Tulsa, understanding the nuances of the local market is the first step toward finding a policy that balances low cost with high reliability.
Understanding the Tulsa Life Insurance Market in 2026
The insurance market in Oklahoma, and specifically in the Tulsa metropolitan area, is governed by the Oklahoma Insurance Department (OID). By 2026, the department has implemented several consumer-centric initiatives that make it easier for residents to compare rates transparently. Tulsa remains a hub for regional insurance offices, meaning residents have access to both large-scale national providers and specialized local brokers who understand the unique economic conditions of Green Country.
Life insurance rates are fundamentally a calculation of risk. In Tulsa, insurers look at regional health data, average life expectancy, and even local environmental factors. However, the primary drivers of your premium remain your personal health, age, and the type of policy you select. In 2026, many Tulsa-based employers have also updated their group life offerings, but these often lack the portability and coverage depth of a private, individual policy.
Types of Affordable Life Insurance Policies for Tulsa Residents
When searching for "cheap" options, it is vital to distinguish between low-cost premiums and high-value coverage. Not all inexpensive policies provide the same level of protection.
Term Life Insurance: The Budget-Friendly Standard
Term life insurance remains the most affordable option for the vast majority of Tulsa families. It provides coverage for a specific period—typically 10, 20, or 30 years. If the policyholder passes away during this term, the death benefit is paid out to beneficiaries tax-free.
In 2026, "laddering" term policies has become a popular strategy in Tulsa. This involves purchasing multiple smaller term policies that expire at different stages of life (e.g., when the mortgage is paid off or when children graduate from the University of Tulsa), which can significantly reduce total premium costs compared to one large, permanent policy.
Permanent Life Insurance: Evaluating Long-Term Value
While whole life or universal life insurance is more expensive than term, it offers lifelong coverage and builds cash value. For those seeking cheap life insurance Tulsa options, permanent policies are usually only recommended if there is a specific need for estate planning or lifelong final expense coverage. However, some "Guaranteed Universal Life" (GUL) policies offer a middle ground, providing permanent protection without the high cash-value accumulation costs, making them a cost-effective choice for seniors.
Final Expense Insurance for Seniors
Also known as "burial insurance," these are small whole life policies designed to cover funeral costs and minor debts. For Tulsa seniors on a fixed income, these policies offer a predictable monthly payment that does not increase over time. Local providers often offer these with simplified issue underwriting, meaning no medical exam is required.
Factors Influencing Your Life Insurance Rates in Oklahoma
To secure the lowest possible rates, you must understand how underwriters in 2026 evaluate your application.
Age and Health Status
Age is the most significant factor. Purchasing a policy in your 20s or 30s locks in rates that are exponentially lower than those available in your 50s. In terms of health, Tulsa residents who can demonstrate a history of regular check-ups and managed cholesterol or blood pressure levels often qualify for "Standard Plus" or "Preferred" rates.
Occupational and Lifestyle Risks
Oklahoma’s economy, rooted in energy, aerospace, and healthcare, means many residents work in specialized fields. If your job involves high-risk activities (such as certain offshore energy roles or high-altitude construction), your premiums may be higher. Conversely, many insurers offer "professional discounts" for educators, first responders, and healthcare workers in the Saint Francis or St. John health systems.
Credit History and Insurance Scores
It is a common misconception that credit only affects car insurance. In 2026, most life insurance carriers use a variation of an insurance-based credit score to determine policy eligibility and pricing. Maintaining a solid credit profile in Tulsa can lead to lower life insurance premiums, as insurers correlate financial responsibility with lower mortality risk.
Top-Rated Carriers Providing Competitive Rates in Tulsa
While many companies operate in Oklahoma, a few have distinguished themselves in 2026 for providing the most competitive rates for "cheap life insurance Tulsa options."
| Carrier | Best For | Typical Underwriting Style |
|---|---|---|
| Banner Life (Legal & General) | Low-cost Term Life | Very aggressive pricing for healthy individuals. |
| Protective Life | Long-term (30-40 year) Terms | Excellent for those wanting to lock in rates for decades. |
| Mutual of Omaha | Seniors & Final Expense | Strong local presence and simplified application process. |
| State Farm | Bundling Discounts | Best for those with existing home/auto policies in Tulsa. |
| Pacific Life | High Death Benefits | Competitive for business owners and estate planning. |
How to Compare Quotes Effectively
The search for cheap life insurance Tulsa options should not be limited to a single quote. In 2026, the use of independent brokers is the most effective way to shop. Unlike "captive" agents who work for one company, independent brokers can scan dozens of carriers simultaneously.
When comparing quotes, ensure you are looking at "guaranteed premiums." Some low-cost policies may feature "indeterminable premiums" that can increase after a certain period. Always ask for a policy illustration that shows the cost for the entire duration of the term.
Strategies to Lower Your Life Insurance Premiums
If you find that initial quotes are higher than your budget allows, consider these tactical adjustments:
- Improve Your Health Tier: In 2026, many carriers allow for a "re-rating" after one or two years. If you quit smoking or lose a significant amount of weight, you can request a new medical exam to move from a "Standard" to a "Preferred" rate.
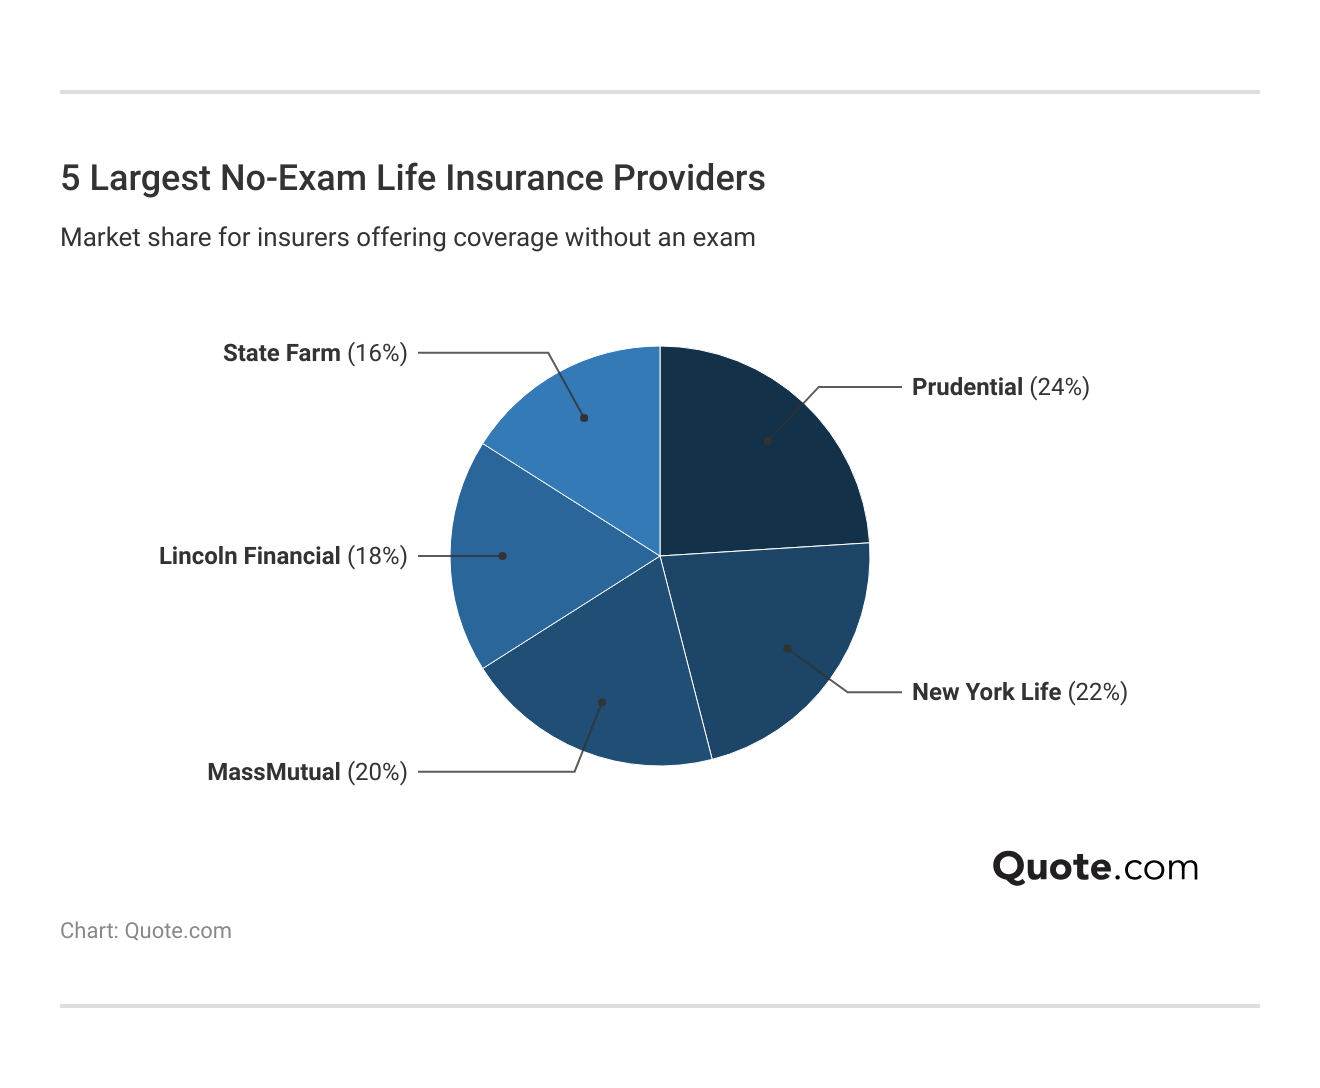
- Opt for Accelerated Underwriting: This "no-exam" path uses big data and medical records to approve you instantly. While it was once more expensive, by 2026, the price gap between exam-based and accelerated policies has nearly vanished for healthy applicants.
- Pay Annually: Most Tulsa insurance agencies offer a 2% to 5% discount if you pay your premium in one annual lump sum rather than monthly installments.
- Adjust the Coverage Amount: Sometimes, a small reduction in the death benefit (e.g., from $1 million to $750,000) can drop the premium into a different pricing "band," resulting in significant savings.
Local vs. National: Choosing an Agent in Tulsa
There is a distinct advantage to working with a local Tulsa agent. Local agents are familiar with Oklahoma-specific laws, such as the Oklahoma Life and Health Insurance Guaranty Association, which protects policyholders if a carrier becomes insolvent.
Furthermore, a local agent in Midtown or South Tulsa can provide a level of personalized service that digital-only platforms cannot. If a claim needs to be filed, having a local office to visit can ease the administrative burden on your beneficiaries during a difficult time. However, always ensure the local agent has access to national carriers to ensure you are getting the "cheap" rates promised by larger scale operations.
Common Pitfalls to Avoid When Shopping for Cheap Coverage
The quest for the lowest price can sometimes lead to mistakes that cost more in the long run.
- Under-insuring: Choosing a lower death benefit just to save $10 a month can leave your family short of the funds needed to pay off a mortgage or cover college tuition.
- Ignoring the Financial Strength Rating: A "cheap" policy is worthless if the company cannot pay the claim. Only consider carriers with an A.M. Best rating of A- or higher.
- Waiting Too Long: Every year you age, the baseline cost of life insurance increases by 5% to 8%. The cheapest time to buy life insurance in Tulsa is always today.
- Overlooking Riders: While riders (like Waiver of Premium or Child Term riders) add cost, some, like the Terminal Illness Rider, are often included for free and provide essential value.
Frequently Asked Questions
Can I get cheap life insurance in Tulsa if I use tobacco?
Yes, but "cheap" is relative. Tobacco users typically pay 2x to 3x more than non-smokers. However, in 2026, some carriers offer "smoker-friendly" rates for occasional cigar users or those who use nicotine replacement therapies. In Tulsa, working with a broker who knows which carriers are more lenient toward tobacco use is essential for finding the lowest rate.
Are "no-medical-exam" policies actually cheaper?
In the past, no-exam policies carried a premium. In 2026, for many healthy individuals under age 50, accelerated underwriting (which skip the exam) offers the exact same pricing as traditional policies. If you have significant health issues, however, a fully underwritten policy with a medical exam might actually be cheaper because it allows you to prove your health status to the insurer.
How does the Tulsa cost of living affect my insurance needs?
Tulsa’s cost of living is generally lower than the national average, which means your "needs analysis" might show you require a smaller death benefit than someone in New York or California. Lower mortgage balances and tuition costs at local institutions like Tulsa Community College or ORU mean your dollar goes further, potentially allowing you to opt for a smaller, cheaper policy.
What happens if I move away from Tulsa after buying a policy?
Your life insurance policy is portable. As long as you continue to pay the premiums, your coverage remains in force regardless of where you move within the United States. The rates you locked in while living in Tulsa will stay the same.
Is group life insurance through my Tulsa employer enough?
Generally, no. Most Tulsa employers offer coverage equal to 1x or 2x your annual salary. Financial experts typically recommend 10x to 15x your salary. Additionally, group coverage is usually not portable; if you leave your job at the Mid-Continent Tower or the Williams Center, you lose your coverage. A private, cheap life insurance policy provides consistent protection regardless of your employment status.
Final Recommendations for Tulsa Residents
To secure the most affordable life insurance in Tulsa in 2026, start by calculating your actual need using a DIME (Debt, Income, Mortgage, Education) analysis. Once you have a coverage amount in mind, gather quotes from at least three different sources: a national digital platform, a local captive agent (like State Farm or Farmers), and an independent broker.
Prioritize term life insurance unless you have a specific lifelong financial obligation. If you are healthy, aim for a "no-exam" policy to save time, but be prepared to undergo a physical if it means dropping your premium into a lower bracket. By acting while you are young and healthy, you can lock in a rate that protects your family's future for the price of a few meals at a local Tulsa restaurant each month.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
