
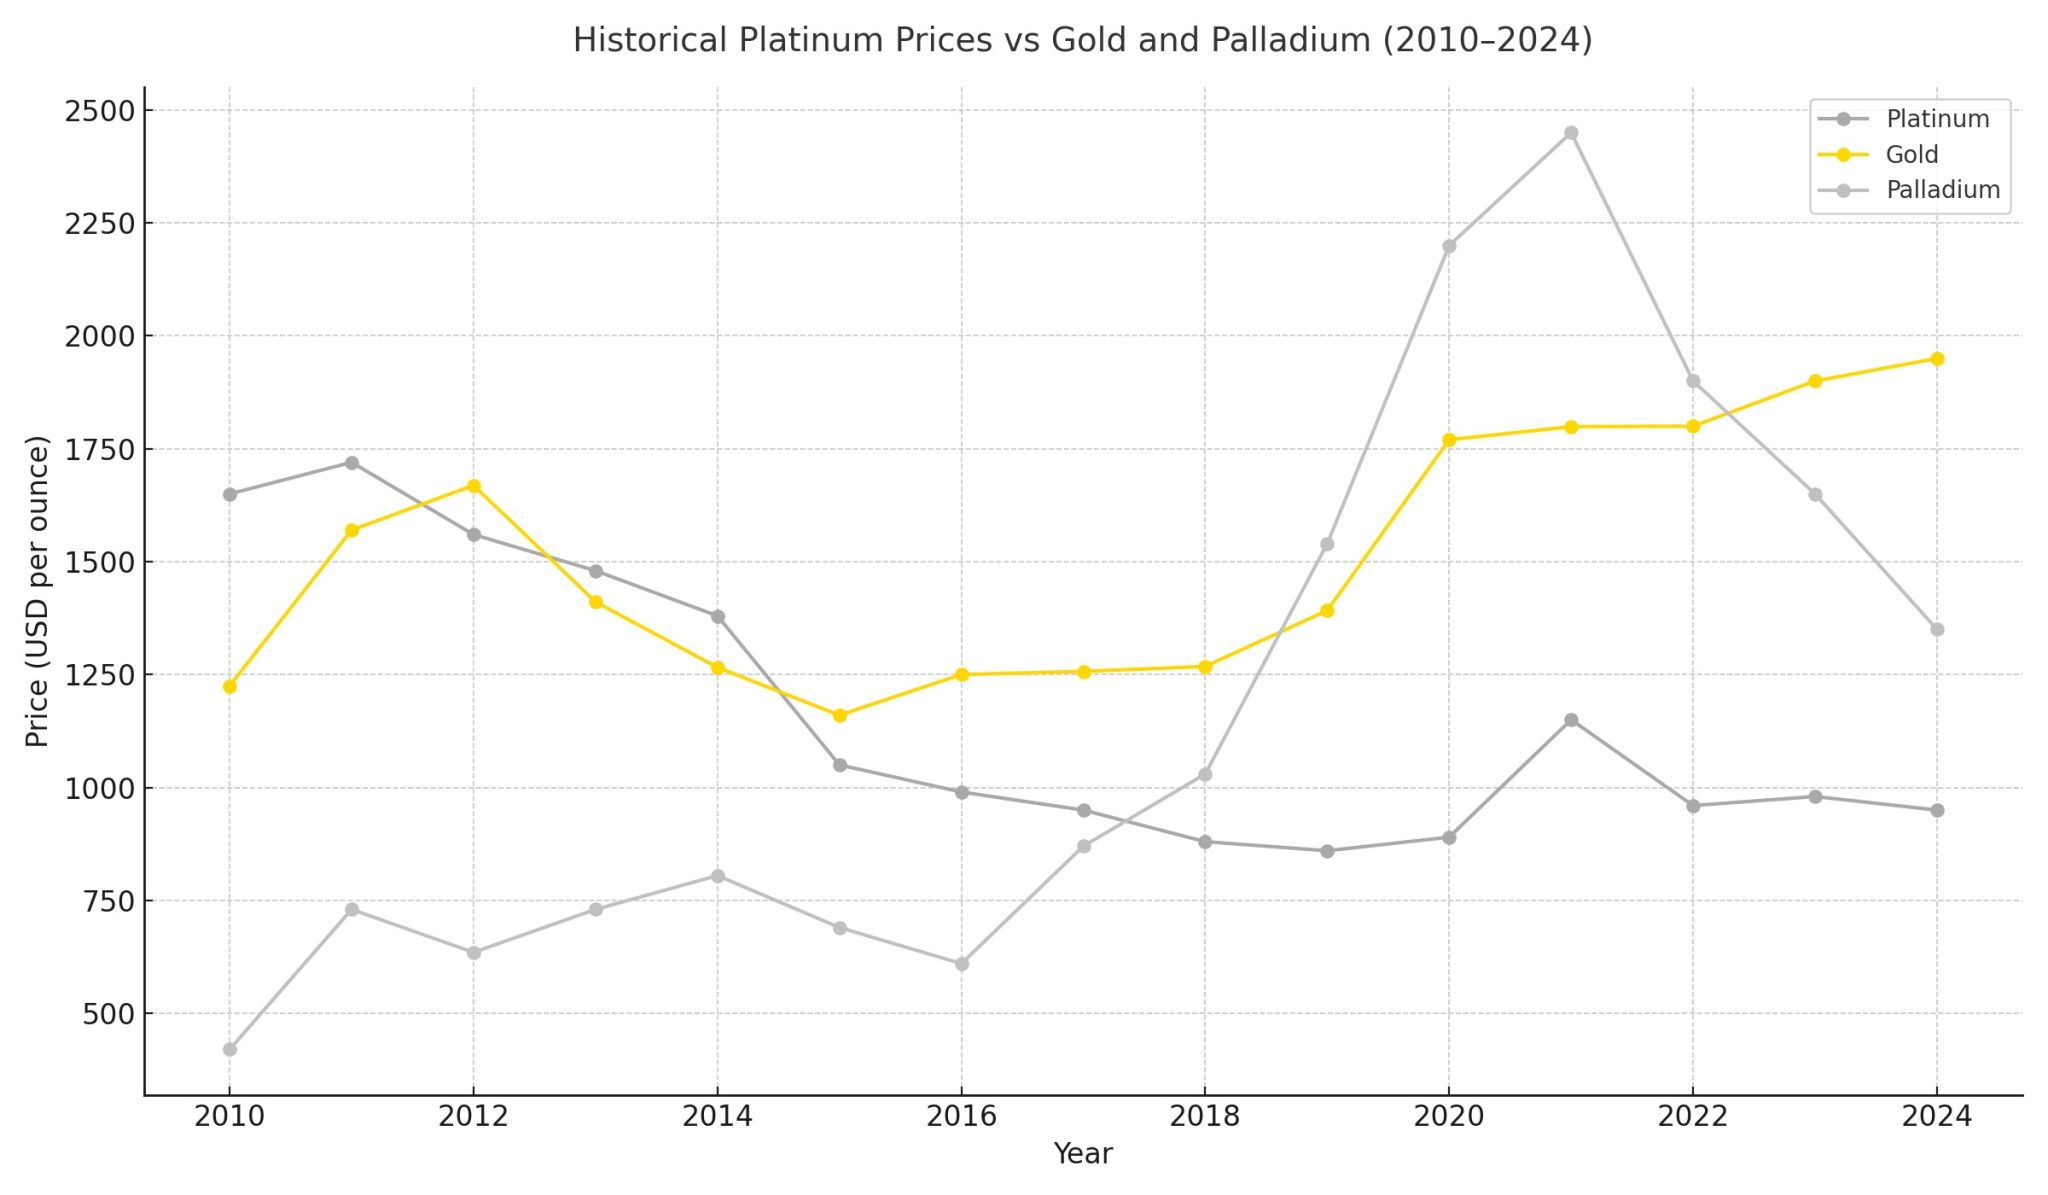
The price of platinum compared to gold has historically favored gold, with platinum trading at a premium for much of the late 20th and early 20th centuries before experiencing a structural inversion where gold became significantly more expensive. This dynamic is driven by differences in industrial utility, mining supply constraints, macroeconomic sentiment, and investor safe-haven demand.
Understanding the Precious Metals Market
Precious metals have served as a store of value, a medium of exchange, and an essential input for industrial manufacturing for centuries. Among the suite of precious metals—which includes silver, palladium, rhodium, gold, and platinum—gold and platinum occupy a unique tier. They are scarce, highly durable, and possess distinct chemical and physical properties that dictate their market value.
To understand why the price of platinum compares the way it does to gold, one must look beyond simple aesthetics. Gold is primarily a monetary asset and a luxury good, with central banks and private investors holding vast reserves as a hedge against inflation and currency devaluation. Platinum, by contrast, is deeply tied to the global industrial economy, particularly the automotive sector, chemical manufacturing, and green energy technology.
Historical Price Dynamics: When Platinum Outpaced Gold
For decades leading up to the 2008 global financial crisis, platinum routinely commanded a higher price per ounce than gold. During economic expansions, robust industrial demand for catalytic converters and jewelry pushed platinum prices to significant premiums—sometimes double the price of gold. Investors viewed platinum as a rarer, more industrially vital asset, often dubbed the "rich man's gold."
However, the economic shocks of 2008 fundamentally altered this relationship. As industrial demand plummeted during the global recession, platinum prices crashed much harder than gold prices, which were buoyed by safe-haven buying.
Following that recovery period, structural changes in the automotive industry—specifically the "dieselgate" emissions scandal in 2015, which accelerated a shift away from diesel engines (the primary users of platinum auto-catalysts) toward gasoline engines (which traditionally use palladium)—depressed long-term platinum demand. Gold, meanwhile, experienced sustained central bank buying and institutional investment inflows, widening a valuation gap that has largely persisted.
Key Drivers Influencing the Price Ratio
Evaluating the price of platinum compared to gold requires analyzing several interconnected market mechanics. Unlike consumer goods whose prices are set by supply and demand curves alone, precious metals are heavily influenced by speculative positioning, currency fluctuations, and geopolitical stability.
Supply and Mine Production
Platinum is exceptionally rare compared to gold. Annual mine production of platinum is a fraction of gold's output. The vast majority of the world's platinum—roughly 70% to 80%—is mined in a single country: South Africa. This geographic concentration makes the platinum supply chain vulnerable to labor strikes, power grid instability, and political shifts.
Gold mining, conversely, is geographically diversified across multiple continents, including Australia, Russia, Canada, the United States, and various African and South American nations. While gold is also scarce, its above-ground stocks are immense. Central banks hold thousands of tonnes of gold in reserve, and because gold is rarely consumed or destroyed in industrial processes, almost every ounce of gold ever mined still exists in some form. Platinum, because of its industrial application, is frequently consumed and lost, making its recycling stream smaller and its active supply tighter.
Industrial Demand Versus Monetary Demand
The core divergence between gold and platinum lies in their end-use profiles:
- Gold Demand: Roughly 40% to 50% of annual gold demand comes from jewelry, with the remainder split between investment (bars and coins), central bank purchases, and a smaller component of high-end electronics. Gold behaves as a financial asset.
- Platinum Demand: Historically, over 40% of platinum demand originates from the automotive sector for use in catalytic converters to reduce harmful emissions. Additional demand comes from the chemical, petroleum refining, glassmaking, and medical device industries, alongside jewelry and investment. Platinum behaves as an industrial commodity.
Because of this industrial exposure, platinum prices tend to rise during periods of synchronized global economic growth when manufacturing output is high. Gold prices tend to excel during periods of economic uncertainty, high inflation, geopolitical conflict, or low interest rates.
Macroeconomic Factors and Investor Sentiment
Currency markets and interest rate environments exert immense pressure on both metals. Both gold and platinum are globally priced in U.S. dollars. When the U.S. dollar strengthens, foreign buyers face higher local costs to purchase these metals, typically putting downward pressure on prices. Conversely, a weakening dollar often boosts both commodities.
Investor sentiment also dictates capital flows. Exchange-Traded Funds (ETFs) and futures markets allow institutional and retail investors to buy large blocks of metal without taking physical delivery. Shifts in speculative positioning can cause rapid price swings that disconnect short-term market prices from underlying physical supply and demand fundamentals.
| Feature / Metric | Gold | Platinum |
|---|---|---|
| Primary Driver | Monetary asset, safe haven, jewelry | Industrial use, auto-catalysts, jewelry |
| Annual Mine Supply | Approximately 3,000 to 3,500 metric tonnes | Approximately 170 to 200 metric tonnes |
| Geographic Concentration | Diversified globally | Highly concentrated (South Africa, Russia) |
| Above-Ground Stocks | Massive; centuries of accumulated supply | Relatively low; heavily consumed in industry |
| Market Volatility | Moderate; buffers against systemic risk | Higher; sensitive to industrial cycles |
Substitution and Technological Shifts
The relative pricing of platinum and gold—and its sister metal, palladium—is also influenced by technological substitution. Because platinum group metals (PGMs) share similar catalytic properties, automakers and industrial refiners can substitute one for another when price imbalances become extreme.
For instance, when palladium prices surged to historic highs in the early 2020s, automotive engineers accelerated programs to substitute palladium with cheaper platinum in gasoline vehicle catalytic converters. This structural shift helped support platinum demand even as diesel vehicle production declined. Similar substitution dynamics can occur between platinum and gold in industrial applications, though gold is rarely used for heavy catalytic duties due to its higher cost and different chemical behavior.
Furthermore, the global transition toward hydrogen fuel cell technology and green energy infrastructure has positioned platinum as a critical material for the future. Platinum serves as an essential catalyst in proton exchange membrane (PEM) fuel cells and water electrolyzers used to produce green hydrogen. If the hydrogen economy scales significantly, long-term industrial demand for platinum could outstrip supply growth, potentially narrowing or reversing the historical price gap with gold.
Investment Considerations and Portfolio Role
For private investors and wealth managers, comparing the price of platinum to gold involves assessing risk tolerance, investment horizon, and portfolio diversification goals.
Gold is universally recognized as a core portfolio hedge. It has a multi-millennium track record of preserving purchasing power across major currency collapses and geopolitical upheavals. It exhibits lower volatility relative to industrial commodities and serves as a reliable shock absorber during equity market drawdowns.
Platinum, on the other hand, is generally treated as a tactical or growth-oriented precious metal investment. Its higher volatility means it can deliver substantial capital gains during economic booms or supply squeezes, but it also exposes investors to sharp drawdowns during industrial recessions. Furthermore, retail platinum bullion purchases often carry higher manufacturing premiums and wider bid-ask spreads compared to standard gold bars and coins, reflecting the specialized refining required to work with the metal.
Frequently Asked Questions
Why is gold more expensive than platinum today?
Gold is more expensive primarily because of its role as a global monetary asset and safe-haven reserve. While platinum is much rarer in terms of annual mine production, its heavy reliance on industrial demand—particularly automotive manufacturing—leaves it vulnerable to economic slowdowns and shifting industrial technologies. Gold benefits from massive above-ground reserves held by central banks and investors who treat it as a universal store of value.
Can platinum surpass the price of gold again?
Yes, it is historically possible. From the late 1980s until 2008, platinum traded at a significant premium over gold for extended periods. Whether it surpasses gold again depends on future macroeconomic conditions, a rebound in industrial manufacturing intensity, supply disruptions in major mining jurisdictions like South Africa, and the large-scale adoption of hydrogen fuel cell technologies that heavily utilize platinum.
Is platinum a better investment than gold?
Neither metal is universally "better"; their suitability depends entirely on an investor's financial objectives. Gold provides superior stability, liquidity, and wealth preservation during crises. Platinum offers higher volatility and potential growth tied to industrial demand and green energy transitions, but carries greater risk and price cyclicality.
How does South Africa impact the price of platinum?
South Africa produces the majority of the world's primary platinum supply, primarily from the Bushveld Igneous Complex. Labor strikes, safety stoppages, wage disputes, or structural energy shortages within South Africa's national power grid can severely restrict global platinum output, creating immediate supply deficits and upward price pressure.
How do taxes and premiums differ between gold and platinum purchases?
Retail physical platinum bullion often carries higher manufacturing premiums (the cost over the spot price of the metal) than gold. This is due to the smaller scale of the retail platinum market, the higher melting point and specialized tooling required to fabricate platinum items, and potential tax classifications (such as higher capital gains or sales tax treatments in certain jurisdictions) compared to recognized gold bullion coins and bars.
Conclusion and Next Steps
Evaluating the price of platinum compared to gold reveals a complex interplay between monetary history and modern industrial economics. While gold remains the undisputed king of safe-haven assets, platinum offers a unique value proposition rooted in scarcity and critical industrial applications. Investors and market observers should monitor macroeconomic growth indicators, South African mining stability, and emerging green energy technologies to gauge future shifts in this historic metal ratio.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
