State Farm operates as a mutual insurance company, meaning it is owned by its policyholders rather than shareholders, a structure that influences its approach to coverage, claims processing, and customer service. Understanding how this organization handles auto and home insurance requires a clear grasp of their specific policy structures, the bundling process, and the role of local agents in the 2026 insurance landscape.
Navigating insurance options at State Farm involves evaluating standard coverage tiers, optional endorsements that tailor policies to specific property or vehicle risks, and the logistical steps required to manage these policies through their digital portal or local agency network. Whether you are a first-time homeowner or seeking to consolidate vehicle coverage, the primary goal is ensuring that your financial exposure is minimized through a combination of mandatory legal requirements and elective protection.
The Structure of State Farm Insurance Products
State Farm provides personal lines of insurance that are designed to be modular. While auto and home insurance are distinct products, the company encourages integrating them into a singular relationship managed through a personal agent.
Auto Insurance Fundamentals
At its core, State Farm auto insurance is built upon state-mandated coverages such as liability, which pays for the damages you cause to others, and uninsured motorist coverage. However, the company distinguishes itself through a variety of elective additions:
- Comprehensive Coverage: Protects against non-collision events, including theft, vandalism, and environmental damage like hail or fire.
- Collision Coverage: Covers repairs to your vehicle resulting from an accident, regardless of who is at fault.
- Emergency Road Service: An add-on that assists with common roadside issues like lockouts, dead batteries, or mechanical failures that leave a vehicle immobilized.
- Rental Car Reimbursement: Covers the cost of a rental vehicle while your primary vehicle is undergoing repairs covered under a claim.
Homeowners Insurance Fundamentals
Homeowners insurance at State Farm is a property and liability package. It protects the physical structure of your dwelling, your personal property within that dwelling, and your legal liability should someone be injured on your premises.
The standard policy—often referred to as an HO-3 form—covers the dwelling on an open-peril basis, meaning all causes of loss are covered unless specifically excluded (such as floods or earthquakes). Conversely, personal property is often covered on a named-peril basis, meaning only those events explicitly listed in the policy—such as fire, lightning, windstorm, or theft—are covered.
The Mechanics of Bundling and Multi-Policy Discounts
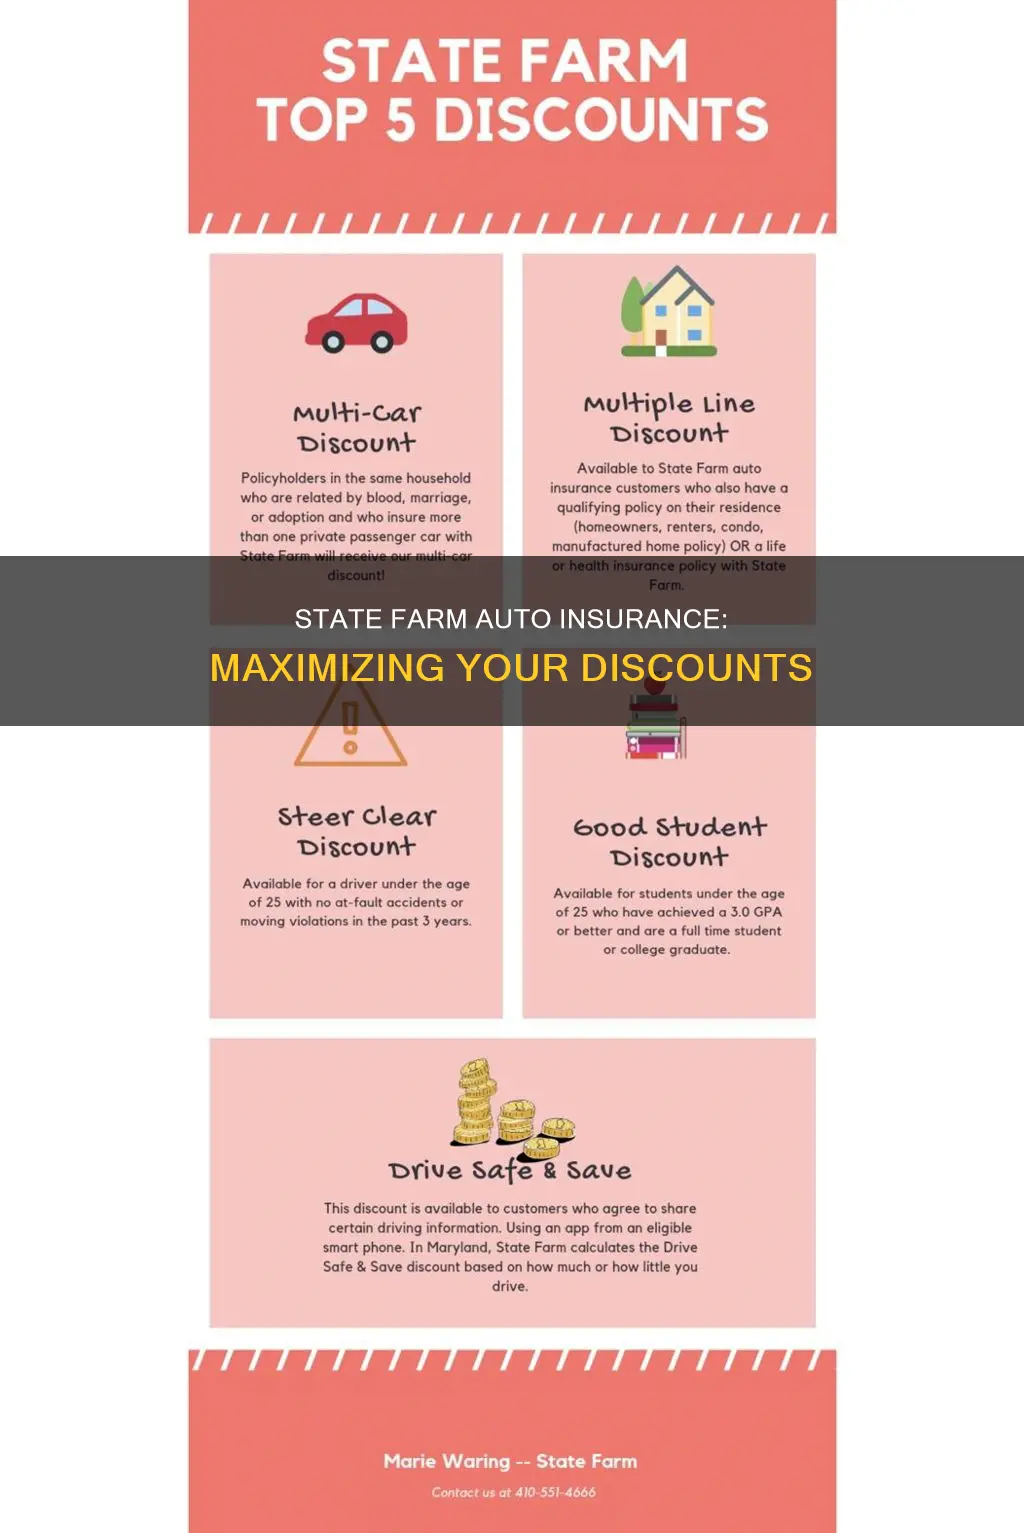
The most common financial strategy for State Farm clients is the "bundle," which links auto and home insurance under one roof. This is not merely a marketing tactic; it is an administrative integration that often leads to a multi-policy discount on both premiums.
When you bundle, you typically manage both policies through a single agent. This agent acts as a centralized point of contact for updates, policy changes, and claim advocacy. From a technical standpoint, bundling simplifies your "insurance footprint," allowing the company to view your total risk profile holistically. If an accident occurs that affects your home (for example, a vehicle crashing into your garage), the integration between the auto claim and the home claim is significantly more streamlined than if the policies were held by different carriers.
Comparison of Coverage Scenarios
| Feature | Auto Insurance Policy | Homeowners Insurance Policy |
|---|---|---|
| Primary Risk | Bodily injury & property damage liability | Dwelling & personal property protection |
| Deductible Type | Per-incident (Collision/Comprehensive) | Fixed dollar or percentage of dwelling limit |
| Liability Scope | Covers damages to others in accidents | Covers guests/others on property |
| Optional Add-ons | Roadside assistance, rental car, GAP | Water backup, identity theft, personal articles |
Eligibility and Requirements for Coverage
Securing insurance with State Farm in 2026 involves a verification process that varies based on your location and the specific assets being insured. For auto insurance, you must provide the Vehicle Identification Number (VIN), current mileage, and primary garaging address. For home insurance, the company requires information regarding the age of the roof, the type of electrical and plumbing systems, and any security measures like monitored alarm systems.
The Role of Underwriting
Underwriting is the process by which State Farm determines if they will insure you and at what price. This process utilizes various data points, including:
- Claims History: Past incidents, whether or not a claim was paid out, significantly impact your risk profile.
- Credit-Based Insurance Scores: In states where permitted by law, your financial stability is a factor in premium calculation.
- Property Inspection: For home insurance, the company may conduct an exterior inspection to verify the condition of the dwelling and identify any significant hazards, such as an unfenced swimming pool or an aging roof that could collapse under snow load.
Navigating Claims and Support
When a loss occurs, the efficiency of your insurance relies on the reporting process. State Farm utilizes a multi-channel claims system. You can initiate a claim via the mobile application, through your local agent’s office, or via the 24/7 call center.
The Claims Process Workflow
- Notification: File the claim as soon as possible after the event. Documentation such as photos, police reports, and inventory lists should be provided immediately.
- Assignment: A claims adjuster is assigned to your file. They are responsible for investigating the circumstances and assessing the damage.
- Assessment: The adjuster determines the scope of the loss relative to the coverage limits defined in your specific policy.
- Resolution: If the claim is approved, the company issues payment based on the terms (e.g., Replacement Cost Value or Actual Cash Value).
A critical distinction for homeowners is the difference between Replacement Cost and Actual Cash Value. Replacement cost pays to repair or replace your property at current market prices without a deduction for depreciation. Actual Cash Value factors in depreciation, meaning you receive a lower settlement if the items were older at the time of loss. Ensure you verify which valuation method your policy uses, as it is a common point of confusion during claim settlement.
Common Mistakes and How to Avoid Them
Even with a reputable carrier, policyholders often make errors that lead to coverage gaps or claim denials. Being aware of these pitfalls is essential for effective risk management.
Underinsuring Property
One of the most frequent errors is failing to update your home insurance coverage limits after major renovations or market appreciation. If your home’s value has increased due to additions or remodeling, your current policy limit may be insufficient to cover a total rebuild in 2026. Review your dwelling coverage limit annually to ensure it reflects current local construction costs, not just the market value of the home.
Misunderstanding Policy Exclusions
Many policyholders assume "full coverage" implies protection against every possible incident. In reality, standard homeowners policies almost universally exclude damage caused by floods and earthquakes. If you live in an area prone to these events, you must purchase separate, specialized policies or endorsements to avoid catastrophic financial loss. Never assume you are protected until you have verified the specific exclusions in your written policy document.
Overlooking the Personal Articles Policy
Standard homeowners insurance usually caps the payout for high-value items like jewelry, fine art, or collections. If you own items that exceed these sub-limits, you should consider a "Personal Articles Policy." This provides broader coverage, often with no deductible, and protects against a wider range of perils, including accidental loss or mysterious disappearance.
Digital Integration and Account Management
By 2026, the State Farm digital ecosystem allows for significant autonomy. The mobile app and web portal are designed to facilitate policy maintenance without needing to visit an agency. You can pay bills, download proof of insurance (auto ID cards), and even submit photos for simple auto claims directly through your smartphone.
However, despite these digital conveniences, the agent model remains the backbone of the company. If you encounter a complex issue—such as a dispute over a claim denial or a nuanced question about liability coverage—the digital interface may be insufficient. In such cases, your local agent is your primary advocate. They have the ability to review your entire portfolio and can often provide context that a centralized customer service representative cannot.
Frequently Asked Questions
What happens to my auto insurance if I move to a different state?
Insurance regulations are state-specific. If you move, you must notify your agent. Your premiums will likely change because factors like local traffic density, crime rates, and state legal requirements differ. You must update your garaging address immediately to ensure your policy remains compliant with state law.
Can I change my deductibles at any time?
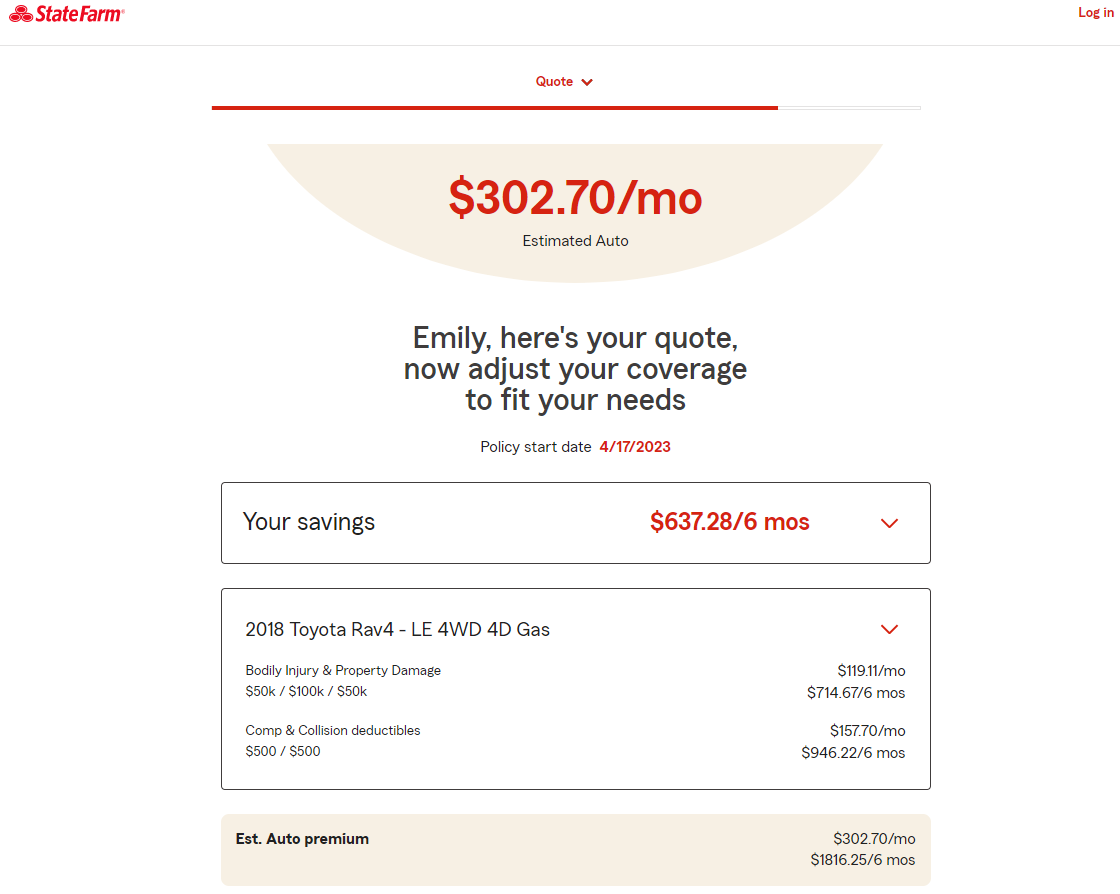
Yes, you can request a change to your deductibles at any time. However, be aware that lowering your deductible will increase your premium, while raising it will decrease your premium. It is advisable to maintain a deductible that you can afford to pay out-of-pocket if a sudden, unexpected loss occurs.
Does my homeowners policy cover my car if it is damaged in my garage?
Generally, no. Your homeowners policy covers the dwelling and personal property, but vehicles are explicitly excluded from the personal property section. Damage to your vehicle, whether it occurs in the garage or on the road, must be handled through your auto insurance policy, specifically under comprehensive coverage.
Why did my premium increase this year if I haven't filed any claims?
Insurance premiums are based on aggregate risk. Even if your personal history is clean, premiums can rise due to broader factors such as an increase in local repair costs for vehicles, a higher frequency of weather-related claims in your region, or inflation affecting construction materials for homes.
What is "gap" coverage and do I need it?
GAP (Guaranteed Asset Protection) coverage pays the difference between what you owe on your auto loan and what the insurance company pays for the vehicle if it is totaled. If you are leasing a car or have a loan with a small down payment, this is highly recommended, as your car's market value may be lower than your outstanding loan balance.
Recommendation for Policyholders
For those seeking to maximize the value of their insurance at State Farm, the most practical next step is a "Policy Review Appointment." Reach out to your local agent to schedule a meeting. Provide them with an updated list of your assets, including any recent home improvements and the current mileage of your vehicles. Ask specifically for a breakdown of your current liability limits to ensure they are sufficient for your current net worth. By proactively verifying that your coverage matches your current life circumstances, you eliminate the risk of discovering an underinsured position only after a loss has occurred.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
