Understanding the Typical Premium on a 53 Year Old Male for Term Life Insurance
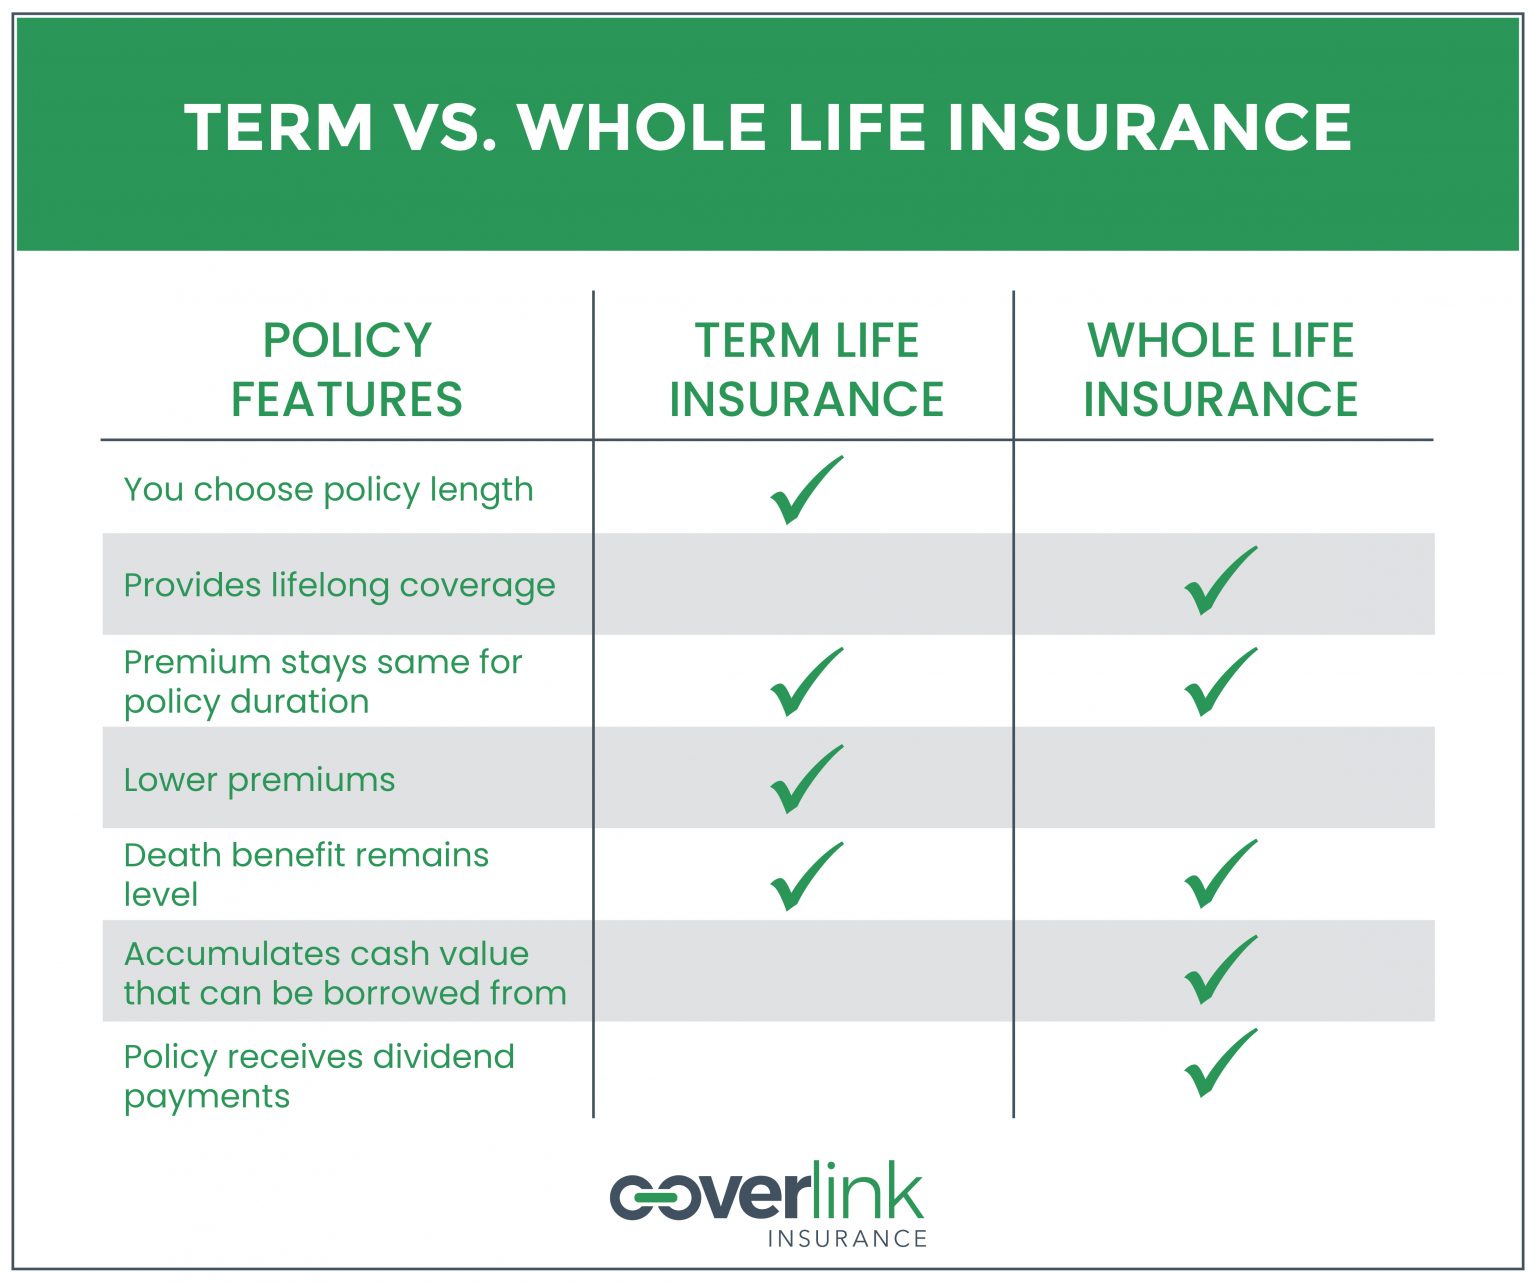
At age 53, a male seeking term life insurance will typically face monthly premiums ranging from $80 to $250 for a $500,000 policy, depending heavily on health status, lifestyle, and the length of the term. Because insurers perceive higher mortality risk at this stage of life compared to younger applicants, actuarial calculations become more sensitive to medical history, tobacco usage, and family health factors.
The Dynamics of Life Insurance Pricing at Age 53
Life insurance is fundamentally a risk-management product. For a 53-year-old male, the primary determinant of premium costs is the insurer's assessment of mortality risk—the statistical probability that the policyholder will pass away during the policy term. By age 53, the actuarial tables used by insurance companies reflect a transition; the "sweet spot" of low-risk, youthful health has passed, and underwriting begins to focus more intently on the presence of chronic conditions or age-related markers.
Insurance companies categorize risk into "underwriting classes." These classes serve as the primary drivers of premium pricing. Even at age 53, an applicant who is a non-smoker, maintains a healthy weight, has normal blood pressure, and possesses a clean medical record may qualify for a "Preferred" or "Preferred Plus" rating. Conversely, individuals with pre-existing conditions such as Type 2 diabetes, high cholesterol, or a history of cardiovascular issues will be placed in "Standard" or "Substandard" (often called "Table Rated") categories, which can significantly inflate premiums.
Determining the Cost Variables for Term Policies
Term life insurance is distinct from permanent (whole or universal) insurance because it covers a specific duration—typically 10, 15, 20, or 30 years. For a 53-year-old, the length of the term itself acts as a massive cost lever.
1. The Term Duration
A 53-year-old requesting a 20-year term policy is asking the insurer to cover them until age 73. Because the statistical likelihood of death is higher in the late stages of that term, the annual premium is priced to reflect that entire risk profile. Many 53-year-olds find that a 10-year or 15-year term is sufficient to cover outstanding mortgage debts or the remaining years until full retirement, which often results in lower monthly costs than a 20-year term.
2. The Face Amount (Death Benefit)
The face amount is the payout the beneficiaries receive upon the death of the insured. Predictably, the higher the death benefit, the higher the premium. However, the relationship is not always linear. Many carriers offer "banded" pricing, where buying a policy of $1,000,000 might have a lower cost-per-thousand-dollars-of-coverage compared to a $250,000 policy due to administrative efficiencies.
3. Health and Lifestyle Underwriting
Underwriting is the process by which an insurance company evaluates your risk. At 53, this almost always involves a medical exam—or at least a "paramedical" exam—where a technician measures height, weight, blood pressure, and draws blood/urine samples. Markers for blood glucose and cholesterol levels are scrutinized heavily at this age.
Comparative Cost Estimates for 53-Year-Old Males
The following table provides a generalized estimation of monthly premiums for a 53-year-old male in good health. These figures are averages based on 2026 market standards and are for illustrative purposes; individual quotes will vary based on specific medical findings and carrier guidelines.
| Policy Amount | 10-Year Term (Monthly) | 20-Year Term (Monthly) |
|---|---|---|
| $250,000 | $55 – $85 | $110 – $160 |
| $500,000 | $90 – $140 | $190 – $280 |
| $1,000,000 | $170 – $260 | $360 – $550 |
Note: These estimates assume a non-smoker with a "Standard" to "Preferred" health rating. Tobacco users typically see premiums 200% to 300% higher than non-smokers.
The Role of Medical History and "Table Ratings"
If you are 53 and have a history of health issues, you may encounter a "Table Rating." Insurers use a table system (often labeled Table A through Table P) to adjust premiums for individuals with health risks that fall outside the "Standard" classification. Each table represents an additional percentage increase over the base premium—usually 25% to 50% per table.
It is vital to be transparent during the application process. Attempting to hide a chronic condition or a smoking habit is often caught during the blood and urine analysis. If the insurer discovers a misrepresentation, they have the right to decline coverage entirely, and your name may be flagged in the Medical Information Bureau (MIB) database, making it significantly harder to secure coverage with other providers in the future.
Strategic Considerations for Men in Their 50s
When shopping for coverage at 53, consider the following strategies to manage the cost and effectiveness of your policy:
- Laddering Policies: Rather than buying one large 20-year policy, consider "laddering." This involves buying a 10-year policy to cover a specific short-term liability (like a child's college education or a lingering debt) and a 20-year policy for long-term income replacement. This can often be cheaper than a single, long-duration, high-value policy.
- The "No-Exam" Alternative: Some insurers offer "accelerated underwriting," which uses digital health data, prescription history, and motor vehicle records to approve policies without a physical medical exam. While these are often more expensive than fully underwritten policies, they provide a faster path to coverage for those with minor health concerns.
- Conversion Privileges: Always check if your term policy is "convertible." A conversion privilege allows you to swap your term policy for a permanent life insurance policy later in life without having to undergo a new medical exam. This is an essential safety net if your health declines after your policy is issued.
Common Pitfalls to Avoid
The most common mistake men make in their 50s is waiting too long to apply. Premiums increase every year you age, but they also increase if you develop new health conditions. If you are 53, locking in a rate now is almost always cheaper than waiting until you are 55 or 58, even if you are in perfect health today.
Another pitfall is underestimating the need for coverage. Many 53-year-olds assume that because their children are grown or their mortgage is partially paid off, they need less coverage. However, life insurance at this age is often less about protecting young dependents and more about estate liquidity, covering final expenses, and ensuring a spouse has sufficient income to maintain their standard of living during retirement.
Frequently Asked Questions
Is it too late to get affordable term life insurance at 53? It is not too late, though the rates will be higher than they were in your 30s or 40s. The key is to shop among multiple carriers, as different insurance companies have varying "sweet spots" for underwriting older applicants. Some companies specialize in health conditions like controlled diabetes or hypertension, and their rates may be significantly more competitive for you than those of a standard provider.
Does my occupation affect my premium? Generally, your occupation only affects your premium if you engage in "hazardous avocations" or extremely dangerous high-risk professions. For most standard office or professional roles, your occupation has little to no impact on your life insurance premium compared to your medical profile.
What happens if I stop smoking after my policy is issued? If you currently smoke, you will pay "smoker" rates. However, many policies allow you to apply for a "reconsideration" or "reclassification" after you have been nicotine-free for a certain period (usually 12 to 24 months). By proving you have quit, you may be able to have your premiums reduced to non-smoker levels without needing a new policy.
Should I buy term life through my employer? Employer-provided life insurance is a valuable benefit, but it usually isn't enough. It is often tied to your job—if you leave the company or are laid off, you usually lose the coverage. Furthermore, the death benefit is typically capped at a multiple of your salary. Using an individual term life policy as your foundation provides portability and ownership that employer-provided plans cannot match.
How long does the application process take at age 53? With traditional fully underwritten insurance, the process usually takes 4 to 8 weeks. This includes scheduling the medical exam, the lab testing of your samples, and the underwriter reviewing your records. Accelerated underwriting processes can sometimes conclude in as little as 48 hours to 10 days if all your medical records are available digitally.
Recommended Next Actions
If you are 53 and considering term life insurance, start by calculating your specific needs. Do not simply guess an amount; add up your outstanding mortgage, funeral costs, and the annual income you would need to replace for your spouse to maintain their lifestyle for a specific number of years.
Once you have a target death benefit, contact a licensed independent life insurance agent. Unlike "captive" agents who only sell for one company, independent agents can pull quotes from a dozen or more top-rated carriers, allowing you to compare pricing and underwriting appetites side-by-side. Ensure that any policy you consider includes a conversion option, providing you with long-term flexibility should your financial or health circumstances change in the future.

Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
