Life insurance proceeds are included in your taxable estate if you held "incidents of ownership" at death or if the proceeds are payable to your estate. While generally income-tax-free for beneficiaries, these funds are counted toward the federal estate tax threshold, which in 2026 has significantly decreased due to sunsetting legislation.
The Critical Distinction: Income Tax vs. Estate Tax
When discussing life insurance and taxes, the most common source of confusion is the difference between income tax and estate tax. Most individuals are aware that life insurance is "tax-free," but this statement is only partially accurate.
For the vast majority of beneficiaries, the death benefit received from a life insurance policy is exempt from federal income tax. Whether the payout is $50,000 or $5,000,000, the Internal Revenue Service (IRS) typically does not require the recipient to report this as taxable income. However, the estate tax is a different matter entirely.
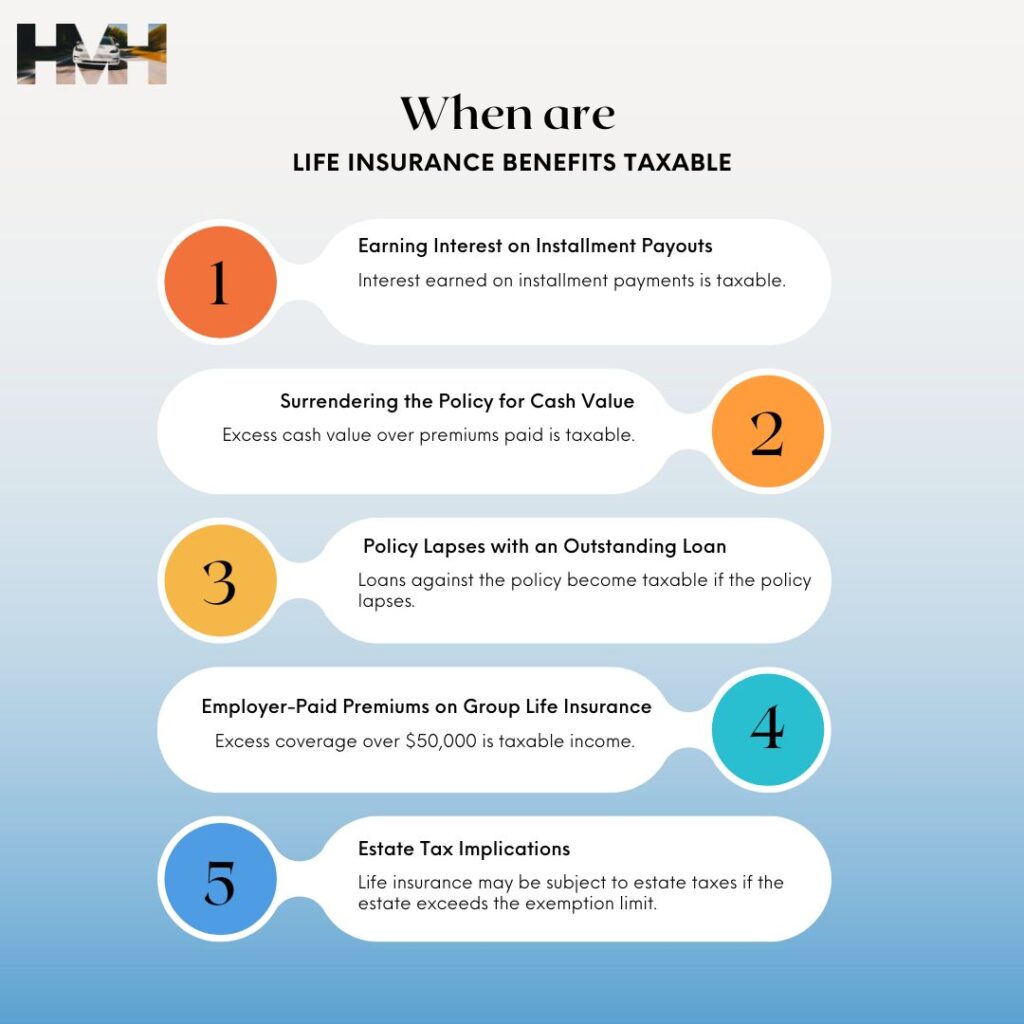
The federal estate tax is a levy on the transfer of property at death. The "gross estate" includes everything you own or have an interest in at the time of your death. In 2026, the inclusion of life insurance proceeds in the gross estate has become a primary concern for middle- to upper-income families because the federal exemption limit has significantly decreased following the expiration of the Tax Cuts and Jobs Act (TCJA) provisions.
Defining "Incidents of Ownership" Under IRC Section 2042
According to Internal Revenue Code Section 2042, life insurance proceeds are included in the decedent's gross estate if the decedent possessed any "incidents of ownership" in the policy at the time of death. This is the legal pivot point upon which estate tax liability turns.
"Incidents of ownership" does not simply mean owning the policy in a literal sense. It refers to the right of the insured or their estate to the economic benefits of the policy. The IRS interprets this broadly. If you have the power to do any of the following, you likely possess incidents of ownership:
- Changing the Beneficiary: The power to name who receives the death benefit.
- Surrendering or Canceling the Policy: The right to terminate the coverage.
- Assigning the Policy: The ability to transfer ownership or rights to another party.
- Revoking an Assignment: The power to undo a previous transfer of rights.
- Pledging the Policy for a Loan: Using the policy as collateral.
- Borrowing Against Cash Value: For whole life or universal life policies, the right to take a loan against the accumulated cash.
Even if you do not pay the premiums, if you retain the right to change the beneficiary, the full value of the death benefit is included in your taxable estate. This often catches taxpayers by surprise, as they may view a policy as "belonging" to their spouse or children, while legally retaining the right to alter the policy terms.

The Impact of the 2026 Federal Estate Tax Exemption Sunset
As of 2026, the landscape of estate planning has shifted dramatically. Between 2018 and 2025, the federal estate tax exemption was at historic highs (reaching over $13 million per individual in 2025). However, the provisions of the 2017 Tax Cuts and Jobs Act expired at the end of 2025.
In 2026, the base individual exemption has reverted to $5 million, adjusted for inflation, which places it at approximately $7 million. For a married couple, the combined exemption is roughly $14 million.
While $7 million sounds substantial, the inclusion of life insurance can quickly push a modest estate over this limit. Consider a professional with a $1.5 million home, $3 million in retirement accounts, $1 million in other investments, and a $2 million term life insurance policy. In 2025, this $7.5 million estate was well under the $13.61 million exemption. In 2026, however, this same individual would have a taxable estate exceeding the $7 million threshold, leading to a potential 40% tax on the excess amount.
The Three-Year Look-Back Rule: Timing Your Transfers
A common strategy to avoid estate tax is to transfer ownership of a life insurance policy to another person or a trust. However, Internal Revenue Code Section 2035 creates a significant hurdle known as the "Three-Year Rule."
If the insured owns a policy and transfers it to another entity (like a child or a trust) for less than full and adequate consideration, and then dies within three years of that transfer, the IRS ignores the transfer. The full proceeds are "pulled back" into the decedent's gross estate as if the transfer never happened.
This rule is designed to prevent "deathbed transfers" where individuals attempt to shed assets immediately before passing to avoid taxation. To successfully remove life insurance from your estate, you must outlive the transfer by at least 36 months. This makes early planning essential, especially for individuals with health concerns or those reaching advanced ages.
Strategic Mitigation: The Irrevocable Life Insurance Trust (ILIT)
To circumvent both the incidents of ownership and the estate tax inclusion, many taxpayers utilize an Irrevocable Life Insurance Trust (ILIT). An ILIT is a specialized legal entity designed specifically to own life insurance policies.
When structured correctly, the ILIT owns the policy, pays the premiums, and is named as the beneficiary. Because the insured does not personally own the policy or hold any "incidents of ownership," the death benefit is generally excluded from their gross estate.
How an ILIT Functions:
- Creation: You establish the trust and appoint a trustee (someone other than yourself).
- Funding: You transfer an existing policy to the trust or, ideally, the trust purchases a new policy.
- Crummey Powers: To pay premiums, you gift money to the trust. To ensure these gifts qualify for the annual gift tax exclusion ($18,000 per recipient in 2026), the trust must include "Crummey" powers. This gives beneficiaries a limited time to withdraw the gifted funds, satisfying the IRS "present interest" requirement.
- Distribution: Upon your death, the insurance company pays the death benefit to the trust. The trustee then distributes the funds to your heirs according to the trust's instructions, completely bypassing the probate process and the federal estate tax.
Benefits of an ILIT in 2026:
- Estate Tax Savings: Removes the entire death benefit from your taxable estate.
- Liquidity: Provides the estate with cash to pay other taxes or debts without selling off illiquid assets like real estate or a family business.
- Asset Protection: Because the trust is irrevocable, the policy's cash value and death benefit are generally protected from the creditors of the insured and the beneficiaries.
When the Estate is the Beneficiary: A Common Pitfall
Regardless of who owns the policy, the proceeds are always included in the taxable estate if they are payable to the estate of the decedent.
Naming "My Estate" as a beneficiary is rarely recommended. Not only does this subject the proceeds to federal and state estate taxes, but it also subjects the funds to the probate process. Probate can be time-consuming, expensive, and public. Furthermore, funds in the estate are vulnerable to creditors' claims before they can be distributed to heirs.
In 2026, with the lower exemption thresholds, naming the estate as a beneficiary is a costly mistake that can result in a 40% loss of the death benefit to federal taxes before a single dollar reaches the family.
State-Level Estate and Inheritance Tax Considerations
While federal law is uniform, state laws vary significantly. Even if your estate is below the $7 million federal threshold in 2026, you may still owe state-level taxes.
- Estate Tax: Several states (such as Massachusetts, Oregon, and Washington) have estate tax exemptions much lower than the federal level—sometimes as low as $1 million. In these states, life insurance inclusion can trigger a state tax bill even if no federal tax is due.
- Inheritance Tax: A few states (like Pennsylvania and New Jersey) levy an inheritance tax based on who receives the money. The relationship of the beneficiary to the deceased determines the tax rate.
It is vital to check the IRS state tax guidelines and consult with a local estate attorney to understand how your specific jurisdiction treats life insurance proceeds.
Summary of Life Insurance Tax Treatment in 2026
The following table summarizes the different tax treatments of life insurance proceeds based on ownership and beneficiary status in the current 2026 tax year.
| Policy Ownership | Beneficiary | Federal Income Tax | Federal Estate Tax |
|---|---|---|---|
| Insured Individually | Named Individual (e.g., Spouse) | Generally Exempt | Included in Gross Estate |
| Insured Individually | The Insured's Estate | Generally Exempt | Included in Gross Estate |
| Third Party (e.g., Adult Child) | The Third Party | Generally Exempt | Excluded from Gross Estate |
| Irrevocable Trust (ILIT) | The Trust | Generally Exempt | Excluded from Gross Estate |
| Employer (Group Term) | Named Individual | Generally Exempt | Included in Gross Estate* |
*Note: Group term life insurance provided by an employer is generally included in the employee's estate if the employee retains the right to name the beneficiary.
Frequently Asked Questions
1. If my spouse owns the policy on my life, is it included in my estate?
Generally, no. If your spouse is the owner and you have no incidents of ownership, the proceeds are excluded from your estate. However, if your spouse dies before you, the "cash value" or replacement cost of the policy will be included in their estate. Additionally, if the proceeds are paid to your spouse and they remain in your spouse’s estate until their later death, they may be taxed at that time.
2. Does the "Three-Year Rule" apply to new policies?
The Three-Year Rule (IRC Section 2035) typically applies when you transfer an existing policy. If an Irrevocable Life Insurance Trust (ILIT) or another individual applies for and purchases a new policy on your life from the start, the three-year clock usually does not apply because you never personally "owned" the policy to begin with.
3. What happens if the death benefit exceeds the $7 million exemption?
In 2026, if your gross estate (including life insurance) exceeds the roughly $7 million exemption, the excess is taxed at the federal estate tax rate, which is currently a top rate of 40%. For example, if your total estate is $8 million, the $1 million over the limit could result in a $400,000 tax bill.
4. Can I avoid the 40% tax by naming a charity as the beneficiary?
Yes. Life insurance proceeds paid directly to a qualified 501(c)(3) charitable organization are eligible for an estate tax charitable deduction. While the proceeds are technically "included" in the gross estate, they are "deducted" out, resulting in zero net estate tax on those specific funds.
5. How do I know if I have "incidents of ownership" on my current policy?
You must review the policy contract. Most individual term and permanent policies name the "Insured" as the "Owner." If the contract grants you the power to change beneficiaries or access cash value, you have incidents of ownership. You can verify this by looking at your most recent policy illustration or contacting your insurance carrier.
Practical Next Steps for 2026 Estate Planning
With the 2026 sunset of the higher exemption amounts, your first priority should be an asset audit. Calculate the total value of your assets, including the full face value of all life insurance policies (term, whole life, and group policies from work).
If your total estate value approaches or exceeds $7 million, consider the following actions:
- Consult a Tax Professional: Discuss the specific impact of the TCJA sunset on your holdings.
- Evaluate an ILIT: If you have significant life insurance, establishing an Irrevocable Life Insurance Trust can immediately remove those proceeds from your taxable estate, provided you navigate the three-year rule or purchase a new policy through the trust.
- Review Beneficiary Designations: Ensure your estate is not the named beneficiary. Update your primary and contingent beneficiaries to reflect your current wishes and tax strategy.
- Coordinate with State Laws: Ensure your plan accounts for lower state-level estate tax thresholds, which may be more restrictive than federal law.
Life insurance is a powerful tool for family protection, but without proper structuring in 2026, a large portion of that protection could be diverted to the IRS. Proactive ownership management is the only way to ensure the full benefit reaches your intended heirs.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
