
UFI auto insurance coverage—commonly referring to Uninsured and Underinsured Motorist (UM/UIM) coverage within first-party auto policies—protects drivers, passengers, and vehicle owners against financial losses caused by drivers who carry no insurance, inadequate liability limits, or who flee the scene of an accident. It covers medical bills, lost wages, and vehicle repairs depending on specific policy endorsements.
Auto insurance contracts contain various technical terms, acronyms, and coverage tiers designed to shield vehicle owners from unexpected liabilities. Among these, UFI auto insurance coverage (often categorized alongside Uninsured/Underinsured Motorist provisions or carrier-specific first-party protection terms) plays a critical role in complete financial risk management.
While baseline liability coverage protects other drivers when you are at fault, UFI coverage flips this relationship: it acts as your personal safety net when another party is at fault but lacks the insurance necessary to cover your damages.
Understanding how UFI auto insurance functions, what specific scenarios it applies to, and the key policy considerations required when structuring your endorsement ensures you remain fully protected without paying for redundant coverage.
Disclaimer: Auto insurance regulations, policy definitions, and statutory mandates vary by jurisdiction. This article provides educational guidance and should not replace professional financial or legal counsel.
Understanding UFI Auto Insurance Coverage
To evaluate UFI coverage effectively, policyholders must understand how first-party and third-party insurance claims interact following a motor vehicle collision.
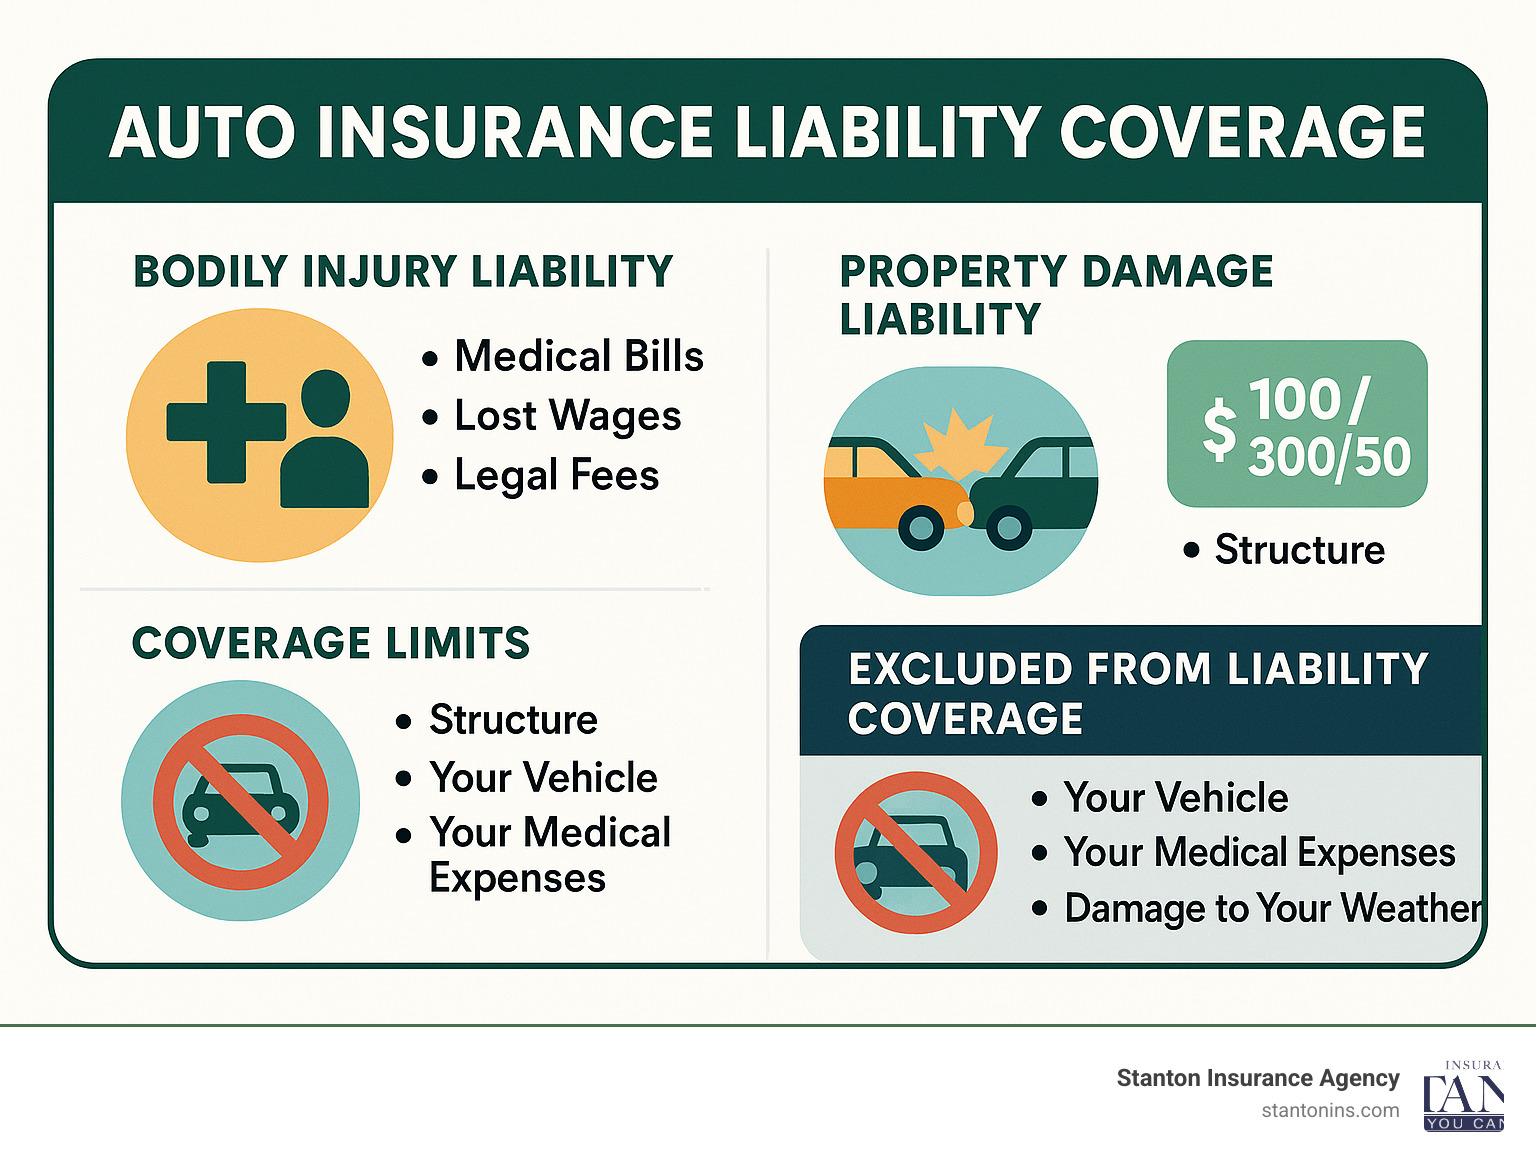
When an auto accident occurs, liability insurance operates on a third-party structure. The driver who caused the crash relies on their liability policy to pay for the victim's bodily injuries and property damage. However, millions of vehicles operate on public roads without active insurance policies or with minimum statutory limits that fail to cover modern medical costs and vehicle replacement values.
- Accident Occurs (At-Fault Driver Has No/Insufficient Coverage)
- At-Fault Driver's Policy (Depleted, Non-Existent, or Hit-and-Run)
- Your UFI Insurance Policy (Steps in to pay Bodily Injury & Property Damage)
UFI auto insurance coverage steps into the shoes of the uninsured or underinsured driver's missing policy. Instead of pursuing an underfunded individual through lengthy court proceedings, your own insurer compensates you directly up to the policy limits specified in your declarations page.
Dominant Scenarios Covered by UFI Provisions
- Uninsured At-Fault Drivers: The driver responsible for the collision carries no auto insurance policy whatsoever.
- Underinsured At-Fault Drivers: The responsible driver carries insurance, but their bodily injury or property damage limits are lower than the total costs resulting from your injuries or damage.
- Hit-and-Run Accidents: The responsible driver flees the scene and cannot be identified, leaving no third-party policy to file against.
- Pedestrian or Cyclist Incidents: Many UFI policies extend bodily injury coverage to policyholders and family members if struck by an uninsured vehicle while walking or cycling.
Core Components of UFI Coverage
UFI coverage typically divides into two distinct operational components: Bodily Injury (UFI-BI) and Property Damage (UFI-PD). Each component serves a different purpose and operates under separate limit caps.
1. UFI Bodily Injury (UFI-BI)
UFI Bodily Injury coverage compensates you and passengers in your vehicle for physical injuries sustained in a crash caused by an uninsured or underinsured driver.
- Medical Expenses: Hospital stays, emergency care, surgeries, physical therapy, and ongoing rehabilitation.
- Lost Income: Wages lost during recovery and future loss of earning capacity if permanent disability occurs.
- Pain and Suffering: Non-economic damages recognized under tort law, reimbursing physical discomfort and emotional distress resulting from severe injuries.
- Funeral Expenses: Compensation provided to surviving family members in the event of a fatal collision.
2. UFI Property Damage (UFI-PD)
UFI Property Damage coverage pays for physical damage to your insured vehicle and select personal items inside the car when an uninsured driver is at fault.
- Vehicle Repair or Replacement: Actual cash value compensation or repair costs up to the chosen policy limit.
- Rental Car Allowance: Coverage for temporary rental transportation while your primary vehicle undergoes repair (when included in policy terms).
- Personal Belongings: Replacement costs for damaged personal equipment, such as child car seats or laptops inside the vehicle at the time of impact.

Key Considerations When Selecting UFI Limits and Terms
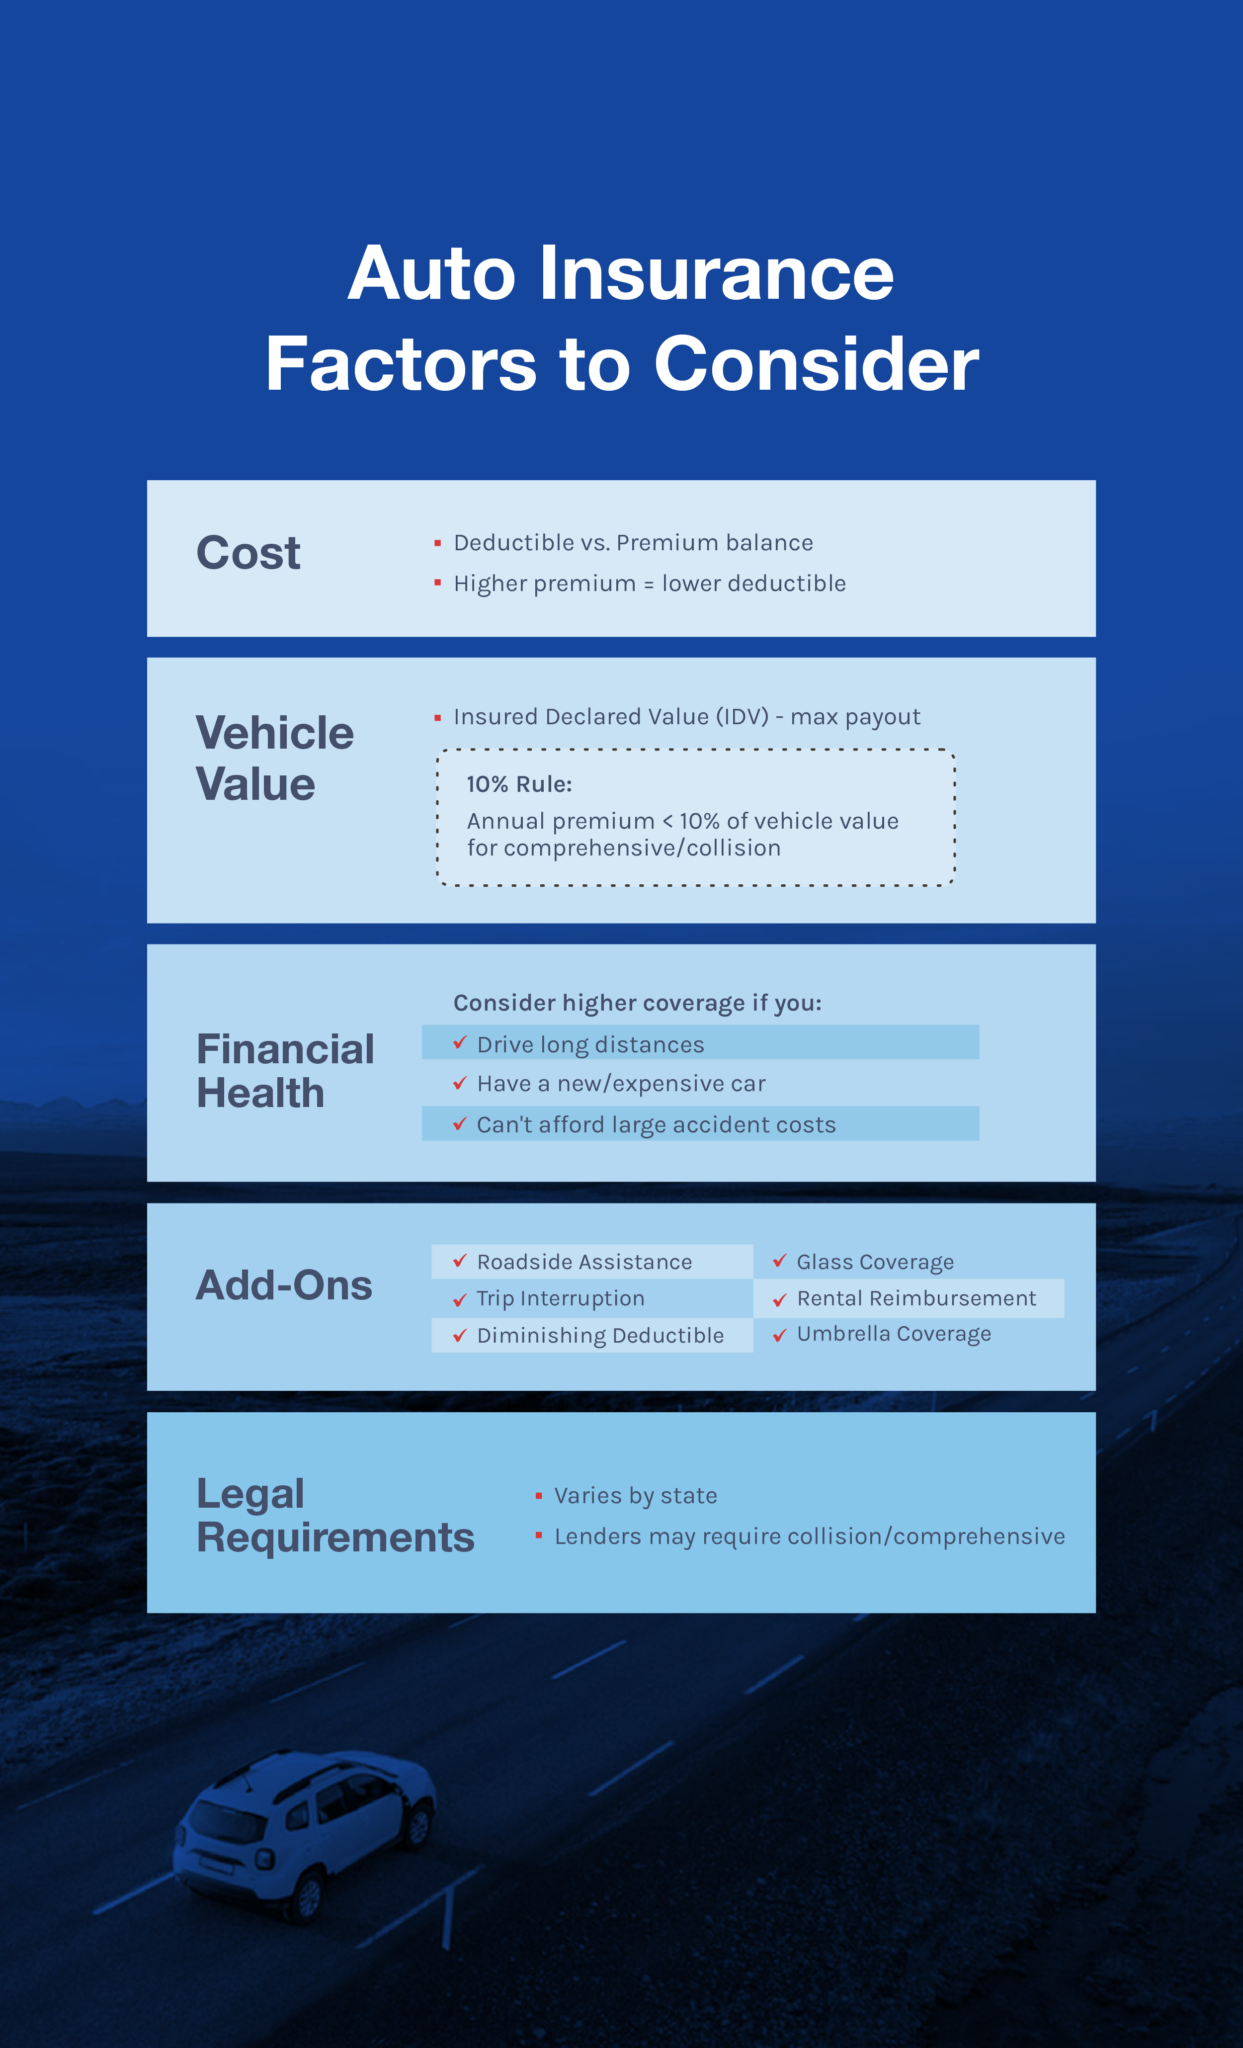
Choosing the right UFI coverage parameters requires balancing individual risk tolerance, existing health coverage, and budget constraints. Policyholders should carefully evaluate several critical structural considerations before finalizing their auto policy.
Matching Liability Limits
In most insurance jurisdictions, insurers do not allow policyholders to purchase UFI limits higher than their standard third-party liability limits. For example, if your policy carries $100,000/$300,000 in Bodily Injury Liability (meaning $100,000 per person and $300,000 per accident), your UFI-BI maximum limit will typically top out at $100,000/$300,000.
Carrying high third-party liability without matching UFI limits creates a critical imbalance: you protect others from your mistakes while leaving yourself exposed to theirs.
Stacked vs. Unstacked UFI Coverage
In states and jurisdictions where stacking is permitted, policyholders who insure multiple vehicles can combine (or "stack") coverage limits across policies or vehicles under a single policy.
- Stacked Coverage: Multiplies your UFI coverage limits by the number of vehicles insured on your policy. If you carry $50,000 in UFI-BI on two separate vehicles, your total available limit for a single accident becomes $100,000.
- Unstacked Coverage: Limits available coverage to the specified limit of the vehicle involved in the accident, regardless of how many vehicles are listed on the policy contract.
While stacked coverage increases policy premiums slightly, it significantly enhances financial protection for households owning two or more automobiles.
Deductibles and Property Damage Interplay
UFI Property Damage coverage often features a lower deductible (typically $100 to $250) compared to standard Collision coverage (which often ranges from $500 to $1,000). Furthermore, in some states, UFI-PD waives the deductible entirely if the uninsured driver is positively identified by law enforcement.
However, if you already maintain comprehensive Collision coverage on a vehicle, adding UFI-PD may provide overlapping benefit except for the reduced deductible. Policyholders should evaluate whether collision coverage already handles property losses sufficiently.
Regulatory Framework and State Mandates
Auto insurance regulation operates primarily at the state level. Consequently, the legal obligations surrounding UFI and uninsured motorist coverage vary significantly depending on where your vehicle is registered.
- Jurisdictional Legal Rules
- Mandatory States: Required by law for all policyholders
- Mandatory-Offer States: Insurers must offer; requires written waiver
- Mandatory UFI States: Several states mandate that all licensed drivers carry minimum levels of UFI bodily injury coverage. Policies issued in these states automatically incorporate baseline limits into standard quotes.
- Mandatory-Offer States: In many jurisdictions, state statutes require insurance companies to offer UFI coverage equal to your liability limits, but permit policyholders to decline or lower the coverage by signing a formal written rejection form.
- No-Fault / PIP States: In states operating under Personal Injury Protection (PIP) or no-fault frameworks, your medical costs are initially paid by your PIP policy regardless of who caused the crash. UFI coverage comes into play once severe injury thresholds exceed PIP limits.
To review official state-by-state auto insurance requirements and consumer protection standards, consult the National Association of Insurance Commissioners (NAIC).
Comparing UFI to Related Auto Insurance Provisions
Understanding where UFI coverage fits into an overall auto policy requires comparing it directly against other standard coverage types.
| Coverage Type | Primary Purpose | Pays For Whom? | Deductible Applicable? | Requires At-Fault Uninsured Party? |
|---|---|---|---|---|
| UFI / UM / UIM | Protects against uninsured/underinsured driver fault | Named insured & vehicle passengers | Minimal or waived in many states | Yes |
| Bodily Injury Liability | Protects other drivers when you cause harm | Third-party victims | No | No (You are at fault) |
| Collision Coverage | Pays for physical vehicle damage from crashes | Named insured's vehicle repair | Standard deductible ($250–$1,000+) | No (Applies regardless of fault) |
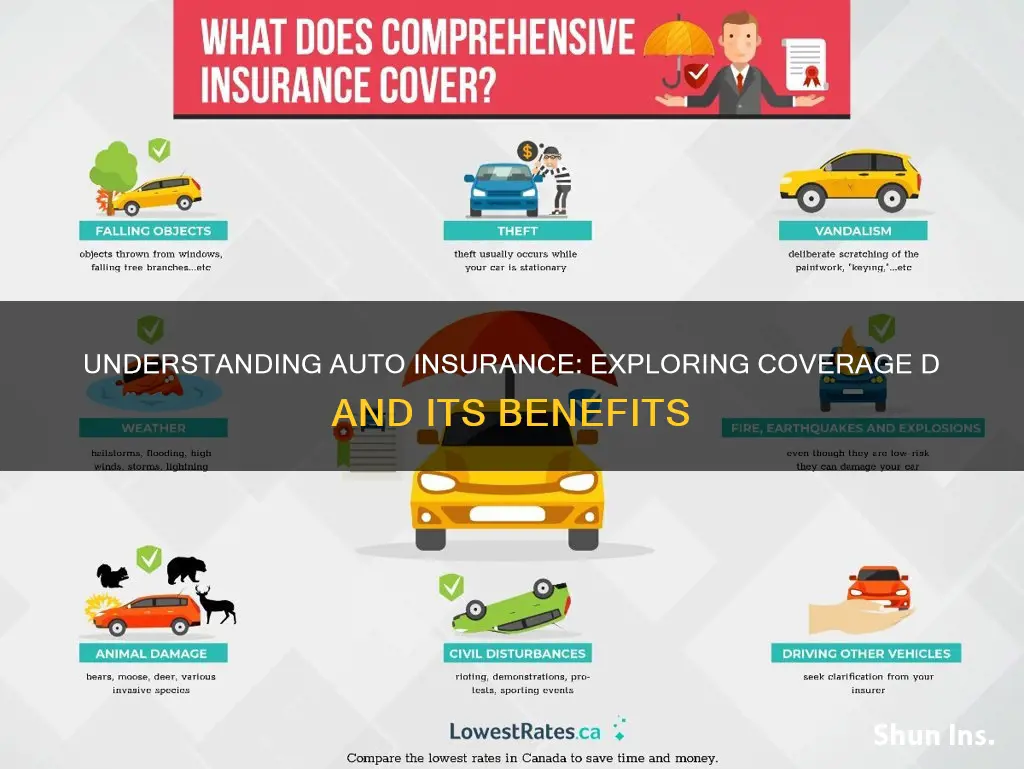
| Comprehensive | Pays for non-collision events (weather, theft, vandalism) | Named insured's vehicle replacement | Standard deductible | No |
| Personal Injury Protection (PIP) | Covers immediate medical bills & lost wages | Named insured & passengers | Minimal or zero depending on policy | No (Fault-neutral coverage) |
Navigating a UFI Claim: Steps and Best Practices
Filing a UFI claim requires establishing two distinct elements: first, that the other driver was legally at fault for the accident, and second, that the driver either lacked insurance or carried insufficient coverage.
- Step 1: Document Scene & Obtain Police Report
- Step 2: Notify Insurer & Confirm At-Fault Status
- Step 3: Document Injuries, Repairs & Out-of-Pocket Costs
- Step 4: Insurer Evaluates Claim & Issues Settlement
- Step 5: Subrogation (Insurer Pursues At-Fault Driver)
Step 1: Secure Comprehensive Scene Documentation
- Call law enforcement immediately to file an official accident report. A police report serves as foundational evidence confirming hit-and-run status or lack of valid insurance credentials from the opposing driver.
- Take photos of vehicle positioning, tire marks, property damage, weather conditions, and visible injuries.
- Gather contact details from neutral eyewitnesses.
Step 2: Formally Notify Your Insurance Carrier
Report the collision to your insurance provider as soon as practical. Explicitly state that you are initiating a claim under your UFI / Uninsured Motorist provision.
Step 3: Verify Insurance Status of the At-Fault Driver
Your insurance adjuster will perform a database check to confirm whether the responsible driver had active insurance coverage at the exact time of impact. If the opposing carrier formally denies coverage or confirms policy lapse, your UFI provision activates.
Step 4: Medical Documentation and Settlement Negotiation
Submit all itemized medical invoices, treatment plans, physician notes, and proof of wage loss to your adjuster. Because UFI claims place you in an adversarial position with your own insurer regarding claim valuation, maintaining detailed, clean medical records is essential for securing fair compensation.
Step 5: Subrogation Rights
Once your insurance company pays your UFI settlement, it inherits your right to sue the at-fault driver individually through a legal process known as subrogation. The carrier may pursue the uninsured driver directly to recover the money paid to you.
Cost Analysis and Value Evaluation
Because UFI coverage represents relatively low financial risk for insurers compared to primary collision coverage, adding UFI to an auto insurance policy is typically very cost-effective.
- Average Cost: For most drivers, adding UFI Bodily Injury and Property Damage coverage costs between $40 and $150 per year per vehicle, depending on geographic location and baseline coverage limits.
- High-Risk Geographies: In urban regions or states with higher rates of uninsured motorists, UFI premiums may run higher. According to research from the Insurance Information Institute, uninsured driver rates vary significantly across regions, making UFI coverage essential in high-uninsured jurisdictions.
When Is UFI Most Value-Critical?
- High-Deductible Health Plans (HDHPs): If your private health insurance features a high annual deductible or strict out-of-network limitations, UFI-BI shields you from unexpected out-of-pocket medical debt following a serious collision.
- Sole Wage Earners: If your household depends entirely on your ability to work, UFI's lost-wage reimbursement safeguards income stability while you recover.
- Older Vehicles Without Collision Coverage: Owners of older vehicles who drop full-coverage Collision to lower costs often retain UFI-PD. This ensures that if an uninsured driver destroys their vehicle, they retain partial financial protection without paying expensive full-collision premiums.
Common Pitfalls and Coverage Mistakes
Failing to structure your auto insurance policy correctly can lead to surprising coverage gaps during a claim. Avoid these common errors:
- Rejecting UFI to Save Minimal Premium: Waiving UFI coverage to reduce a monthly bill by a few dollars exposes drivers to devastating financial loss if struck by an uninsured or underinsured motorist.
- Selecting Minimum Statutory Limits: Purchasing minimum UFI limits (e.g., $25,000 per person) may prove drastically insufficient if emergency medical care, surgery, or intensive therapy is required.
- Failing to Report Hit-and-Run Incidents Promptly: Most UFI policies mandate that hit-and-run accidents be reported to police within 24 to 72 hours to prevent fraudulent claims. Delayed reporting can jeopardize coverage eligibility.
- Assuming Health Insurance Covers Everything: While health insurance pays medical bills, it does not compensate for lost income, pain and suffering, or car repair deductibles.
Frequently Asked Questions
Does UFI auto insurance cover hit-and-run damage?
Yes. Most UFI bodily injury policies cover injuries caused by unidentified hit-and-run drivers. However, UFI property damage coverage for hit-and-run vehicle repairs varies by state; some jurisdictions require physical contact or driver identification before UFI-PD applies.
Will filing a UFI claim increase my auto insurance rates?
In most states, insurance companies are legally prohibited from surcharging premiums or raising rates for claims filed under UFI coverage if you were entirely not at fault for the accident.
What is the difference between UM and UIM coverage?
Uninsured Motorist (UM) coverage applies when the at-fault driver has no auto insurance at all or flees the scene. Underinsured Motorist (UIM) coverage kicks in when the at-fault driver has insurance, but their policy limits are too low to cover your total damages. Many insurers package UM and UIM into a unified UFI coverage endorsement.
If I have good health insurance, do I still need UFI coverage?
Yes. Health insurance only covers medical costs—it does not pay for lost income, ongoing disability accommodations, pain and suffering, or vehicle property repairs. Furthermore, health insurance policies often carry high co-pays and deductibles that UFI can reimburse.
Can I stack UFI coverage across multiple vehicles?
If your state law and insurance carrier permit stacking, you can combine UFI limits across multiple vehicles on your policy. This increases your total available coverage ceiling in exchange for a modest premium increase.
Practical Recommendation and Next Steps
Evaluating your UFI auto insurance coverage is one of the most effective steps you can take to protect your household's financial health.
- Review Your Current Declarations Page: Locate your auto insurance policy document and verify whether Uninsured/Underinsured Motorist (UFI/UM/UIM) coverage is active.
- Align UFI Limits with Liability Limits: Ensure your UFI bodily injury limits match your overall liability limits (for example, $100,000/$300,000 or higher).
- Evaluate Your Health and Disability Coverage: If your health policy has high deductibles or limited income replacement, maximize your UFI bodily injury coverage to fill potential financial gaps.
- Consult Your Provider: Contact your insurance representative to review state-specific stacking options, UFI property damage deductibles, and hit-and-run reporting requirements.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
