Comprehensive List of Workers Compensation Insurance Companies in Virginia (2026)

In Virginia, businesses with two or more employees are legally required to carry workers' compensation insurance. As of 2026, the state remains a competitive "voluntary market," meaning employers can choose from hundreds of private insurance carriers, including national leaders like Travelers, The Hartford, and Liberty Mutual, as well as regional specialists like Erie Insurance and Builders Mutual.
Virginia’s workers' compensation landscape is governed by the Virginia Workers' Compensation Commission (VWC). Because Virginia does not operate a monopolistic state fund, the market is highly diverse, offering business owners various options based on their industry, risk profile, and payroll size. Selecting the right carrier involves more than just comparing premiums; it requires evaluating claims handling efficiency, loss control services, and financial stability ratings.
Virginia Workers' Compensation Requirements in 2026
Before diving into the specific list of companies, it is crucial to understand the regulatory environment in Virginia. As of 2026, the mandate remains clear: any employer who regularly employs two or more employees (including part-time workers, corporate officers, and managers) must provide workers' compensation coverage.
The "two-employee rule" is one of the strictest in the Mid-Atlantic region. Even if your employees are family members or temporary help, they count toward this threshold. Failure to carry insurance can lead to significant civil penalties, often calculated based on the duration of non-compliance, and can lead to the employer being held personally liable for medical expenses and lost wages in the event of a workplace injury.
The Role of the Virginia Workers' Compensation Commission (VWC)
The VWC does not sell insurance. Instead, it acts as a judicial and administrative body that oversees the processing of claims and ensures that employers are complying with the law. When you select a company from the list below, that company must be licensed by the Virginia State Corporation Commission (SCC) Bureau of Insurance and report its coverage data to the VWC.
Top National Workers' Compensation Carriers in Virginia
National carriers often provide the most robust digital tools and the largest networks of occupational health providers. Here are the leading private insurers currently active in the Virginia market.
1. Travelers Insurance
Travelers remains the largest writer of workers' compensation insurance in the United States and maintains a significant footprint in Virginia. They are often favored by mid-to-large-sized corporations due to their sophisticated "TravComp" claims management system. In 2026, Travelers continues to emphasize data-driven safety programs that help Virginia employers reduce their Experience Modification Factor (E-Mod).
2. The Hartford
Specializing in small-to-mid-sized businesses, The Hartford is a primary choice for retail, professional services, and healthcare providers in Virginia. Their integration with payroll providers like ADP and Paychex allows for "Pay-as-you-go" billing, which is highly beneficial for Virginia startups and seasonal businesses (such as those in the Virginia Beach tourism sector) looking to manage cash flow.
3. Liberty Mutual
Liberty Mutual is a dominant force for industrial and manufacturing risks. With Virginia’s growing logistics and distribution hubs along the I-81 corridor, Liberty Mutual provides specialized loss-control engineering services designed to minimize repetitive motion injuries and warehouse accidents.
4. Berkshire Hathaway GUARD
GUARD Insurance Group (a Berkshire Hathaway company) has expanded its appetite in Virginia significantly over the last few years. They are particularly competitive for "main street" businesses—restaurants, auto repair shops, and small offices—that require bundled packages (BOP) alongside their workers' compensation.
5. Chubb
For high-end professional firms or companies with international operations based in Northern Virginia, Chubb offers premium concierge-level claims service. While their premiums may be higher, their focus on complex litigation management and high-limit coverage makes them a staple for the tech and defense contracting sectors in Fairfax and Arlington.
Regional and Niche Insurers in Virginia
Sometimes, a regional carrier understands the local legal climate and medical landscape better than a national giant. These companies often offer more personalized service to Virginia employers.
Erie Insurance
Erie is a powerhouse in the Mid-Atlantic. Many Virginia business owners prefer Erie because they operate exclusively through independent agents. Their "Erie Custom Business Insurance" often ranks highest in customer satisfaction for the region. They are an excellent fit for contractors and local service providers who want a local agent they can call directly.
Builders Mutual
If you are in the construction industry in Virginia—whether a general contractor in Richmond or a specialist in Norfolk—Builders Mutual is often the benchmark. Because they focus exclusively on the building industry, their risk management programs are tailored to job site safety, OSHA compliance, and the specific nuances of Virginia’s construction statutes.
Amerisafe
Amerisafe focuses on "high-hazard" industries. If your Virginia business involves logging, heavy trucking, or roof work, many standard carriers might decline the risk. Amerisafe specializes in these dangerous classes, offering intensive safety training and specialized medical case management for severe injuries.
Comparison of Leading Virginia Workers' Comp Providers
The following table summarizes the key attributes of the most prominent carriers in Virginia for the 2026 policy year.
| Insurance Carrier | A.M. Best Rating | Target Industry | Key Strength in VA |
|---|---|---|---|
| Travelers | A++ (Superior) | General/Mixed | Advanced data analytics & scale |
| The Hartford | A+ (Superior) | Small Business/Retail | Seamless payroll integration |
| Erie Insurance | A+ (Superior) | Contractors/Local Shops | Local agent service & stability |
| Builders Mutual | A (Excellent) | Construction/Trades | Industry-specific safety experts |
| Berkshire GUARD | A+ (Superior) | Restaurants/Offices | Competitive pricing for small firms |
| Liberty Mutual | A (Excellent) | Manufacturing/Logistics | Complex risk & loss control |
| Amerisafe | A (Excellent) | High-Hazard/Logging | Expertise in dangerous industries |
The Virginia Residual Market: NCCI Assigned Risk
Not every business can find coverage in the "voluntary market." If your Virginia business has a high claims history or operates in an extremely high-risk industry, private carriers may refuse to issue a policy.
In this scenario, you will be placed in the Virginia Assigned Risk Pool. This market is managed by the National Council on Compensation Insurance (NCCI).
- How it works: NCCI assigns your business to a "servicing carrier" (which could be one of the major companies like Travelers or Liberty Mutual).
- Cost: Premiums in the assigned risk market are generally higher than in the voluntary market because they include a "residual market burden" or surcharge.
- Goal: The goal for any employer in this pool should be to improve their safety record over 1–3 years to eventually qualify for lower-cost coverage in the voluntary market.
How Workers' Comp Premiums Are Calculated in VA
To choose the best company from the list, you must understand how they arrive at your quote. In 2026, Virginia uses a standard formula:
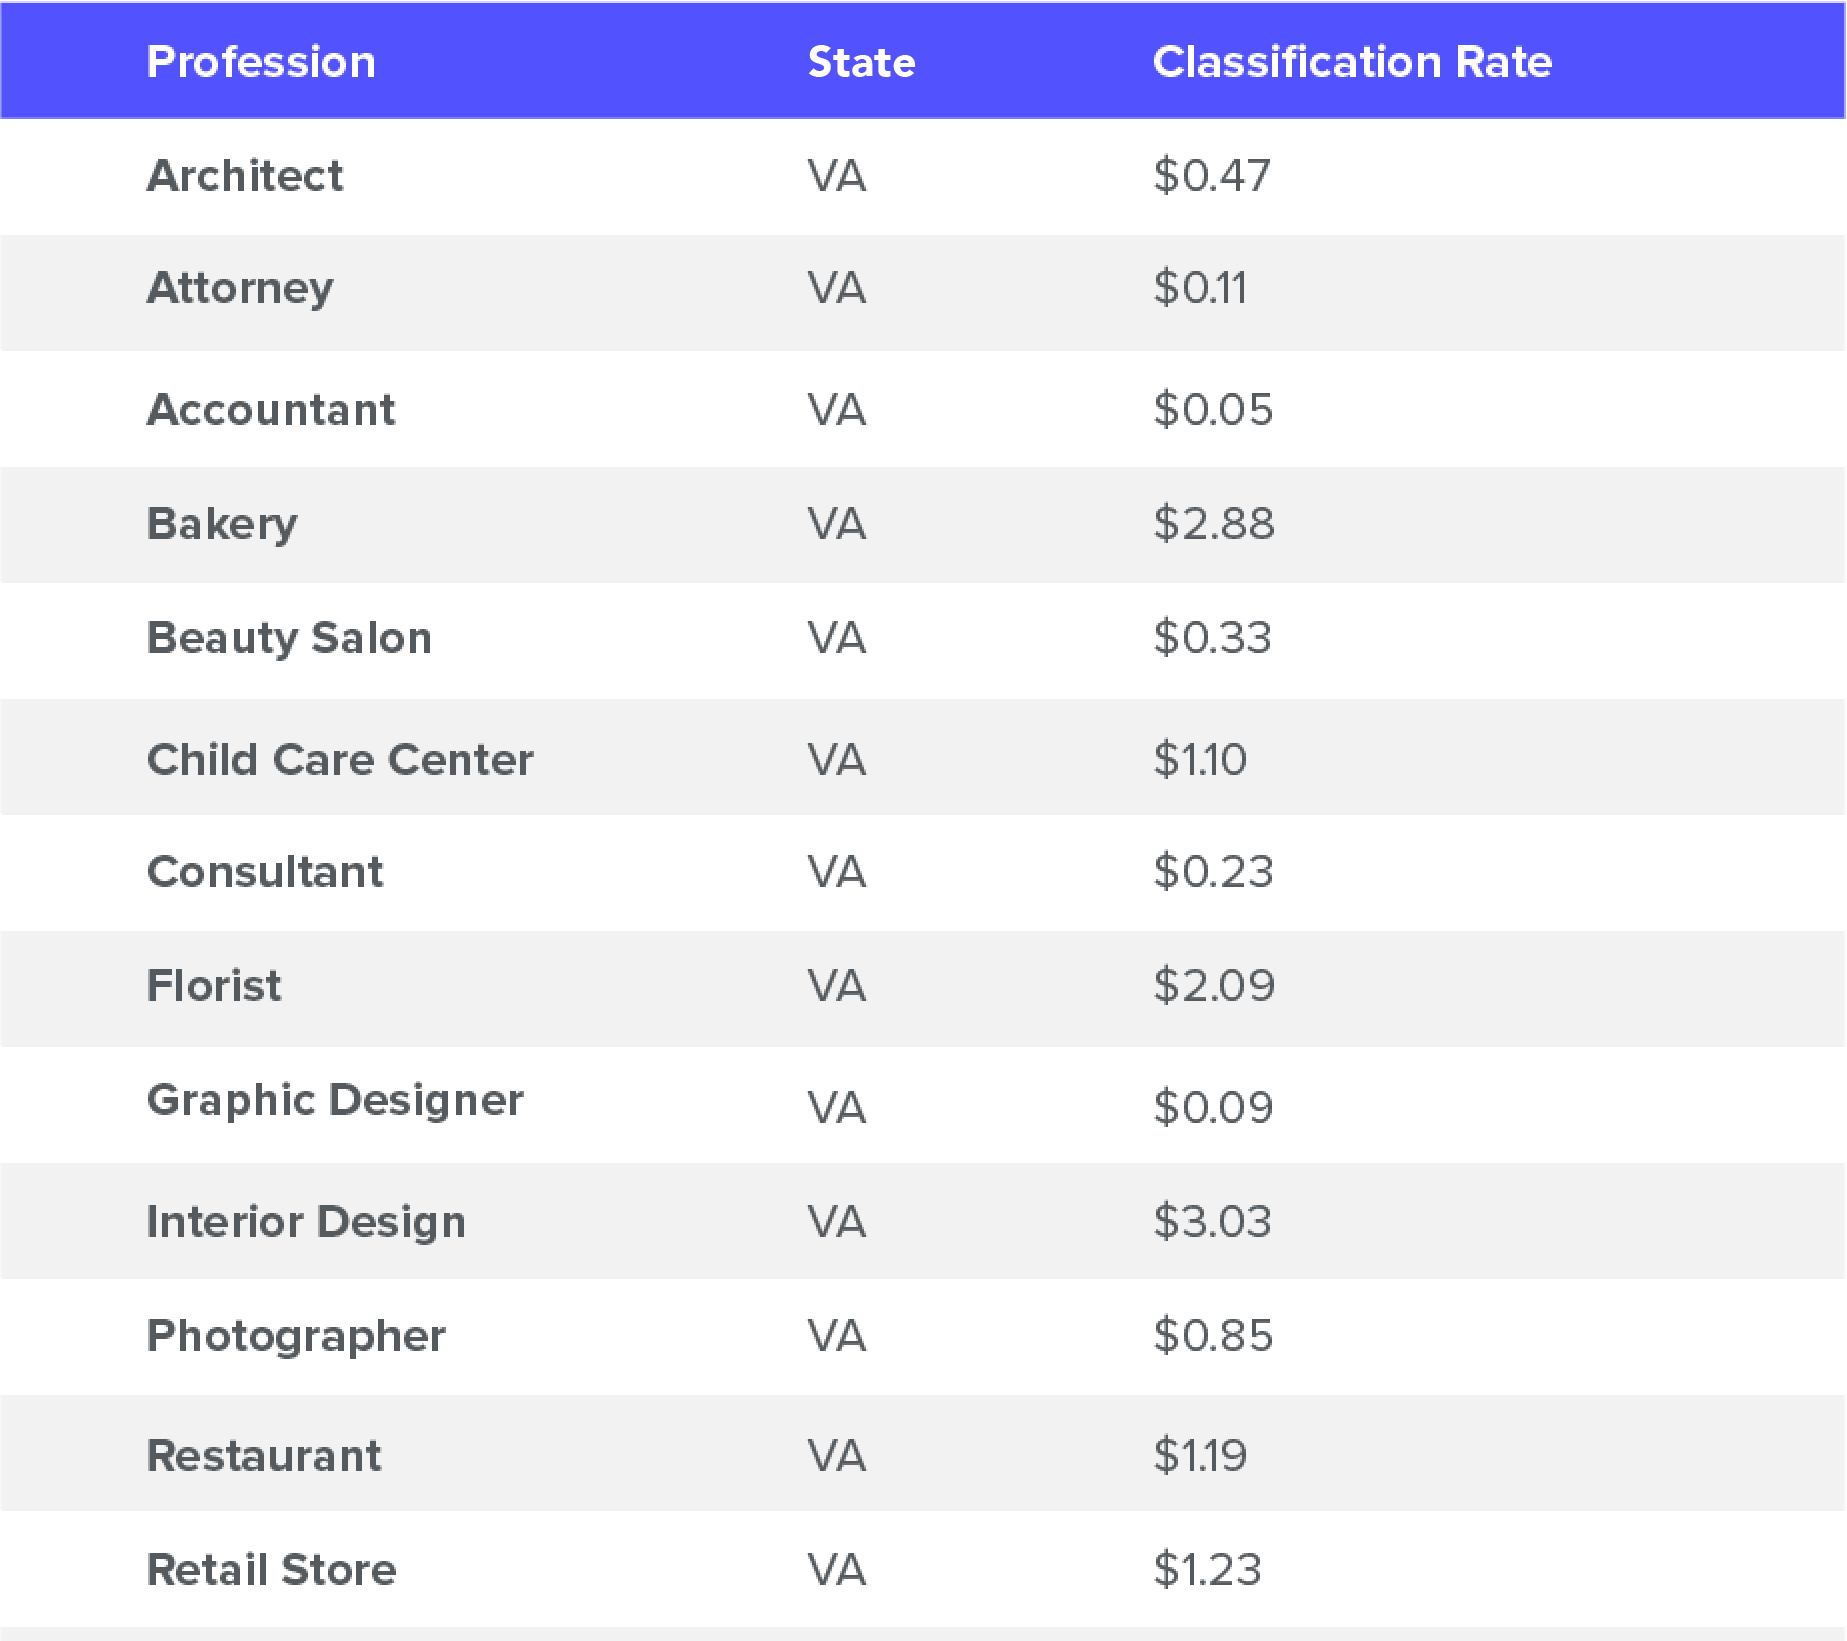
[Classification Code Rate] x [Payroll / 100] x [Experience Modifier] = Base Premium
- Classification Codes: Every job in Virginia is assigned a four-digit NCCI code (e.g., 8810 for clerical office employees). Each code has a specific rate based on the risk of that job.
- Payroll: You pay a rate per $100 of your annual gross payroll. Accurate forecasting is essential to avoid large audit bills at the end of the year.
- Experience Modifier (E-Mod): This is your company’s individual "credit score." If you have fewer accidents than the average business of your size in Virginia, your E-Mod will be below 1.0, earning you a discount. If you have more accidents, your E-Mod will rise above 1.0, increasing your premium.
How to Verify a Company's Status in Virginia
Before signing a policy, you should verify that the carrier is officially authorized to write workers' compensation in the Commonwealth. You can do this through two primary methods:
- Virginia Bureau of Insurance: Visit the State Corporation Commission (SCC) website to search for licensed insurance companies.
- VWC Verification Tool: The Virginia Workers' Compensation Commission provides an online "Insurance Search" tool. This is primarily used by employees to see if their employer is covered, but it can also be used to verify that a carrier's filings are active and recognized by the state.
Common Pitfalls to Avoid When Selecting a Carrier
Choosing the cheapest list price isn't always the smartest move for Virginia employers. Consider these factors:
Ignoring the Audit Process
Many Virginia businesses are surprised by a "Premium Audit" at the end of the policy year. Companies like The Hartford or Travelers have very streamlined digital audits, whereas smaller or older carriers might still require physical paperwork. Choose a carrier whose audit process matches your administrative capabilities.
Misclassifying Subcontractors
Virginia law is very specific about "statutory employees." If you hire a subcontractor who does not have their own workers' compensation insurance, the VWC may deem them your employee. Your insurance company will then charge you a premium for that subcontractor’s payroll during the audit. Ensure your carrier provides clear guidance on collecting Certificates of Insurance (COI) from your subs.
Overlooking Claims Advocacy
In Virginia, workers' compensation is a "no-fault" system, but claims can still be contested if an injury didn't happen "in the course of employment." Carriers with strong local legal representation in Richmond, Roanoke, and Norfolk can save you thousands in fraudulent or non-compensable claims.
Frequently Asked Questions
Can I buy workers' comp from a state fund in Virginia?
No. Virginia does not have a state-operated insurance fund like West Virginia or Maryland used to have. You must purchase coverage from a private insurance company or apply for the Assigned Risk Pool if you are denied by private carriers.
Is workers' comp required for a one-person LLC in Virginia?
Generally, no. If you are a sole proprietor or a single-member LLC with no other employees, you are not required to carry workers' compensation for yourself. However, many Virginia general contractors will require you to have a policy anyway before they let you onto a job site. In this case, you can purchase a "Minimum Premium Policy" (often called a "Ghost Policy").
What happens if I have two employees but don't buy insurance?
The Virginia Workers' Compensation Commission can assess a civil penalty of up to $250 per day for each day you are uninsured, capped at a maximum of $50,000. Additionally, if an employee is injured while you are uninsured, you are responsible for all medical costs and can be sued in civil court.
How do I switch insurance companies in Virginia?
You can switch carriers at the end of your policy term (usually one year). To do so, you should provide a "Loss Run Report" from your current carrier to your new agent. This report shows your 3-to-5-year claims history, which is required for an accurate quote from a new company.
Does Virginia allow group self-insurance?
Yes. Certain trade associations in Virginia (like the Virginia Municipal League or various automotive associations) operate group self-insurance pools. These allow members of the same industry to pool their premiums and risks. This is often a viable alternative to traditional insurance companies for established businesses with good safety records.
Practical Recommendation for Virginia Business Owners
For 2026, the best strategy for securing workers' compensation in Virginia is to work with an independent insurance agent who has access to multiple carriers from the list above.
- If you are a small retail or office-based business, prioritize The Hartford or Berkshire Hathaway GUARD for their ease of use and "Pay-as-you-go" options.
- If you are a contractor, look first at Erie Insurance for the price or Builders Mutual for industry-specific protection.
- If you have a complex or high-risk operation, focus on Travelers or Liberty Mutual, as their loss-control engineering can help lower your premiums over time by preventing accidents before they occur.
Always verify that your chosen carrier is reporting your coverage to the VWC to ensure you remain in legal compliance and avoid unnecessary state audits or fines.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
