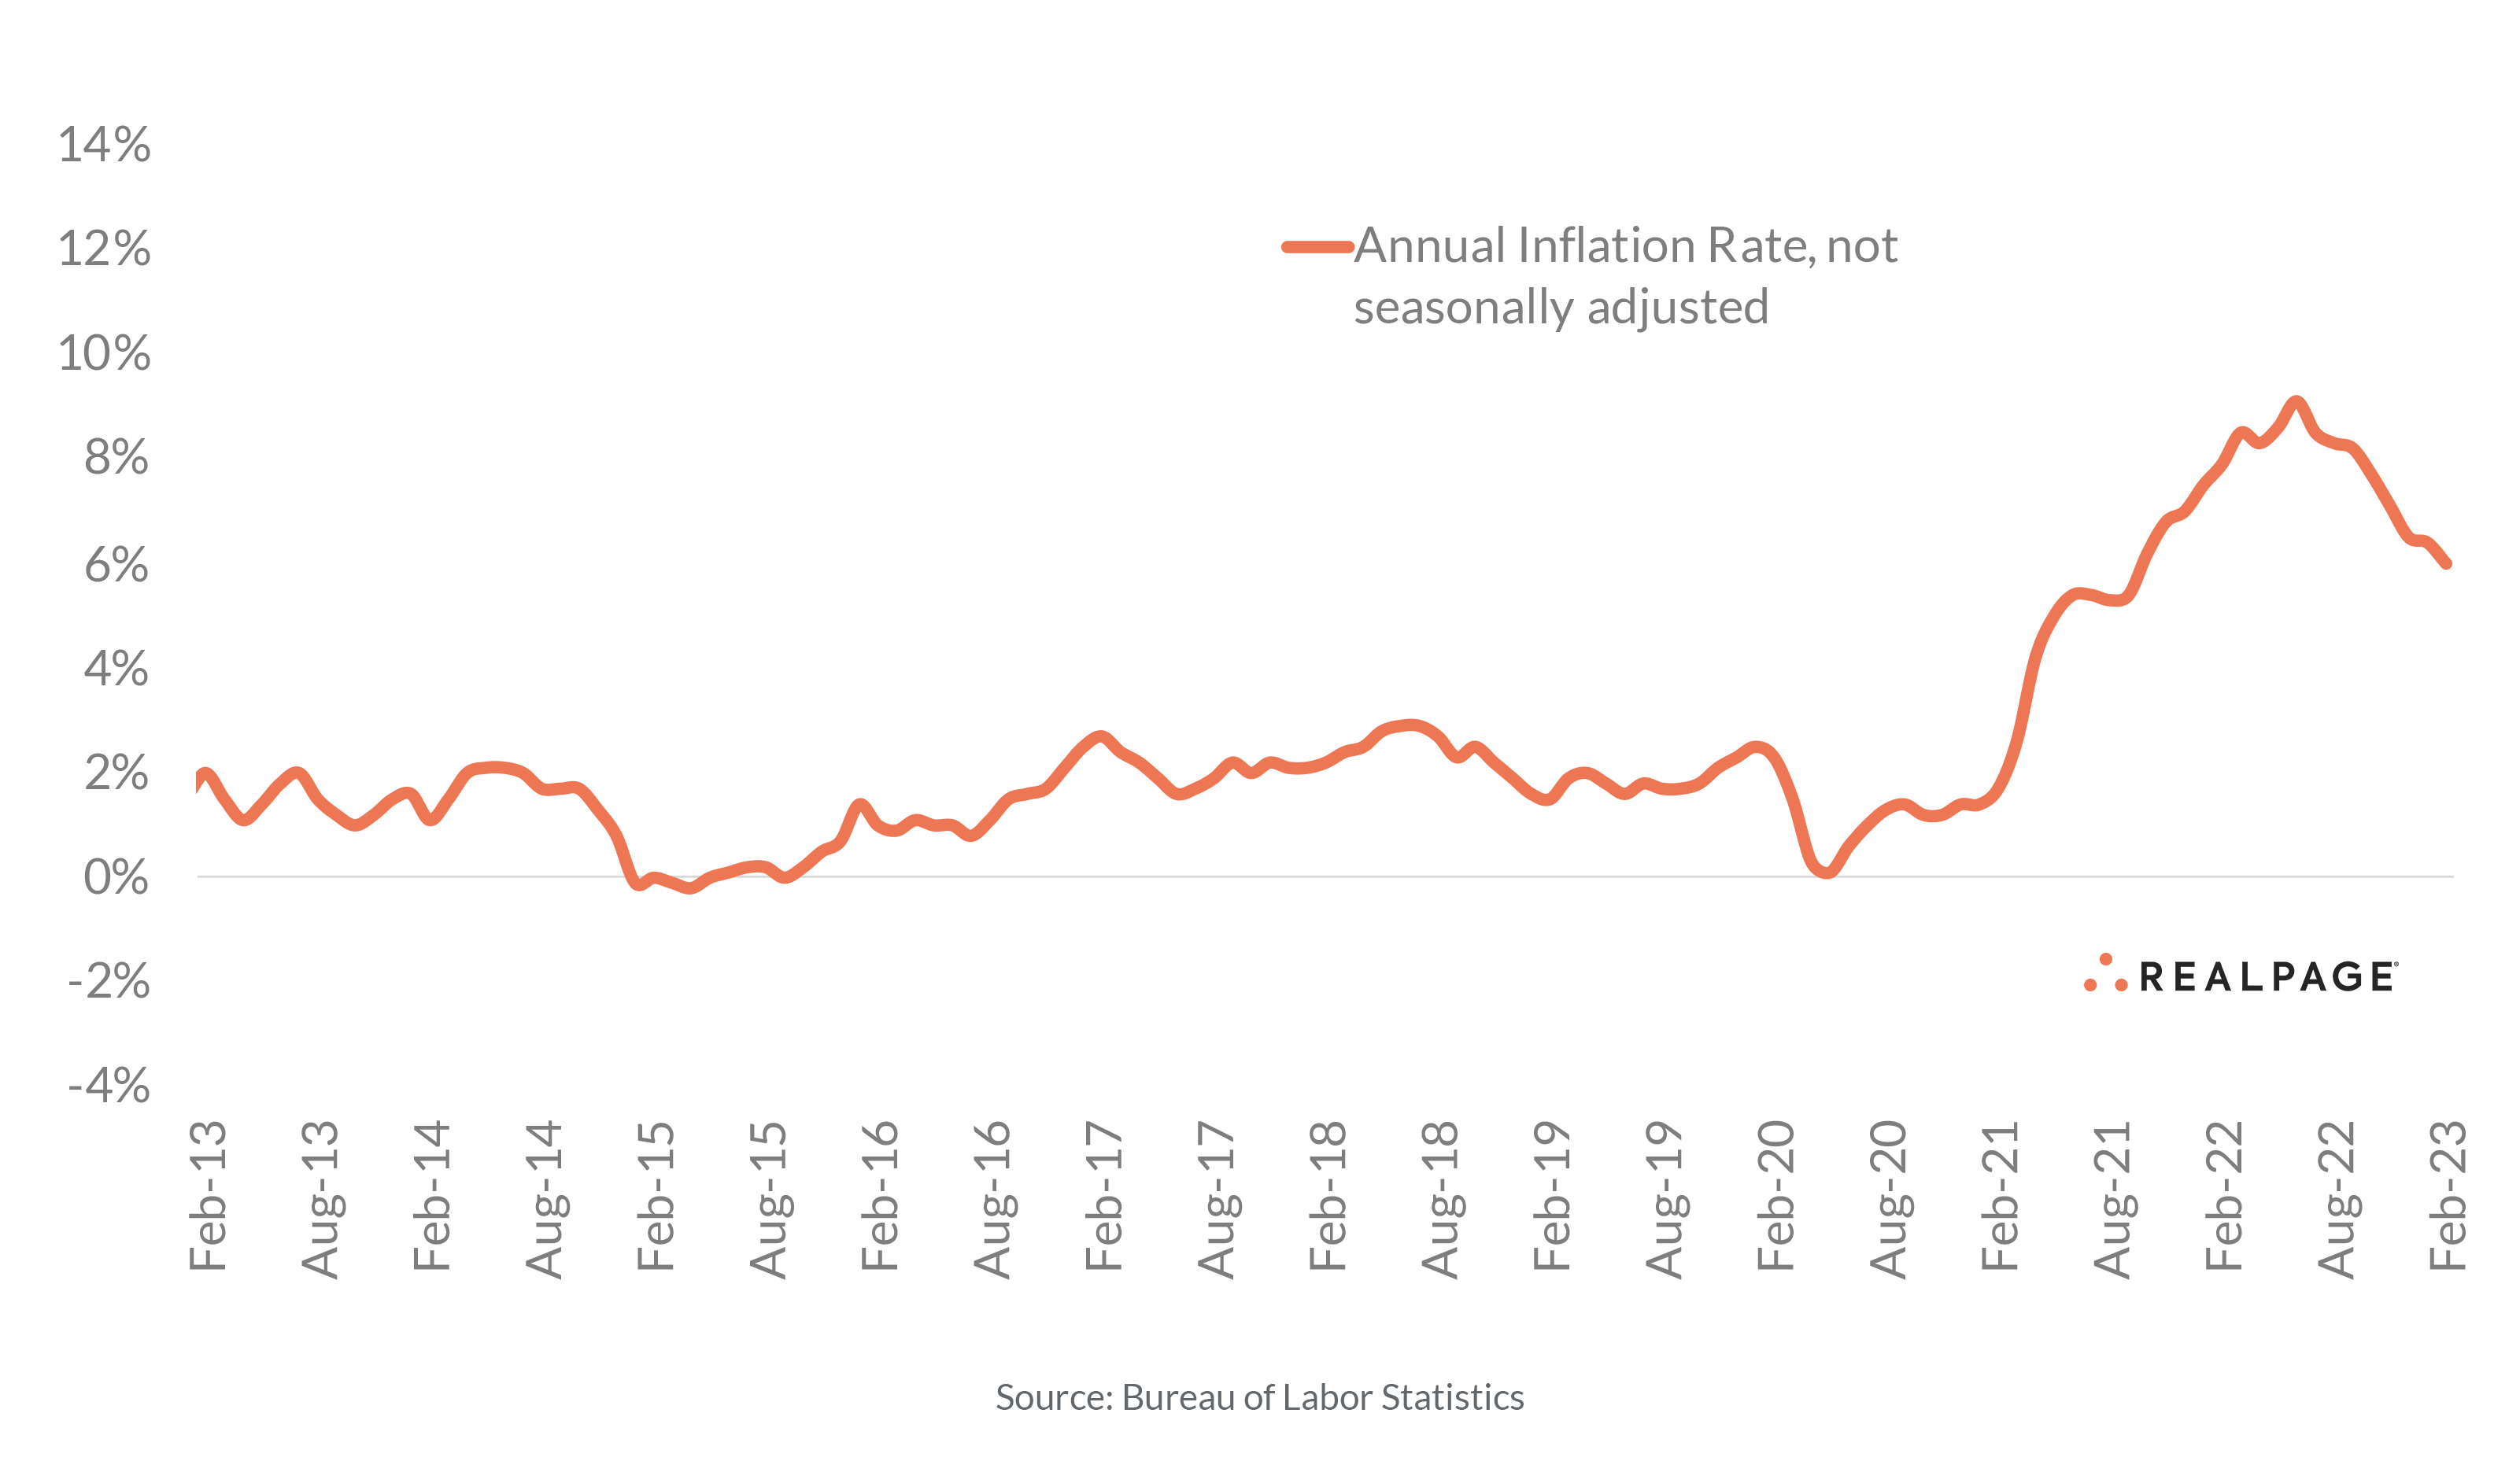
The inflation rate trend over the last three years (2023–2025) has transitioned from a period of extreme post-pandemic volatility to a phase of stabilization and eventual normalization. After peaking in mid-2022, inflation decelerated through 2023, faced persistent "stickiness" in service sectors during 2024, and finally converged toward the Federal Reserve's 2% target by the close of 2025.
The global economy has undergone a significant transformation since the start of 2023. At that time, central banks were locked in a fierce battle against the highest inflation seen in four decades. As we look back from the vantage point of 2026, the trajectory of the consumer price index (CPI) reflects a complex interplay between aggressive monetary policy, the untangling of global supply chains, and shifting consumer behavior. Understanding this three-year journey requires analyzing not just the raw numbers, but the underlying economic forces that dictated the pace of price changes across goods, services, and housing.
The Macroeconomic Context: From Peak to Pivot
To understand the last three years, one must acknowledge the starting point. In late 2022, inflation was the primary concern for households and policymakers alike. The surge was initially sparked by a "perfect storm": unprecedented fiscal stimulus, supply chain bottlenecks caused by the COVID-19 pandemic, and a massive energy price shock following the invasion of Ukraine.
By the beginning of 2023, the Federal Reserve and other global central banks had already begun one of the fastest interest-rate-hiking cycles in history. This set the stage for the disinflationary trend that defined 2023. However, the path was never linear. The economy faced repeated questions about whether a "soft landing"—reducing inflation without triggering a recession—was actually possible.
The last three years have proven that while the "easy" part of disinflation happened quickly as energy prices stabilized, the "last mile" of reaching 2% was fraught with structural challenges, particularly in the labor market and the housing sector.
2023: The Year of Rapid Disinflation and Supply Chain Recovery
In 2023, the primary narrative was the rapid retreat of headline inflation. At the start of the year, the annual inflation rate in the United States was still hovering above 6%. By December 2023, it had fallen to approximately 3.4%.
The Role of Energy and Commodities
The most significant contributor to the 2023 cooldown was the normalization of energy markets. After the 2022 price spikes, oil and natural gas prices moderated significantly. This had a cascading effect on the economy, lowering transportation costs for goods and reducing utility bills for households. According to data from the U.S. Bureau of Labor Statistics (BLS), the energy index saw several months of year-over-year declines in 2023, acting as a powerful brake on the overall CPI.
Supply Chain Normalization
The logistical nightmares of 2021 and 2022 finally resolved in 2023. The "Global Supply Chain Pressure Index" returned to historical norms, meaning that goods—ranging from used cars to electronics—were no longer in short supply. This led to "goods deflation," where the prices of physical items actually began to drop in some categories, helping to offset the rising costs of services.
Monetary Policy Impact
The Federal Reserve continued to raise the federal funds rate in the first half of 2023, reaching a peak range of 5.25% to 5.50% in July. These high borrowing costs began to bite into the economy, slowing down big-ticket purchases and cooling the feverish pace of business investment. The market transitioned from fearing "hyper-inflation" to debating when the Fed would finally stop hiking.
2024: The "Last Mile" and Sticky Service Inflation
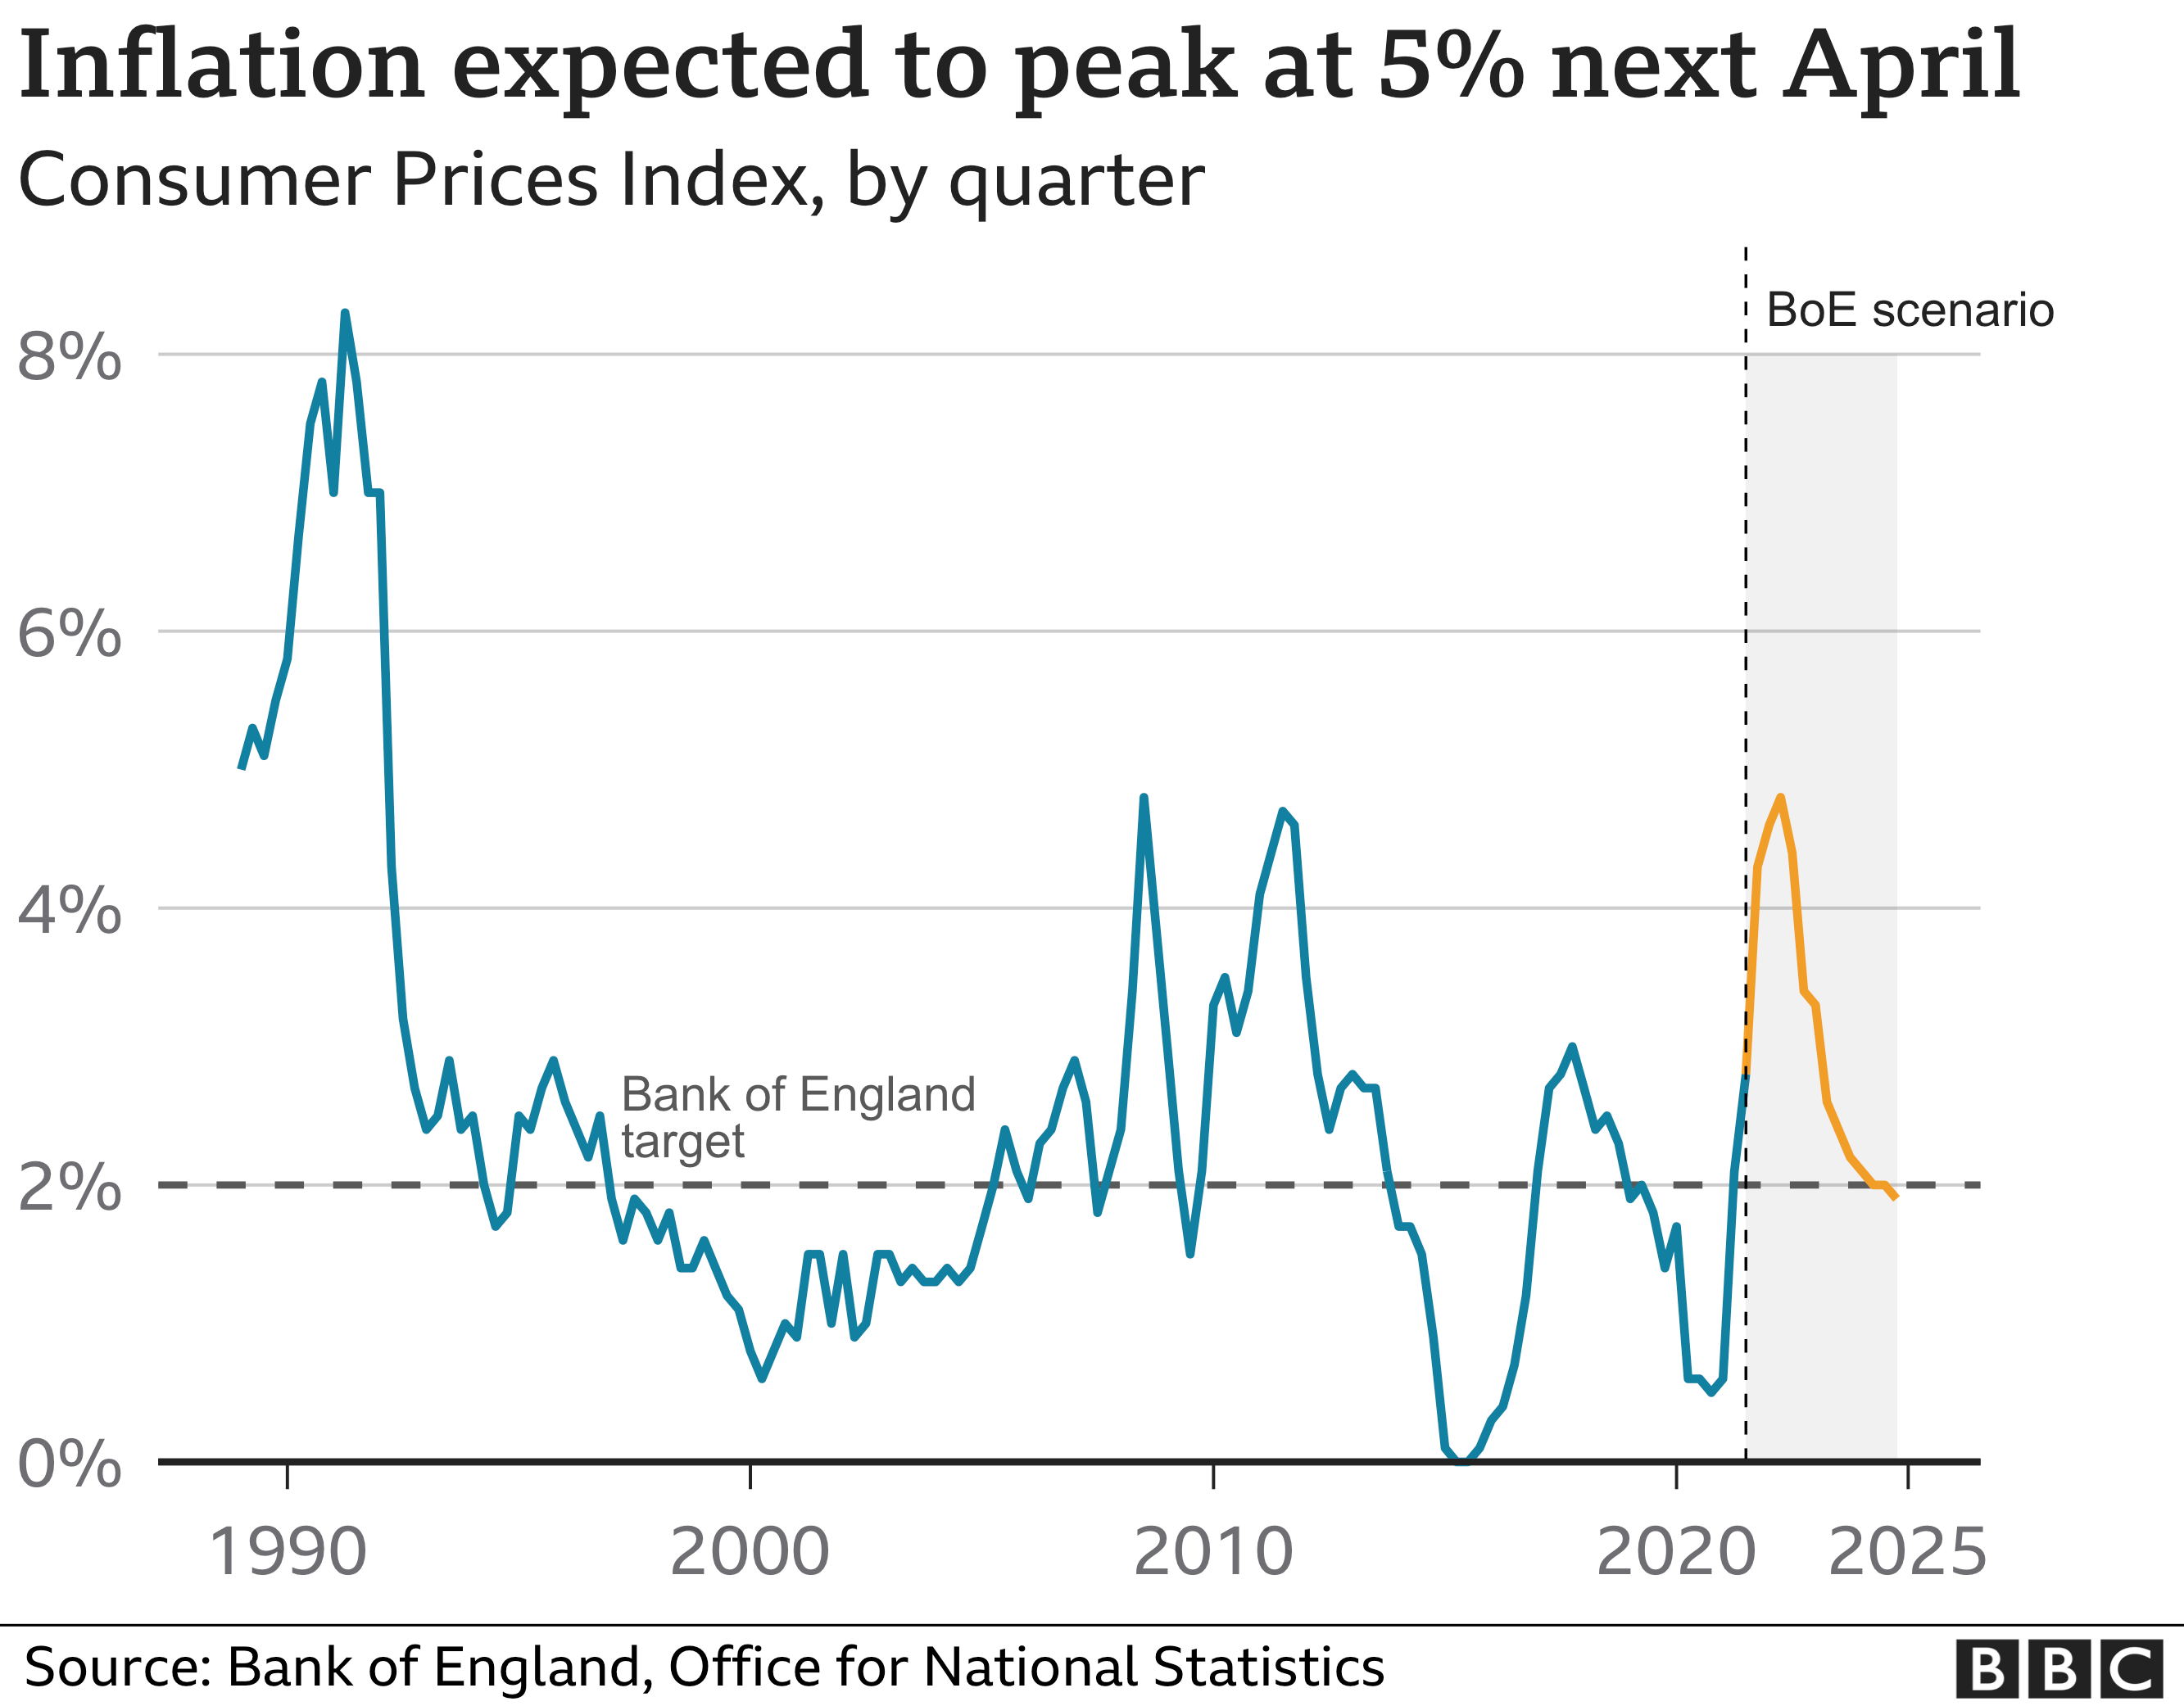
If 2023 was the year of rapid progress, 2024 was the year of frustration for those hoping for a quick return to 2%. Inflation proved to be "sticky," lingering in the 3.0% to 3.5% range for much of the first half of the year.
The Problem with Services
While the prices of goods were stable or falling, the cost of services continued to climb. This was driven largely by labor costs. With the unemployment rate remaining historically low throughout 2024, workers maintained significant bargaining power. Wage growth, while cooling from its 2022 peaks, remained above 4%, which businesses passed on to consumers in sectors like healthcare, car insurance, and personal services.
Shelter Inflation: The Lagging Giant
Shelter (rent and homeowners' equivalent rent) accounts for about one-third of the total CPI. In 2024, shelter inflation remained stubbornly high. This was largely due to the way the BLS measures housing; it takes months for new, lower rental market rates to show up in the official data because of how often leases are renewed. Throughout 2024, this "lagged" shelter data kept the headline inflation rate higher than many economists expected, even as the real-time housing market was cooling.
The "Higher for Longer" Era
Because inflation did not fall as fast as hoped in early 2024, the Federal Reserve maintained interest rates at their restrictive peak for longer than anticipated. This "higher for longer" stance was designed to ensure that inflation expectations did not become unanchored. It wasn't until late 2024 that the Fed finally saw enough evidence of cooling to begin a cautious cycle of interest rate cuts.
2025: Reaching the Target and the New Normal
As we entered 2025, the persistence pays off. The cumulative effect of high interest rates finally fully permeated the economy, and the lagged effects of housing costs finally began to dissipate in the official reports.
Convergence to 2%
By mid-2025, headline inflation finally touched the 2.1% mark, representing a functional return to the Federal Reserve’s long-term target. This was achieved without a major spike in unemployment, a feat that many economists in 2023 had thought impossible. The "soft landing" was officially declared a success by most major financial institutions, including the International Monetary Fund (IMF).
The Shift in Drivers
In 2025, the drivers of inflation shifted from "scarcity" to "productivity." With supply chains optimized and the labor market reaching a better balance between supply and demand, price increases became more predictable. Businesses could no longer rely on broad "inflationary cover" to raise prices, as consumer price sensitivity returned to pre-pandemic levels.
The Federal Reserve's Pivot
With inflation under control, 2025 saw a series of deliberate rate cuts. These were not emergency measures, but rather "recalibration" cuts intended to bring interest rates back to a "neutral" level—one that neither stimulates nor restricts growth. By the end of 2025, the economy had settled into a steady state, though at a higher price floor than existed before the 2021 surge.
Comparative Trends: 2023–2025 Data Summary
The following table summarizes the key inflationary metrics and the federal funds rate throughout this three-year period.
| Metric | 2023 (Annual Avg) | 2024 (Annual Avg) | 2025 (Annual Avg) |
|---|---|---|---|
| Headline CPI (YoY) | 4.1% | 3.2% | 2.2% |
| Core CPI (Excl. Food/Energy) | 4.8% | 3.6% | 2.4% |
| Federal Funds Rate (Peak) | 5.50% | 5.50% | 4.50% (Ending) |
| Primary Inflation Driver | Energy & Supply Chains | Shelter & Service Wages | Policy Lag & Normalization |
| Real Wage Growth | Positive (Late 2023) | Moderate | Stable |
Note: Data for 2025 reflects year-end estimates and finalized reporting cycles as of early 2026.
Key Economic Concepts Explained
To truly grasp why the trend followed this path, it is essential to define the mechanisms at play.
Disinflation vs. Deflation
A common misconception during the last three years was the difference between disinflation and deflation.
- Disinflation is a decrease in the rate of inflation. This is what occurred from 2023 to 2025. Prices were still rising, but they were rising more slowly.
- Deflation is a broad-based decrease in prices. Aside from specific categories like used cars or gasoline, the overall economy did not experience deflation. Consumers often felt frustrated because they expected prices to return to 2019 levels; however, the goal of central banks was merely to stop them from rising so fast.
Core vs. Headline Inflation
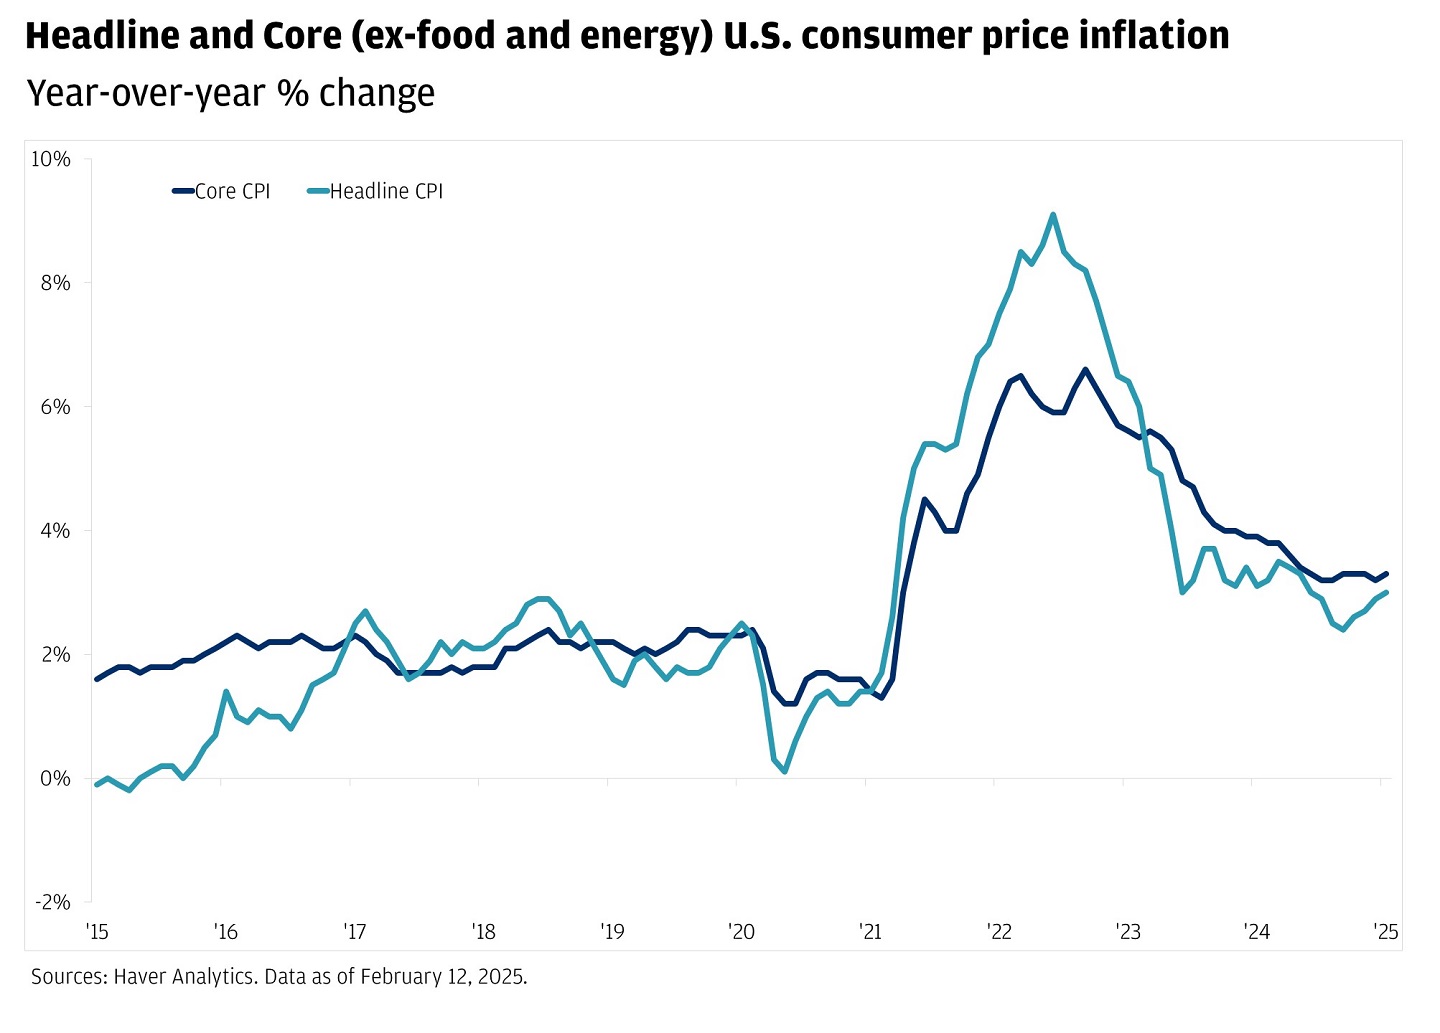
Economists frequently distinguish between "Headline CPI" (which includes everything) and "Core CPI" (which excludes volatile food and energy prices). Over the last three years, Headline inflation was often lower than Core inflation because energy prices were falling. Policymakers focus on Core inflation because it is a better predictor of long-term trends and is less susceptible to temporary shocks like a sudden change in oil production.
The Wealth Effect and Consumer Spending
Despite high prices, consumer spending remained remarkably resilient throughout 2023 and 2024. This was partly due to the "wealth effect"—rising home values and a strong stock market made people feel wealthier, leading them to continue spending even as their "real" (inflation-adjusted) income growth was modest.
Sector-Specific Analysis: How Different Industries Fared
The "headline" number often masks the reality of different sectors. The experience of the last three years varied wildly depending on where you spent your money.
The Housing Market Paradox
The housing sector was perhaps the most unusual part of the 2023–2025 trend. While the Fed raised rates to cool the economy, this actually created a "lock-in effect." Homeowners with 3% mortgages were unwilling to sell and move into a 7% mortgage. This restricted the supply of homes, keeping prices high even as demand fell. It wasn't until rates began to decline in 2025 that housing inventory began to normalize, finally easing the upward pressure on shelter costs.
Food and Groceries
Food inflation was a major political and social issue in 2023. While the rate of increase slowed down, "sticky" prices in the grocery aisle persisted. This was due to a combination of high fertilizer costs, avian flu impacting poultry prices, and increased processing and packaging costs. By 2025, food inflation had largely settled into a 2% annual increase, though the cumulative price increase since 2021 remained a significant burden for low-income households.
The Travel and Leisure Boom
The post-pandemic "revenge travel" phase lasted longer than many expected, continuing well into 2024. Airfares and hotel rates saw significant volatility, often diverging from the general inflation trend as demand for experiences remained high despite rising costs. This sector was one of the last to see price stabilization.
Strategies for Managing Purchasing Power in 2026
As we navigate the current economic landscape of 2026, the lessons of the last three years offer a roadmap for financial stability.
- Debt Management: With interest rates having peaked and now on a downward or stable trajectory, 2026 is an opportune time to evaluate high-interest debt. Refinancing options that were unavailable in 2023 and 2024 are becoming more viable.
- Investment Allocation: The transition from high inflation to stability changes the "winning" asset classes. While cash and short-term bonds were attractive in 2023-2024 (yielding 5%+), 2026 favors a return to balanced portfolios as the "real" return on bonds becomes more predictable.
- Cost-of-Living Awareness: While the inflation rate has stabilized, the price level is significantly higher than five years ago. Budgeting must account for the fact that a 2% increase on a $100 item is more impactful than 2% on an $80 item.
Frequently Asked Questions
Why did it take three years for inflation to get back to 2%?
Inflation is "sticky," meaning that once prices and wages start rising, they tend to stay in a cycle. It took time for the Federal Reserve's interest rate hikes to discourage spending and for the lagged effects of housing and labor contracts to reset. Furthermore, the "last mile" from 3% to 2% is historically the most difficult because it requires cooling the labor market without causing a collapse.
Did the 2023-2025 inflation trend lead to a recession?
Contrary to many 2022 forecasts, the U.S. avoided a formal recession during this period. The economy achieved a "soft landing," characterized by slowing growth and cooling inflation while maintaining a healthy labor market. This was largely attributed to the excess savings consumers held post-pandemic and the underlying strength of the American workforce.
What was the biggest factor in lowering inflation?
While monetary policy (interest rates) played a massive role, the single biggest factor in the initial drop from 9% to 4% was the resolution of global supply chain disruptions and the stabilization of energy prices. The subsequent drop from 4% to 2% was driven primarily by the Fed's restrictive interest rate environment and the eventual cooling of the service sector.
How did the labor market affect inflation during this time?
The labor market was a "double-edged sword." On one hand, high employment kept the economy from crashing. On the other hand, a shortage of workers led to higher wages, which contributed to "wage-price persistence" in the service sector through 2024. Inflation only fully stabilized once the supply of workers (helped by increased labor force participation) better matched the demand from employers.
Is the inflation we saw permanent?
Inflation measures the change in prices, not the level of prices. While the rate of inflation has returned to normal (2%), the price increases that occurred between 2021 and 2024 are generally permanent. Deflation (prices going back down) is rare and often associated with severe economic depressions, which central banks work hard to avoid.
Final Recommendation: A Forward-Looking Approach
For individuals and businesses in 2026, the primary goal should be to shift from a "crisis mindset" to a "stability mindset." The era of extreme price shocks is largely behind us, but the global economy remains sensitive to geopolitical shifts and energy transitions. Maintaining a diversified investment strategy and staying informed through official sources like the Federal Reserve Board remains the best defense against future economic fluctuations. It is advisable to review long-term financial plans to ensure they are calibrated for a 2-2.5% inflation environment rather than the low-inflation decade that preceded 2020.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, investment, or legal advice. Economic conditions are subject to change, and historical trends do not guarantee future results. Consult with a qualified financial advisor before making significant financial decisions.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
