To get multiple auto insurance quotes online, you should use a combination of comparison engines and direct insurer websites. By entering your vehicle's VIN, your driving history, and desired coverage limits into a reputable comparison platform, you can view several preliminary rates simultaneously. For the most accurate final pricing in 2026, verify these figures by visiting the top two or three individual carrier sites directly.
Obtaining multiple quotes is the most effective strategy for reducing your annual premiums. Because each insurance company utilizes a proprietary algorithm to assess risk, the price for the exact same driver can vary by hundreds of dollars across different providers. In 2026, the integration of real-time data and telematics has made this process faster, yet more complex. Navigating this landscape requires a structured approach to ensure you are comparing equivalent coverage levels and not just the lowest price point.
Essential Preparation for Online Quoting
Before you begin inputting data into various web portals, you must gather specific documentation. Inaccurate information is the leading cause of "premium shock," where the final price at the checkout screen is significantly higher than the initial quote. Insurance companies verify your data through third-party reports, such as the Comprehensive Loss Underwriting Exchange (CLUE) and motor vehicle records (MVRs).
Vehicle Information
You will need the Vehicle Identification Number (VIN) for every car you intend to insure. While some sites allow you to search by year, make, and model, the VIN provides the insurer with exact details regarding the car's safety features, trim level, and anti-theft devices. In 2026, safety tech such as advanced driver-assistance systems (ADAS) significantly influences collision coverage costs, making VIN-level accuracy mandatory for a valid quote.
Driver History and Details
Be prepared to provide the full legal name, date of birth, and driver’s license number for all household members of driving age. You must also disclose any accidents or moving violations from the past three to five years. Even if a violation was minor, failing to report it will result in an adjusted—and likely higher—quote once the insurer runs your official MVR.
Current Policy Declarations
Locate your current insurance "Declarations Page." This document outlines your existing coverage limits, such as bodily injury liability, property damage, and your deductibles. Having this on hand allows you to perform an "apples-to-apples" comparison. Without it, you may inadvertently quote a policy with lower protection levels, giving the illusion of savings while increasing your financial risk.
Using Online Comparison Tools (Aggregators)
Online comparison tools, often called aggregators, are the most efficient starting point. These platforms have evolved significantly by 2026, utilizing direct API links to insurance carriers to provide more accurate, "soft-pull" credit-based quotes without affecting your credit score.
How Aggregators Work
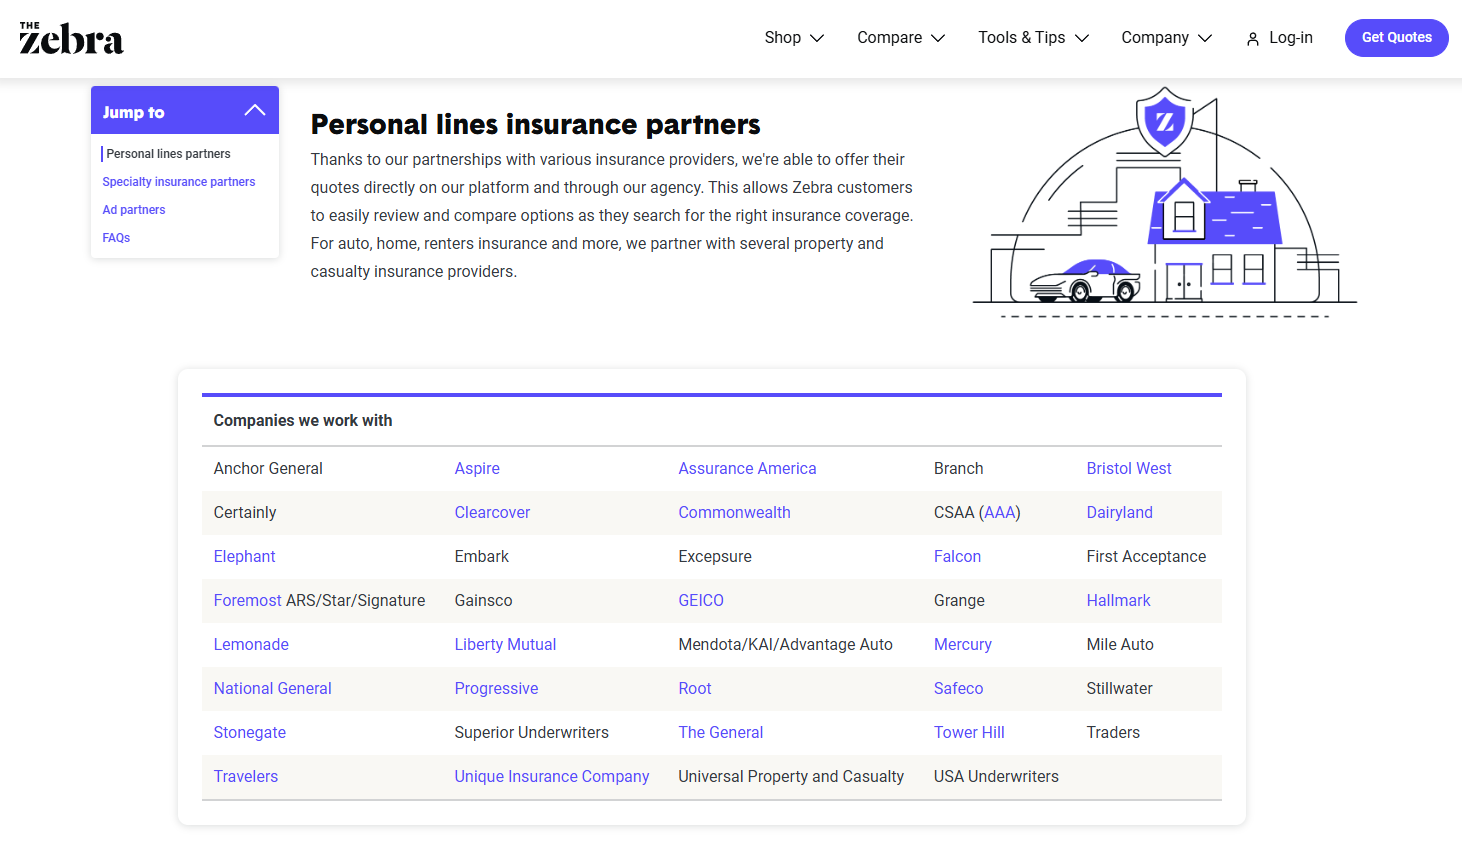
When you enter your information into an aggregator like The Zebra, Gabi, or Policygenius, the platform distributes that data to multiple insurance partners. Within minutes, you receive a list of quotes from various companies. These sites are categorized into two types:
- Direct-to-Consumer Aggregators: These provide actual pricing and allow you to bridge directly to the insurer’s site to buy the policy.
- Lead Generation Sites: These often promise "free quotes" but primarily exist to sell your contact information to local agents. To avoid an influx of unsolicited phone calls, prioritize platforms that display prices immediately on the results page.
The Benefits of Aggregators
The primary advantage is speed. Instead of spending 15 minutes on ten different websites, you spend 15 minutes on one. Aggregators are also excellent for discovering smaller, regional insurers that you might not have considered but which often offer highly competitive rates for specific demographics or geographic areas.
Limitations to Consider
Not every insurance company participates in comparison platforms. Large "captive" insurers—those that only sell through their own agents or websites—often opt out of these tools to maintain control over the customer experience. Consequently, an aggregator might miss some of the market leaders in your specific zip code.
Visiting Direct Carrier Websites
After using a comparison tool to identify the most competitive price range, the next step is to visit the websites of the "Big Five" insurers directly if they did not appear in your initial search. In 2026, companies like GEICO, Progressive, State Farm, Allstate, and USAA (for military families) continue to dominate the market by offering proprietary discounts that aggregators may not capture.
Why Direct Quoting Matters
Direct websites often offer specialized features, such as "Name Your Price" tools or specific bundles for multi-policy discounts (e.g., combining auto with homeowners or renters insurance). Furthermore, direct sites are the primary gateway for enrolling in telematics programs. In 2026, nearly all major carriers offer "pay-how-you-drive" or "pay-per-mile" options. These programs use smartphone apps or OBD-II devices to track your braking, speed, and mileage, potentially offering discounts of 20% to 40% for safe drivers.
The Bundling Advantage
If you own a home or rent an apartment, quoting your auto insurance alongside your property insurance is vital. Direct carrier websites are better equipped to calculate these multi-line discounts than general aggregators. In many cases, the discount on a homeowners policy can effectively offset a portion of the auto premium, a nuance often lost in third-party comparison tools.
Understanding the Components of Your Quotes
When you receive multiple quotes, the "total price" is the least important number. You must verify that the underlying coverage is consistent across all offers. A lower price often masks a higher deductible or lower liability limits.
| Coverage Component | Standard Recommended Limit (2026) | Purpose |
|---|---|---|
| Bodily Injury Liability | $100,000 / $300,000 | Covers medical expenses for others if you are at fault. |
| Property Damage | $100,000 | Covers repairs to other vehicles or structures. |
| Uninsured/Underinsured | Matches Liability Limits | Protects you if hit by a driver with no or low insurance. |
| Collision Deductible | $500 or $1,000 | The amount you pay out of pocket for repairs to your car. |
| Comprehensive Deductible | $500 | Covers non-collision events like theft, fire, or hail. |
| Personal Injury (PIP) | State-specific minimums | Covers your medical bills regardless of fault. |
Liability vs. Full Coverage
"Full coverage" is a colloquial term, not a legal one. It generally refers to a policy that includes liability, collision, and comprehensive insurance. If you are driving a car that is leased or financed, your lender will likely require "full coverage" with a maximum deductible (often $1,000). If you are driving an older vehicle with low market value, you might consider "liability only" to save on premiums, though this leaves you with no protection for your own vehicle’s repairs.
Factors Influencing Online Quotes in 2026
The insurance market in 2026 is influenced by several technical and economic factors that you should understand to better interpret your quotes.
Telematics and Data Privacy
Most online quotes will now ask if you are willing to share driving data via an app. While this can lower costs, it requires a trade-off in privacy. Some insurers in 2026 have moved toward "continuous underwriting," where your premium can fluctuate monthly based on your driving behavior rather than staying fixed for a six-month term.
Vehicle Technology and Repair Costs
As vehicles become more sophisticated, with sensors embedded in bumpers and windshields, the cost of "minor" repairs has surged. If your quote seems high despite a clean driving record, it may be due to the high Loss Cost Rating of your specific vehicle model. Insurers use historical data to determine which cars are more expensive to fix after a claim.
Credit-Based Insurance Scores
In most states (excluding California, Hawaii, Massachusetts, and Michigan), insurers use your credit history to help determine your premium. Online quote engines will perform a soft credit pull to provide an accurate rate. Improving your credit score can often have a larger impact on your insurance premium than even a year of safe driving.
Common Mistakes to Avoid
- Setting Deductibles Too Low: While a $250 deductible sounds safe, it significantly inflates your monthly premium. Many drivers in 2026 find that a $1,000 deductible offers the best balance of monthly savings and manageable out-of-pocket risk.
- Ignoring GAP Insurance: if you are financing a new vehicle, ensure your quote includes "Guaranteed Asset Protection" (GAP) insurance. This covers the difference between what you owe on the car and its actual cash value if it is totaled.
- Providing Inaccurate Mileage: Be realistic about your annual mileage. Underestimating it might lower your quote initially, but if a claim arises and the odometer reveals a massive discrepancy, the insurer could potentially deny the claim or adjust the premium retroactively.
- Skipping the Fine Print on Discounts: Some online quotes automatically apply "new customer" or "paperless" discounts that might disappear after the first six months. Always check which discounts are recurring and which are one-time incentives.
Finalizing Your Selection
Once you have compared at least three to five quotes, select the policy that offers the best "Value-to-Protection" ratio. Before paying the first premium, read the Insurance Information Institute (III) guidelines on policy cancellations to ensure your new coverage starts exactly when your old one ends. This prevents a "coverage gap," which can lead to higher rates in the future.
Verify the insurer’s financial stability through ratings from organizations like A.M. Best or S&P Global. A low price is of little use if the company lacks the financial strength to pay out a significant claim. Once satisfied, you can usually sign the documents electronically and download your proof of insurance (ID cards) immediately.
Frequently Asked Questions
Does getting multiple quotes online hurt my credit score?
No, insurance companies use a "soft inquiry" to check your credit-based insurance score during the quoting process. Unlike a "hard inquiry" used for credit card or loan applications, a soft inquiry does not affect your credit score or appear to other lenders.
How often should I shop for new auto insurance quotes?
It is recommended to shop for quotes every 12 months or whenever you experience a major life event, such as moving to a new zip code, getting married, or purchasing a new vehicle. In 2026, the market is dynamic, and rates can shift significantly year-over-year.
Why is the final price different from the online quote?
The initial quote is an estimate based on the information you provided. The price only becomes final after the insurer runs your official motor vehicle report (MVR) and claims history (CLUE report). Discrepancies in accident dates or undisclosed tickets are the most common reasons for price changes.
Can I get quotes online if I have a "high-risk" driving record?
Yes, many online platforms specialize in "non-standard" insurance for drivers with multiple violations, DUIs, or lapses in coverage. However, you may find that the number of carriers willing to provide an instant online quote is smaller, and you may eventually need to speak with a specialized agent to finalize coverage.
Are online-only insurance companies reliable?
Many "insurtech" companies operate exclusively online and are fully regulated and backed by significant capital. The reliability of an insurer is best measured by its A.M. Best financial strength rating and its complaint ratio with the National Association of Insurance Commissioners (NAIC), rather than whether it has physical office locations.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
