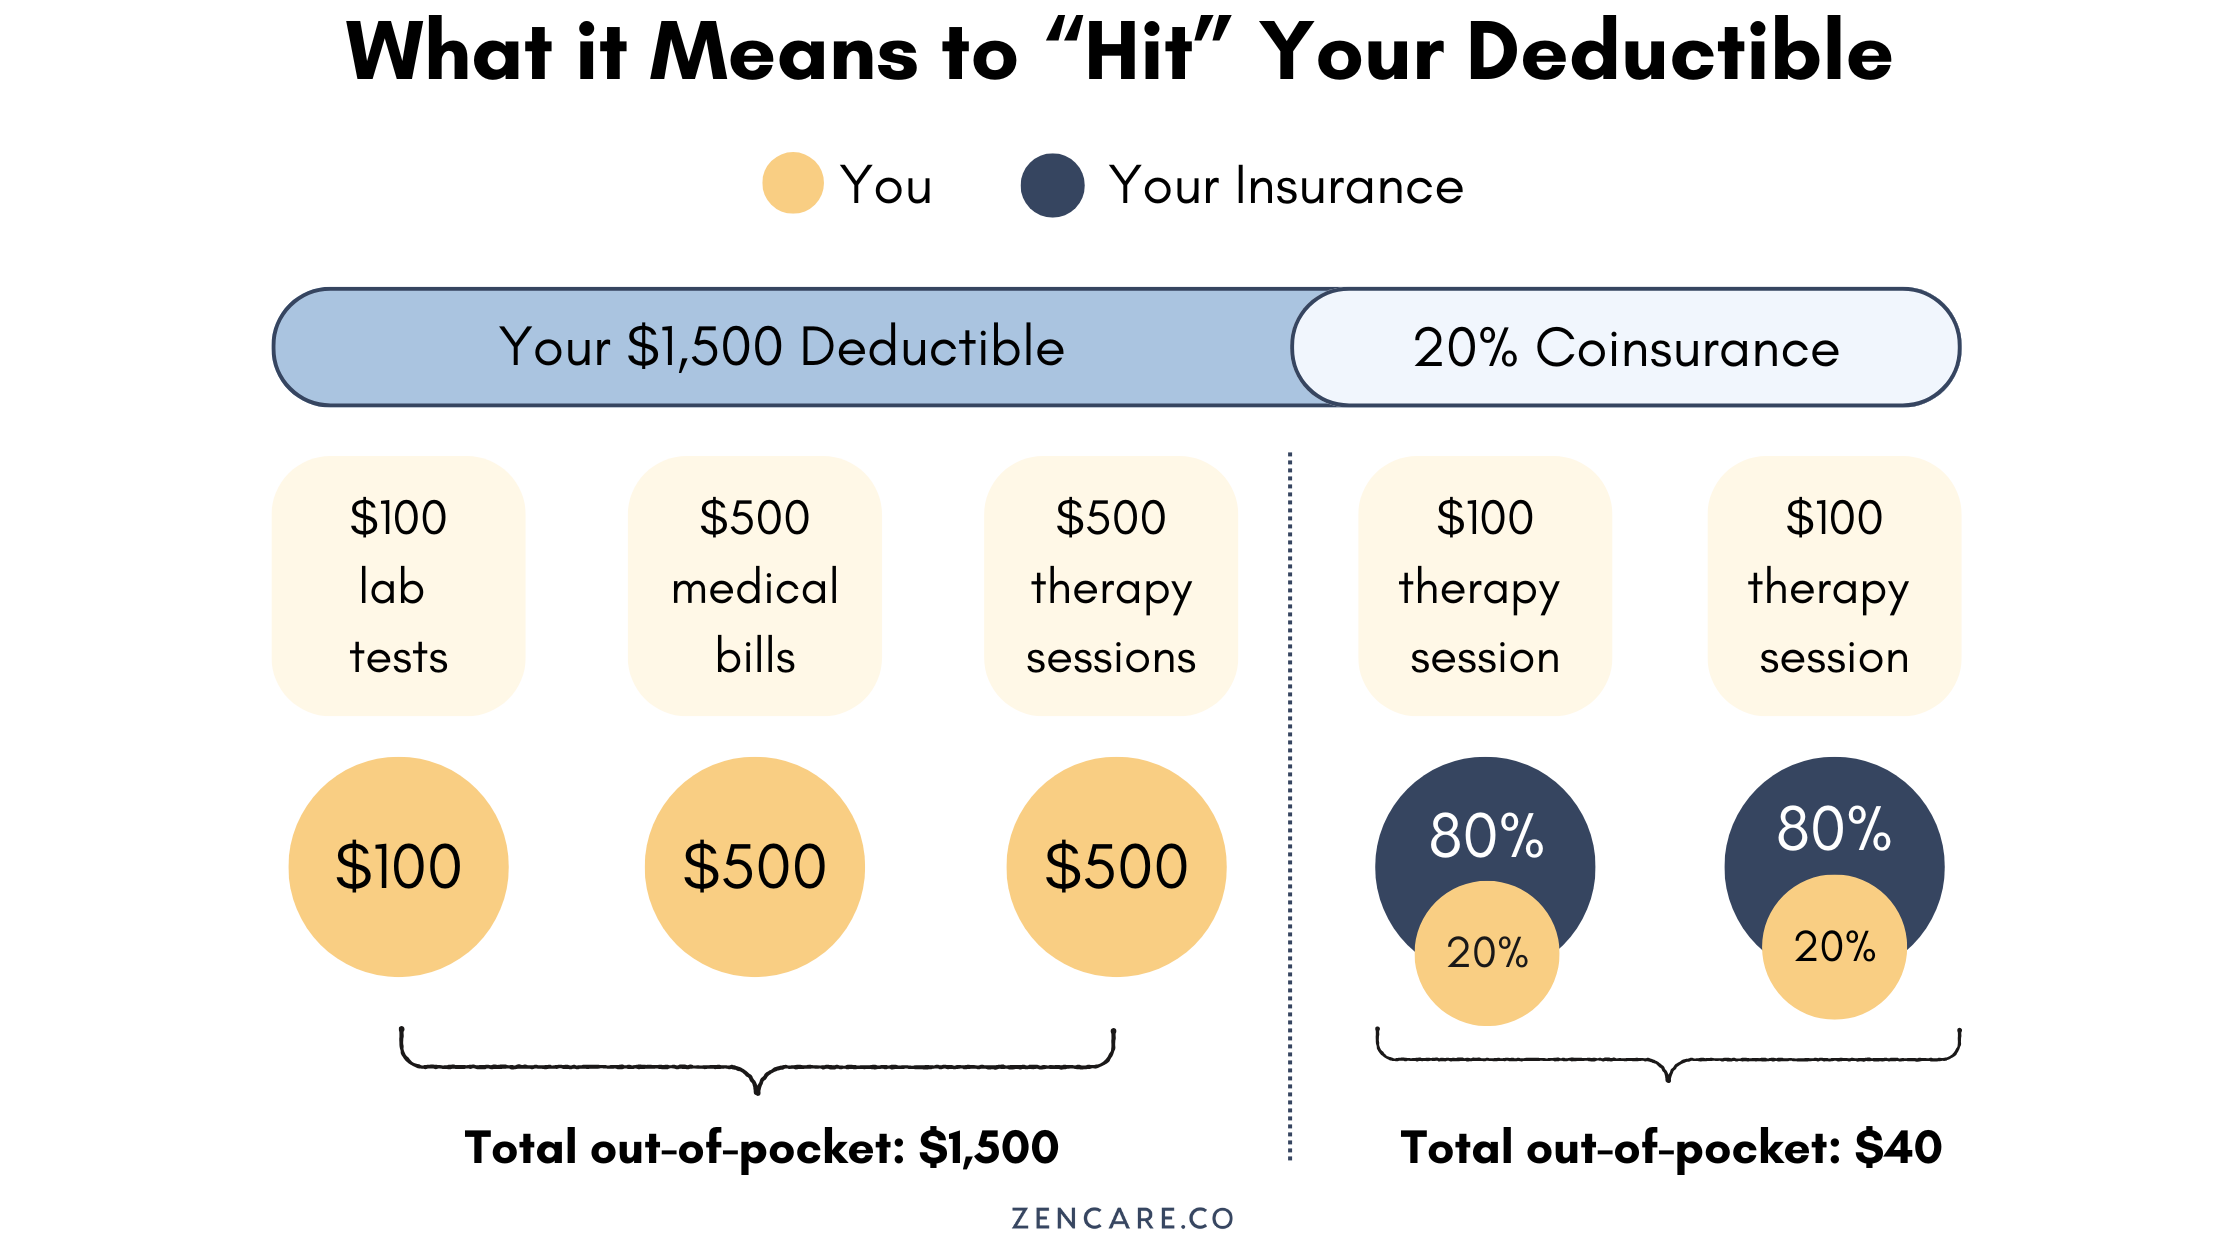
A $2,000 deductible on a travel insurance policy means you must pay the first $2,000 of eligible out-of-pocket expenses for a covered claim before the insurance company begins paying its share. This structure lowers your upfront premium costs but transfers a significant portion of early financial risk directly to you in the event of a disruption or emergency.
Understanding the Fundamentals of Travel Insurance Deductibles
When purchasing a comprehensive travel insurance policy, navigating financial terminology is essential to securing the right coverage for your trip. Among these terms, the "deductible" plays a pivotal role in determining both your upfront costs and your financial exposure while traveling. Simply put, a deductible is the agreed-upon amount of money you must pay toward a covered loss before your insurance provider pays out any benefits.
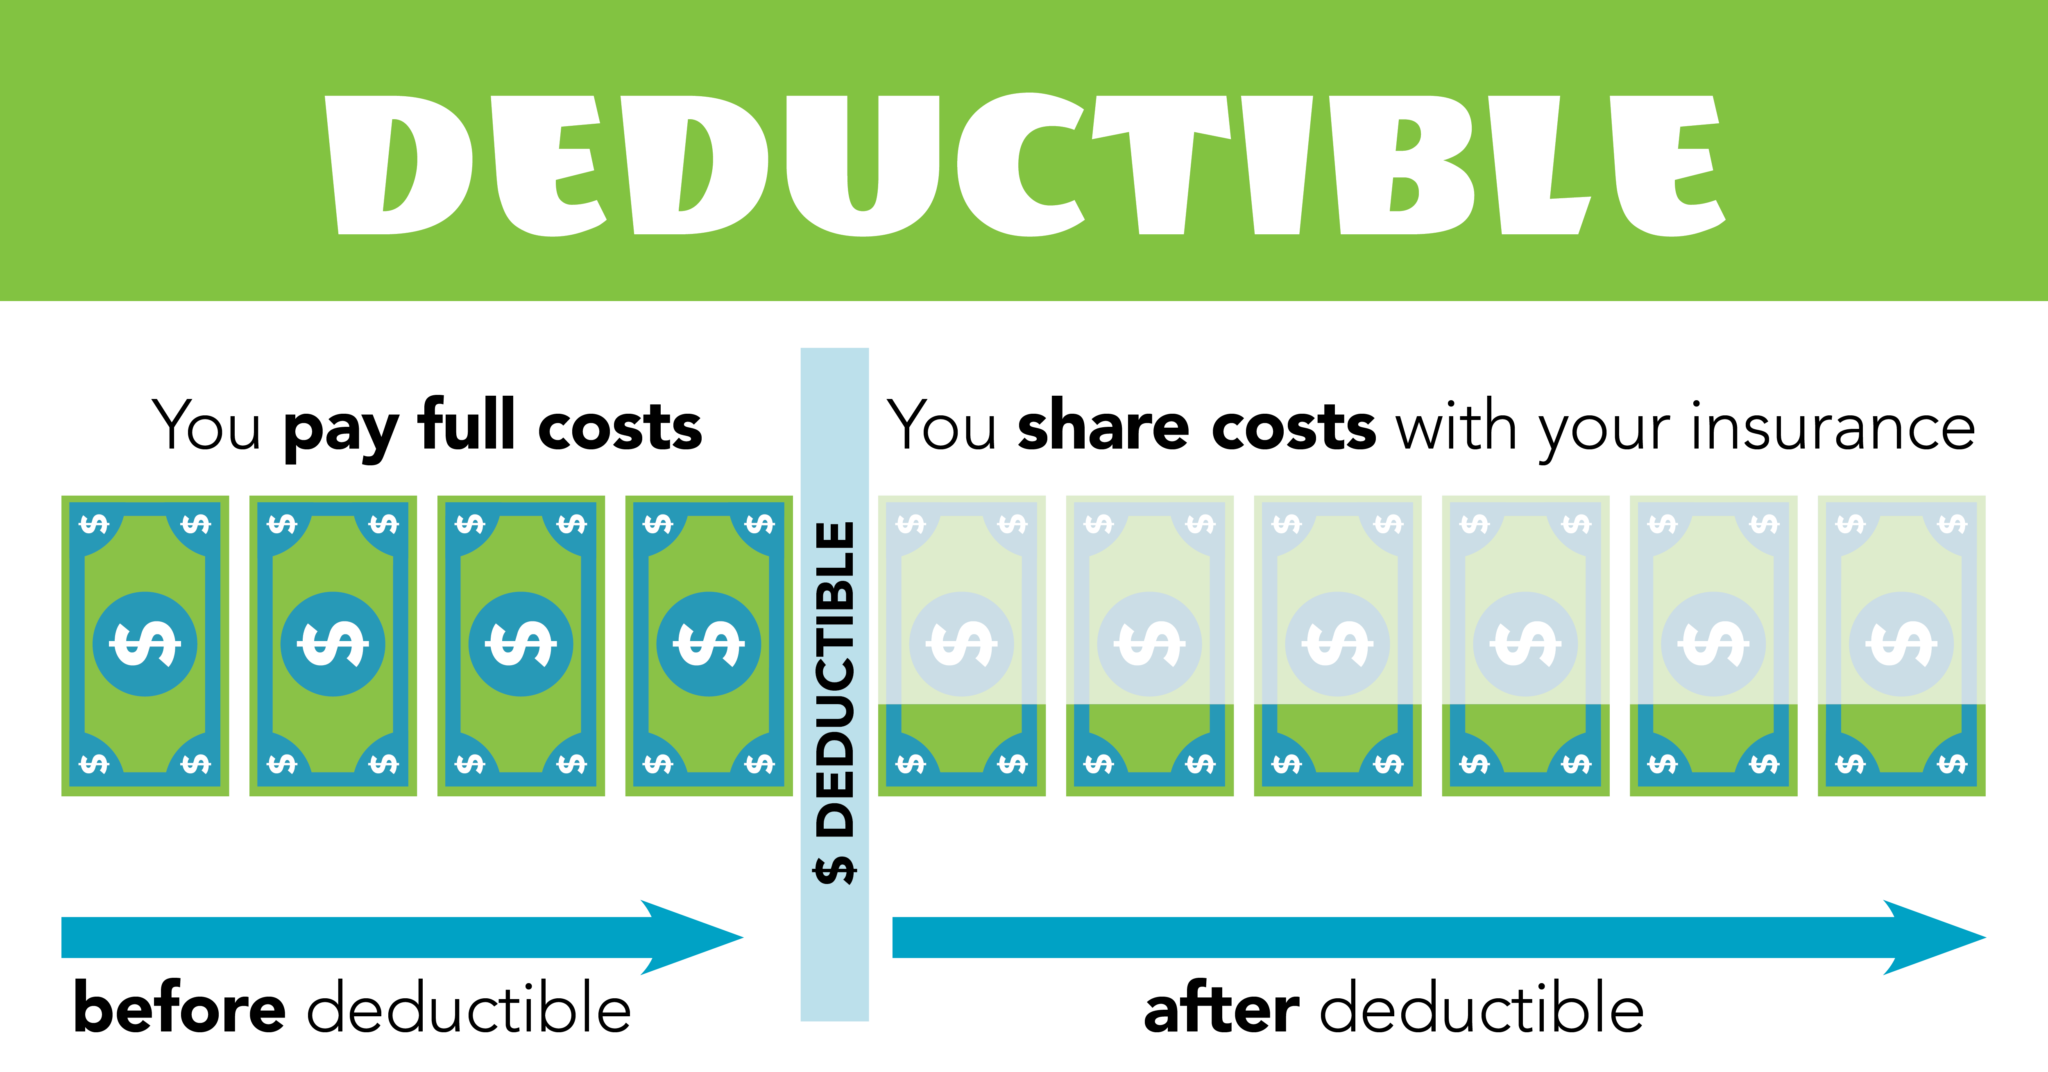
When applied to travel insurance, a $2,000 deductible introduces a specific mathematical threshold to your policy. If an unexpected event occurs—such as emergency medical treatment abroad or damaged baggage—and results in a financial loss, you are responsible for the initial $2,000 of that loss. The insurer only covers costs that exceed this $2,000 baseline, up to your policy’s maximum limit.
It is also important to distinguish between deductibles and other common policy limitations, such as copayments, coinsurance, and coverage maximums. While a copayment is a flat fee per service and coinsurance is a percentage-based split of costs, a deductible is a fixed dollar amount applied per claim or per policy period. Understanding this distinction prevents unexpected financial strain when filing a claim after a trip disruption.
How a $2,000 Deductible Operates in Practice
To fully grasp what a $2,000 deductible means for travel insurance, examining real-world financial scenarios clarifies how costs are distributed between the traveler and the insurance provider. Travel insurance policies do not always apply a deductible uniformly across all benefits. In fact, many standard policies apply deductibles primarily to specific categories, such as emergency medical and dental coverage, trip interruption, or baggage loss, while other benefits like trip cancellation may have a $0 deductible.
Consider a scenario where you experience a medical emergency while traveling internationally, resulting in total hospital and physician bills amounting to $7,000. If your travel medical insurance policy features a $2,000 deductible, the claims adjustment process unfolds in a predictable sequence:
- Evaluation of Coverage: The insurer reviews the itemized medical bills to verify that the treatments received qualify as covered events under the policy terms.
- Deductible Application: The insurer subtracts the $2,000 deductible from the total verified claim amount.
- Insurer Payout: The insurer pays the remaining balance of $5,000 directly to the healthcare provider or reimburses you, depending on how the claim is settled.
- Out-of-Pocket Total: You are ultimately responsible for paying the initial $2,000 out of pocket.
Now consider a smaller claim, such as a medical bill totaling $1,500 for an urgent care visit due to a minor injury. Because the total eligible expense falls below the $2,000 threshold, the insurance company will issue a payout of $0. You absorb the entire cost, and the deductible prevents the claim from yielding any financial reimbursement.
| Total Claim Amount | Deductible Amount | Insurer Payout | Your Out-of-Pocket Cost |
|---|---|---|---|
| $7,000 (Medical Emergency) | $2,000 | $5,000 | $2,000 |
| $3,500 (Trip Interruption) | $2,000 | $1,500 | $2,000 |
| $1,500 (Urgent Care Visit) | $2,000 | $0 | $1,500 (Full Amount) |
| $500 (Lost Baggage) | $2,000 | $0 | $500 (Full Amount) |

The Impact of a High Deductible on Premiums and Risk
Opting for a $2,000 deductible is a deliberate financial strategy designed to alter the balance between premium pricing and personal risk exposure. Insurance underwriters price policies based on the probability of loss and the anticipated payout volume. When a policyholder agrees to shoulder a high deductible—such as $2,000—they assume a substantial portion of the financial risk, which reduces the insurer's potential payout liability for minor or moderate claims.
In exchange for accepting this elevated risk, insurance providers typically offer lower upfront premium rates. For travelers planning expensive trips or looking to minimize the immediate cost of comprehensive protection, selecting a high deductible can make premium plans more affordable. However, this strategy requires careful risk assessment. If your trip goes smoothly without any major disruptions, you save money on the premium. If an emergency occurs, you must have the liquidity available to cover that $2,000 out-of-pocket expense immediately.
Furthermore, travelers must evaluate whether a high deductible aligns with their personal risk tolerance and financial preparedness. If paying an unexpected $2,000 bill would create severe financial hardship during or immediately after a trip, the short-term savings achieved through a lower premium may not justify the long-term exposure.
Comparing $0, $250, $500, and $2,000 Deductibles
To determine whether a $2,000 deductible is appropriate for your itinerary, it helps to compare it directly with lower deductible tiers commonly offered in the travel insurance marketplace. Different coverage levels serve different traveler profiles, budgets, and risk management strategies.
| Deductible Tier | Premium Cost | Out-of-Pocket Risk | Best Suited For |
|---|---|---|---|
| $0 Deductible | Highest | Lowest | Travelers seeking zero financial surprises and comprehensive first-dollar coverage. |
| $250 Deductible | Moderate-High | Low | Risk-averse travelers who want low out-of-pocket costs without paying top-tier premiums. |
| $500 Deductible | Moderate | Moderate | Balanced travelers looking for a middle ground between premium savings and risk protection. |
| $2,000 Deductible | Lowest | High | Budget-conscious travelers prioritizing low premiums who can absorb high emergency costs. |
As shown in the comparison, moving from a $0 deductible to a $2,000 deductible significantly reduces your monthly or trip-based insurance premium. However, it shifts the financial responsibility of minor mishaps entirely to you. Travelers should weigh the frequency of smaller claims against the savings on the policy cost before making a final selection.
Advantages of Choosing a $2,000 Deductible
Selecting a $2,000 deductible offers distinct financial benefits for specific types of travelers and travel scenarios. Understanding these advantages helps clarify when a high-deductible policy represents a smart financial choice rather than a risky gamble.
- Lower Upfront Premiums: The most immediate benefit is a reduced policy cost. If you are insuring an expensive international trip, cutting down the base insurance rate can provide meaningful savings.
- Focus on Catastrophic Protection: A high deductible effectively transforms your travel insurance into catastrophic coverage. Rather than filing claims for minor expenses, your policy functions as a safety net designed to protect you from financially devastating events, such as a major medical evacuation or prolonged hospitalization.
- Ideal for Well-Prepared Travelers: For individuals who maintain robust emergency savings funds specifically earmarked for travel contingencies, a $2,000 deductible allows them to self-insure minor risks while transferring severe financial liabilities to the insurance carrier.
Disadvantages and Hidden Pitfalls of a High Deductible
While lower premiums are attractive, a $2,000 deductible comes with notable drawbacks and potential financial traps that travelers must consider before purchasing a policy.
- High Out-of-Pocket Burden: If a covered emergency occurs, finding $2,000 in liquid cash while away from home can be stressful and logistically difficult.
- Risk of Uncompensated Losses: Many common travel issues—such as minor flight delays, short-term baggage misplacement, or minor outpatient medical care—frequently cost less than $2,000. Under a high-deductible policy, you receive zero reimbursement for these frequent travel headaches.
- Per-Claim vs. Per-Policy Deductible Rules: It is vital to read the policy certificate carefully to determine whether the $2,000 deductible applies per claim, per incident, or per policy year. If the deductible applies to every separate incident, multiple minor issues could result in multiple $2,000 out-of-pocket payments.
Common Mistakes When Evaluating Travel Insurance Deductibles
Navigating travel insurance policy language often leads to misunderstandings that can result in unexpected expenses during a trip. Recognizing these common errors helps ensure you select a policy that matches your expectations.
One frequent mistake is assuming that a single deductible applies uniformly to every benefit listed in the policy. Many travelers buy a policy with a high deductible assuming it lowers the cost across the board, only to discover later that trip cancellation carries a $0 deductible while emergency medical care carries the steep $2,000 threshold. Always review the schedule of benefits to see exactly where deductibles apply.
Another error is failing to read the fine print regarding reimbursement timelines and credit card holds. When seeking medical care abroad under a high-deductible plan, foreign hospitals often require upfront payment or a credit card authorization for the full estimated amount before rendering treatment. Even though your insurance will eventually cover costs exceeding $2,000, you may need to temporarily finance the entire medical bill out of pocket until the insurance claim is processed and settled.
Frequently Asked Questions
Does a $2,000 deductible apply to trip cancellation coverage?
Usually, no. In most comprehensive travel insurance policies, trip cancellation benefits feature a $0 deductible because the insurer calculates the exact prepaid, non-refundable trip costs at the time of purchase. Deductibles are much more commonly applied to emergency medical, dental, baggage, and rental car collision damage benefits.
Can I pay my travel insurance deductible in installments?
No. Travel insurance deductibles are not paid in installments or added to your premium. Instead, the deductible is a direct subtraction applied by the insurance company at the time a claim is processed. The insurer simply deducts that amount from your total reimbursement payout.
Is a $2,000 deductible worth it for cheap trips?
Generally, no. If your total trip cost is low—such as a $1,500 weekend getaway—a $2,000 deductible makes little financial sense because any potential loss would fall below the deductible threshold, leaving you entirely uninsured for that specific claim. High deductibles are primarily designed to offset the high costs of insuring expensive long-haul or luxury itineraries.
Do credit card travel insurance policies have deductibles?
Many secondary or primary travel insurance policies provided automatically through premium credit cards feature low or zero deductibles, but coverage limits, terms, and exclusions vary significantly. Always examine the specific cardholder benefit guide to verify whether a deductible applies to medical or trip interruption claims.
What happens if my claim is less than the $2,000 deductible?
If the total eligible expense of your claim is less than $2,000, the insurance company will not issue a payout. You are responsible for covering 100% of the cost out of pocket, which is why matching your deductible to your risk tolerance and savings is essential.
Summary and Next Actions
Selecting a travel insurance policy with a $2,000 deductible requires balancing the immediate savings of a lower premium against your ability to absorb sudden out-of-pocket expenses during a trip. Before purchasing coverage, review the schedule of benefits to verify exactly which policy sections are subject to the deductible, check whether it applies per claim or per policy, and ensure you have emergency funds available to cover the threshold if an unexpected event occurs. Compare multiple quotes from reputable providers to find a deductible tier that matches your comfort level and financial readiness.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
