The consensus across major Reddit financial communities is that using life insurance to build wealth is generally inefficient for the average investor. While subreddits like r/personalfinance and r/fire advocate for "Buying Term and Investing the Difference" (BTID), they acknowledge that permanent policies serve specific tax-mitigation and estate-planning functions for ultra-high-net-worth individuals.
For years, the "life insurance to build wealth" conversation on Reddit has been one of the most polarized topics in the personal finance sphere. If you browse through subreddits such as r/personalfinance, r/investing, or r/financialindependence, you will encounter a fierce clash between two groups: the "Buy Term and Invest the Difference" (BTID) purists and the proponents of "Infinite Banking" or Indexed Universal Life (IUL) policies. As of 2026, this debate has only intensified as market volatility and shifting tax landscapes lead more people to seek alternative "safe" buckets for their capital.
To navigate this conversation, it is essential to understand that Reddit is not a monolith, but its dominant culture is rooted in low-cost, index-fund investing. When users post about using life insurance as a "bank" or a "retirement vehicle," they are often met with skepticism, math-heavy rebuttals, and warnings about high commissions. However, beneath the surface-level arguments lies a complex financial discussion regarding tax codes, internal rates of return (IRR), and the specific economic conditions that make permanent life insurance either a "scam" or a sophisticated tool.
The Reddit Orthodoxy: "Buy Term and Invest the Difference"
The most frequent advice given on Reddit regarding life insurance is a simple mantra: Buy Term and Invest the Difference (BTID). The logic behind this is rooted in the opportunity cost of capital. Reddit users often argue that life insurance should be treated as an expense for protection, not an investment for growth.
In this framework, an individual buys a 20- or 30-year term policy to cover their "active" years—when they have a mortgage, young children, and haven't yet reached retirement age. The premium for term insurance is significantly lower than that of permanent insurance. The "difference" in premium cost is then funneled into a low-cost brokerage account or a tax-advantaged retirement plan like a 401(k) or a Roth IRA.
The Reddit community favors this because:
- Transparency: You know exactly what the insurance costs and exactly how your investments are performing.
- Liquidity: Brokerage accounts do not have "surrender charges" or complex loan provisions.
- Lower Fees: The expense ratios of index funds are a fraction of the internal costs found in permanent life insurance policies.
The "Infinite Banking" and IUL Pitch
On the other side of the Reddit divide are users (often insurance agents or those influenced by "fin-fluencers") who promote the Infinite Banking Concept (IBC) or Indexed Universal Life (IUL). In these conversations, life insurance is framed not as an expense, but as a "private reserve" or a "tax-free retirement bucket."
Proponents argue that by overfunding a permanent life insurance policy, you can build a "cash value" that grows tax-deferred. You can then take loans against this cash value to buy real estate, fund a business, or provide retirement income. Because these are loans rather than withdrawals, they are not technically considered taxable income under current IRS rules (specifically Internal Revenue Code Section 72).
Why Reddit is Skeptical of IUL and Whole Life
The skepticism on Reddit toward these products usually centers on three pillars:
- High Commissions: Redditors frequently point out that the agents selling these policies often receive 60% to 100% of the first year's premium as commission. This creates a perceived conflict of interest.
- Complexity and Caps: IUL policies often have "participation rates" and "caps" on growth. If the S&P 500 returns 20% in a year, an IUL policy might be capped at 8% or 10%. Reddit users argue that over 20-30 years, missing out on those "up" years results in massive underperformance compared to a simple index fund.
- The "Zero is Your Hero" Fallacy: Agents often market IULs with the phrase "0% is your hero," meaning you won't lose money in a market downturn. Reddit's counter-argument is that while the account value might not drop due to market performance, the cost of insurance (COI) and administrative fees are still deducted, which can lead to a negative net return in a flat market.

The Mechanics of Cash Value: Fees, Loads, and Surrender Charges
To understand the Reddit critique, one must look at the internal mechanics of a policy. When you pay a premium into a "wealth-building" life insurance policy, that money does not go directly into an investment account.
- Premium Expense Charges: A portion of your premium is immediately taken by the insurance company to cover state premium taxes and administrative costs.
- Cost of Insurance (COI): As you get older, the cost of the actual "death benefit" portion of the policy increases. In some Universal Life policies, if the cash value growth doesn't keep up with the rising COI, the policy can "implode," requiring massive capital injections to stay active.
- Surrender Charges: Most permanent policies have a surrender period lasting 10 to 15 years. If you decide the policy was a mistake in year three, you may find that your "cash surrender value" is zero or significantly less than what you paid in.
Reddit users often share "illustrations"—the projections provided by insurance companies—to show how the projected 6% or 7% returns rarely manifest in reality once these internal costs are subtracted.
When Reddit Agrees: The High-Net-Worth Exception
Despite the general hostility toward permanent life insurance, there is a "nuance" often discussed in subreddits like r/fatFIRE (for those aiming for a very high level of wealth). In these circles, the conversation shifts from "investment" to "estate planning and tax mitigation."
As of 2026, with federal estate tax exemptions always a subject of legislative debate, life insurance remains a primary tool for the wealthy to:
- Pay Estate Taxes: For individuals with estates exceeding the federal exemption limit, life insurance held in an Irrevocable Life Insurance Trust (ILIT) can provide the liquidity needed to pay estate taxes without forcing the sale of a family business or real estate.
- Section 7702 Advantages: For those who have already maxed out their 401(k)s, IRAs, and HSAs, the tax-deferred growth of a life insurance policy provides an additional "tax-advantaged" bucket that has no contribution limits (provided the policy is not classified as a Modified Endowment Contract, or MEC).
- Asset Protection: In many states, the cash value of a life insurance policy is protected from creditors and lawsuits, making it an attractive "fortress" for doctors, lawyers, and business owners.
Comparative Analysis: Wealth Building Strategies
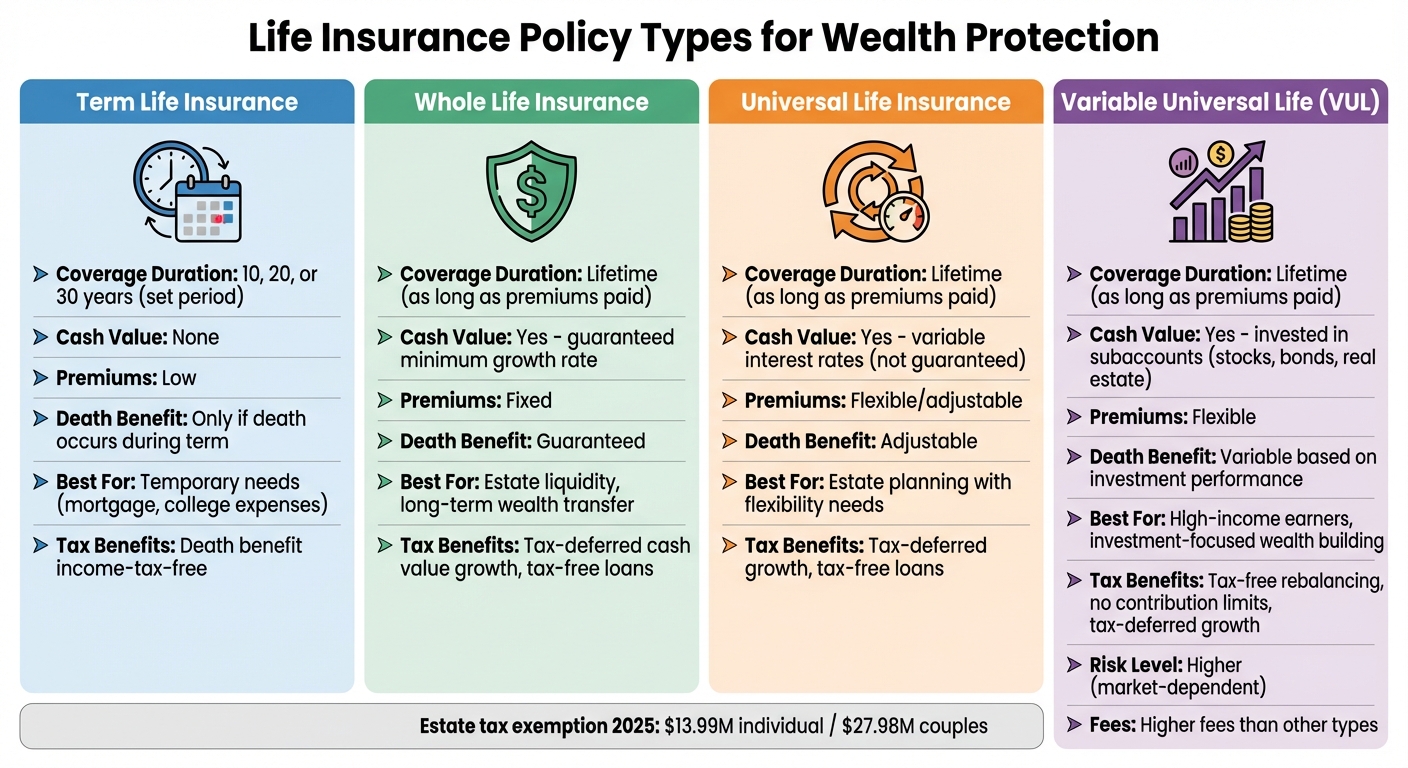
The following table summarizes the key differences discussed in the Reddit "life insurance to build wealth" conversation.
| Feature | Term Life + Index Funds (BTID) | Whole Life Insurance | Indexed Universal Life (IUL) |
|---|---|---|---|
| Primary Goal | Protection + Maximum Growth | Protection + Guaranteed Cash Value | Protection + Market-Linked Growth |
| Fees/Costs | Very Low (0.03% - 0.10% exp. ratios) | High (Commissions & Admin) | Moderate to High (COI & Caps) |
| Liquidity | High (Sell stocks anytime) | Low (Early years), then via Loans | Low (Early years), then via Loans |
| Tax Status | Taxable (Brokerage) or Deferred (401k) | Tax-Deferred Growth / Tax-Free Loans | Tax-Deferred Growth / Tax-Free Loans |
| Risk Profile | Market Risk (High Volatility) | Low Risk (Guaranteed Dividends) | Moderate Risk (Market-Linked, 0% Floor) |
| Complexity | Simple | Moderate | High (Moving parts/caps/floors) |
Common "Red Flags" Identified by the Reddit Community
In the ongoing conversation, several "red flags" are frequently identified by users when they are approached by someone selling a wealth-building insurance strategy:
- "Be Your Own Bank": This is a hallmark of the Infinite Banking Concept. Reddit's debunking usually focuses on the fact that you are paying interest to "borrow" your own money, and while the company may pay you a dividend, the math rarely beats a standard investment portfolio over time.
- Focus on "Tax-Free" without mentioning "Cost of Insurance": Agents often emphasize that the money comes out tax-free but fail to highlight that the cost of insurance (which scales with age) can eat up the gains.
- Hiding the IRR: The "Internal Rate of Return" is the real number that matters. Reddit users often advise asking for an illustration that shows the IRR at age 65, 75, and 85. In many cases, the IRR is 2% to 4%, which is lower than the historical return of the stock market.
- The "7702" Pitch: Some agents reference Section 7702 of the tax code as if it’s a "secret" loophole. Reddit users are quick to point out that this is simply the standard tax definition of life insurance and not a specialized wealth-building program.
Expert Guidance: How to Evaluate the Strategy
If you are considering using life insurance to build wealth, the Reddit community generally recommends a "trust but verify" approach. Before committing to a permanent policy, consider the following steps:
- Ask for a "Full Illustration": Ensure it includes the "guaranteed" column, not just the "projected" or "current" column. The guaranteed column shows what happens if the company performs at its worst.
- Calculate the Break-Even Point: Look at how many years it takes before the "Cash Surrender Value" equals the total premiums paid. In many whole life policies, this can take 10 to 15 years.
- Compare to a Roth IRA: If you haven't maxed out a Roth IRA or a Roth 401(k), the Reddit consensus is that those should always come first. They offer tax-free growth without the "cost of insurance" drag.
- Consult a Fee-Only Fiduciary: Seek advice from a financial advisor who does not sell insurance products. A fiduciary is legally obligated to act in your best interest and will provide a neutral perspective on whether the policy fits your goals.
Frequently Asked Questions
Is life insurance a good investment for the average person?
According to the prevailing sentiment on Reddit and many financial experts, no. For the average person, the high fees and commissions of permanent life insurance make it an inferior wealth-building tool compared to low-cost index funds and traditional retirement accounts. Life insurance should primarily be viewed as risk management (replacing income in the event of death).
Why do some people call Whole Life insurance a scam?
The term "scam" is often used on Reddit because the products are frequently sold to people who do not need them and cannot afford them. Because of the high commissions, agents may push these policies onto young professionals who would be better served by term insurance. However, technically, they are legitimate financial products; the "scam" refers to the perceived mismatch between the product's benefits and the consumer's needs.
What is the "Infinite Banking" concept?
Infinite Banking involves using the cash value of a permanent life insurance policy as a source of financing. Instead of using a bank for loans (like for a car or business), you borrow against your policy's cash value. Proponents argue this keeps the interest "in the family," while critics on Reddit point out that the opportunity cost and the interest paid back to the insurer often negate the benefits.
Can Indexed Universal Life (IUL) policies lose money?
While IUL policies typically have a "0% floor" that protects against market losses, the account value can still decrease. This happens if the cost of insurance (COI) and administrative fees exceed the interest credited to the account in a given year. If the market is flat for several years, the policy's value will decline due to these internal expenses.
Is there anyone who should actually buy a wealth-building life insurance policy?
Yes. Wealth-building policies are often appropriate for individuals with an estate tax problem (estates over $13M+ depending on current 2026 laws), those who have exhausted all other tax-advantaged investment vehicles, or those looking for a specific type of asset protection from creditors. It is a niche tool for the wealthy, not a general tool for the middle class.
Practical Recommendation
Before adopting any strategy discussed in the "life insurance to build wealth" conversation on Reddit, perform a rigorous audit of your current financial state. If you have high-interest debt, have not maxed out your employer-sponsored 401(k) or your IRA, or do not have a six-month emergency fund, a permanent life insurance policy is almost certainly the wrong move.
If you are a high-earner looking for tax diversification, avoid the "sales pitches" found on social media. Instead, ask for a "maximum funded" or "minimum death benefit" illustration. This structure minimizes the commission and the cost of insurance while maximizing the cash growth. Finally, always compare the projected returns against a conservative 7% annual return from a diversified stock portfolio to see if the tax benefits of the insurance policy truly outweigh the higher returns of the market.
Image Gallery
Select an image to open it in a new tab.

Declan O'Connor
Higher Education and Campus Culture Reporter
