
As of 2026, the number of Ultra High Net Worth Individuals (UHNWIs) in the United States is estimated to be approximately 250,000 to 275,000 individuals, depending on the specific asset valuation methodology and exclusion criteria used by financial research firms. These figures represent residents with a net worth of $30 million or more, excluding their primary residence.
Understanding the Definition of UHNWI
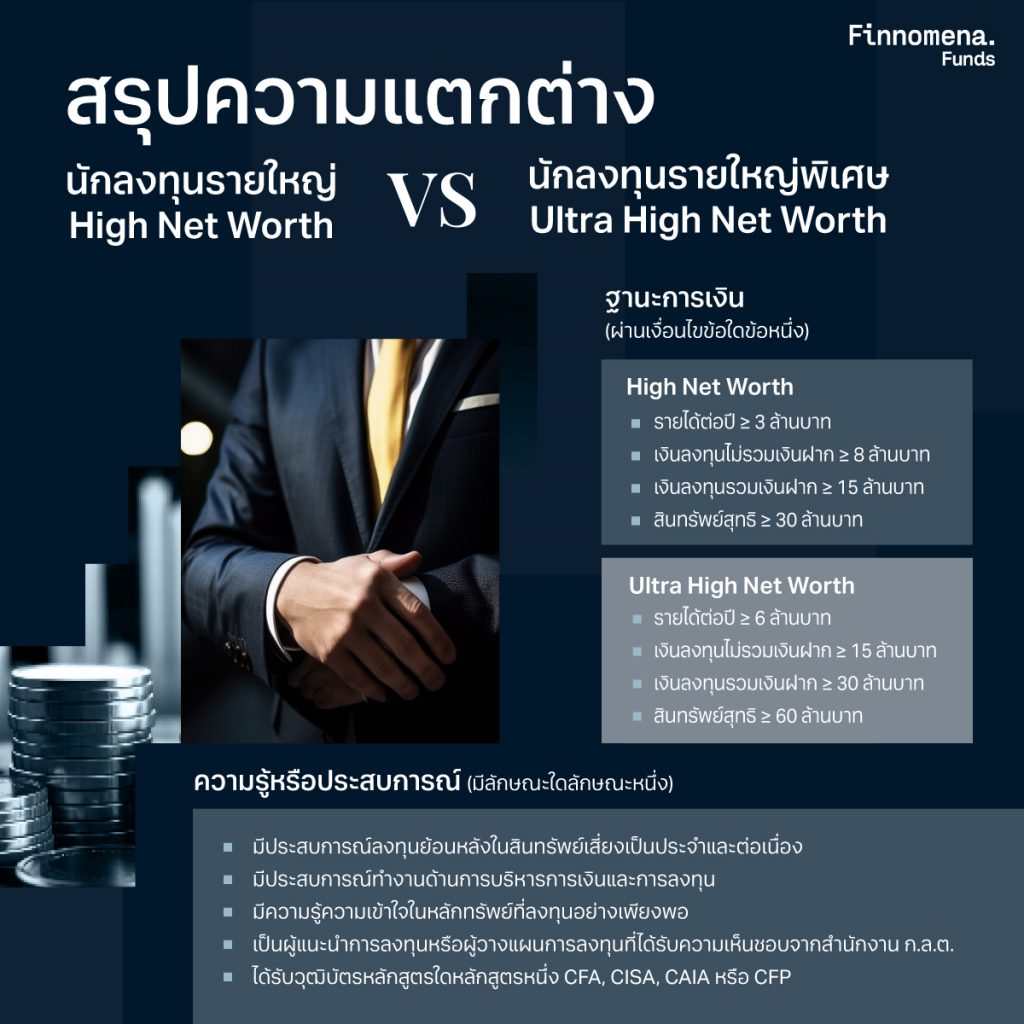
The designation "Ultra High Net Worth Individual" is a standard industry term used by global wealth managers, private banks, and economic research institutions. While definitions can vary slightly, the most widely accepted threshold for an UHNWI is an individual with a net worth of at least $30 million USD.
Unlike the more common "High Net Worth Individual" (HNWI) category, which typically starts at $1 million in liquid assets, the UHNWI bracket represents the top tier of personal wealth. Calculating this number is complex because it involves assessing total assets—including private business equity, art collections, real estate investments, and liquid securities—while subtracting liabilities.
For the purposes of statistical analysis, most reports omit the value of a primary residence to avoid skewing data based on regional real estate bubbles or luxury housing valuations. This distinction is critical for financial planners and institutions that focus on wealth preservation, tax strategies, and estate management.
Methodologies for Estimating Wealth
Measuring the number of individuals in this bracket is not an exact science, as the majority of their wealth is often held in private, non-publicly traded assets. Research firms typically employ three main methodologies to arrive at their estimates:
- Wealth Benchmarking: Firms analyze high-end consumer spending data, luxury real estate transactions, and philanthropic records to build a profile of wealthy cohorts.
- Asset Allocation Modeling: Analysts look at the total pool of investable wealth in the U.S. and use distribution algorithms (such as the Pareto distribution) to determine how many individuals control the largest slices of that total.
- Direct Wealth Intelligence: Specialized firms maintain databases of known assets, board memberships, and business ownership to track individuals who meet or exceed the $30 million threshold.
The volatility of public markets and interest rates significantly influences these counts year-over-year. As of 2026, the stabilization of financial markets has resulted in a moderate, steady growth of the UHNWI population compared to the high volatility observed in the early 2020s.
Regional Concentration of Wealth
In the United States, UHNWI density is not uniform. The concentration of this population is heavily influenced by proximity to financial hubs, the technology sector, and industrial epicenters.
The majority of these individuals reside in major metropolitan areas where business opportunities, capital access, and tax incentives align. Major hubs such as New York City, San Francisco, Los Angeles, and Chicago remain the primary residences for a significant percentage of the UHNWI cohort. However, trends observed over the last few years show a migration toward states with more favorable tax structures, such as Florida and Texas, which have seen a rise in the number of high-net-worth residents relocating from traditional financial centers.
Factors Influencing UHNWI Growth and Retention
Several macroeconomic and personal factors contribute to the fluctuation in the number of ultra-wealthy individuals in the U.S.:
- Asset Performance: For individuals with concentrated holdings in private equity or tech, the performance of the IPO market and venture capital environment is a primary driver of net worth growth.
- Estate and Tax Legislation: Changes to the U.S. Tax Code—specifically regarding capital gains, estate taxes, and carried interest—can influence whether individuals choose to realize gains or hold assets in trust, impacting the statistical count of net worth.
- Corporate Ownership Cycles: The sale of a family-owned business or the acquisition of a private firm by a public corporation can cause a sudden spike in an individual’s net worth, effectively moving them from the HNWI category to the UHNWI category.
- Philanthropy: While donating large sums of money decreases an individual’s personal net worth, the structure of modern philanthropy, often involving donor-advised funds or private foundations, allows some individuals to maintain a form of control over the assets even if they are technically removed from their personal balance sheet.
Comparison of Wealth Categories
To distinguish UHNWIs from other tiers of affluence, it is helpful to look at the relative scale of assets and the complexity of the financial services required.
| Category | Typical Net Worth Threshold | Primary Financial Focus |
|---|---|---|
| Mass Affluent | $100k – $1M | Debt reduction, retirement planning |
| HNWI | $1M – $30M | Asset allocation, tax-efficient investing |
| UHNWI | $30M+ | Multi-generational planning, private equity |
| Billionaires | $1B+ | Global impact, philanthropy, industry influence |
The primary distinction for the UHNWI is the necessity for "Family Office" structures. Once an individual crosses the $30 million threshold, standard wealth management services are often insufficient to address the complexities of global tax compliance, multi-generational wealth transfer, and alternative asset management.
Risks and Challenges to Wealth Preservation
Maintaining a position as an UHNWI involves navigating a unique set of risks that do not apply to the average investor. Cybersecurity threats are a major concern; the concentration of wealth makes these individuals prime targets for sophisticated phishing and social engineering attacks. Furthermore, geopolitical instability can disrupt the international business interests that often constitute a large portion of their wealth.
Financial experts emphasize that for this demographic, the primary objective often shifts from simple capital accumulation to risk mitigation and the preservation of liquidity. Economic downturns, while they may not threaten the basic standard of living for UHNWIs, can cause significant contraction in total net worth, leading to defensive adjustments in portfolio management.
Frequently Asked Questions
What is the minimum net worth to be considered a UHNWI? The industry-standard threshold is $30 million in net assets. This figure excludes the value of a person’s primary residence, as real estate valuations can be highly volatile and are often not liquid, making them an inaccurate measure of true "ultra-high" net worth.
Does this data include government officials? Yes, if a government official or elected representative holds personal assets, business interests, or investments that exceed the $30 million threshold, they are included in the UHNWI count. However, the data is aggregated by wealth intelligence firms and typically excludes public funding or government salaries.
Are these numbers verified by the IRS? No. The Internal Revenue Service does not release an official list of "UHNWIs" for public consumption. IRS data on wealth is anonymized and strictly protected by privacy laws. All counts and statistics regarding UHNWI populations are estimates provided by independent research firms, private banks, and wealth management consultancies.
Why does the number of UHNWIs change so frequently? The fluctuation is primarily driven by market volatility. Since most UHNWI wealth is tied to stocks, private businesses, and real estate, a sharp rise or fall in the S&P 500 or regional housing markets can instantly change the number of individuals who meet the $30 million criteria.
How can I verify the current count of UHNWIs? You can look to annual wealth reports from institutions such as UBS, Knight Frank, or Wealth-X. These organizations produce comprehensive, white-paper-style reports that detail their specific methodology, sources of data, and current estimates for the year.
Professional Advice and Disclaimer
The information provided here is for general educational and informational purposes only and does not constitute financial, legal, or tax advice. Estate planning, asset protection, and tax strategies are highly individualized and subject to the laws of specific jurisdictions. Individuals seeking to manage significant wealth should consult with qualified professionals, including a certified financial planner, a tax attorney, and a wealth manager, to discuss their specific situation. Always verify the status of current tax regulations with official government resources, such as the Internal Revenue Service (IRS) website, to ensure compliance with changing federal and state laws.
Next Steps for Financial Planning
For individuals currently approaching the UHNWI threshold, the recommended next step is a comprehensive portfolio audit. Conduct a formal assessment of all holdings—including non-liquid assets—to ensure that your current estate plan and tax structure are designed for the next stage of wealth management. If you do not already have a dedicated family office or a team of specialized advisors, consider consulting with a private bank that offers high-touch, bespoke services for ultra-high-net-worth clients to ensure your long-term objectives are protected and your risks are properly managed.

Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
