
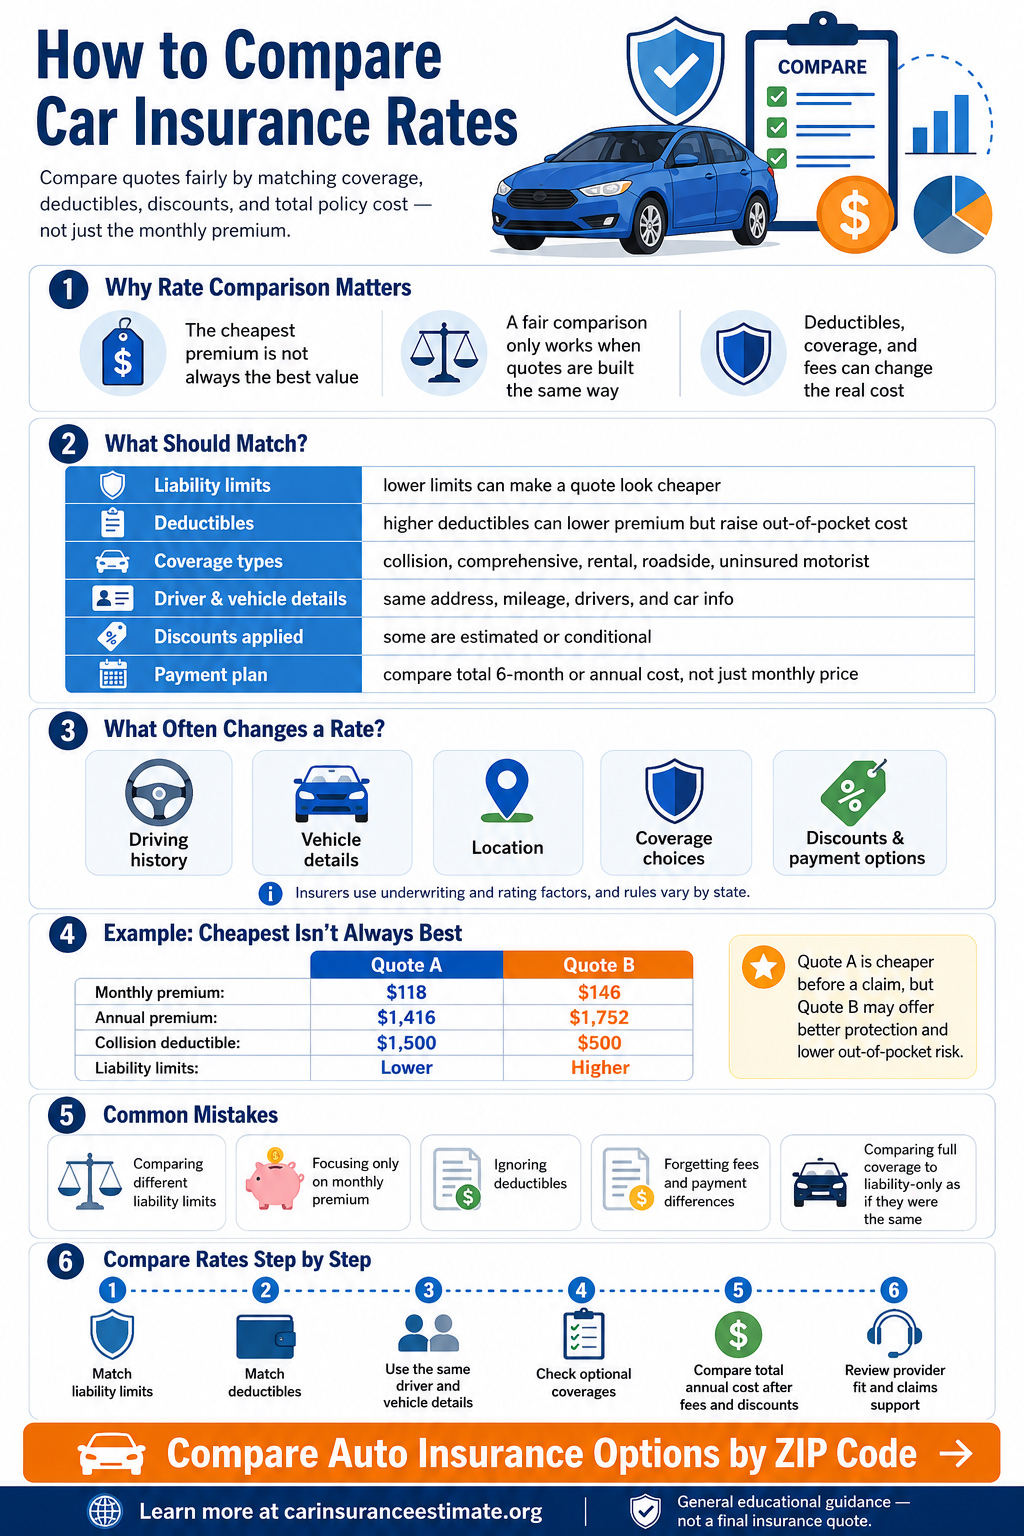
To effectively compare all auto insurance options, you must evaluate three core pillars: coverage breadth, total cost (premiums plus deductibles), and the insurer’s financial stability. Begin by gathering your current policy’s declarations page to use as a baseline, then solicit quotes for identical coverage limits from at least three different providers using a mix of digital aggregators and direct carrier sites.
Comparing auto insurance in 2026 requires more than a simple price check. As vehicle technology becomes more complex and repair costs remain high, the "cheapest" policy often results in the highest out-of-pocket expenses during a claim. A truly comprehensive comparison looks at how an insurer handles claims, the transparency of their digital tools, and whether their specific discount structures align with your driving habits.
The State of the Auto Insurance Market in 2026
As we navigate 2026, the auto insurance landscape has been fundamentally reshaped by two primary factors: the ubiquity of Advanced Driver Assistance Systems (ADAS) and the maturity of telematics-based pricing. While vehicles are safer than ever, the cost to repair sensors, cameras, and lidar arrays has driven property damage liability and collision premiums upward across the board.
Insurers have moved away from traditional actuarial tables that relied solely on age, gender, and zip code. Today, many "all-in" comparisons must account for Usage-Based Insurance (UBI). Most major carriers now prioritize data from your vehicle’s internal computer or a smartphone app to determine your risk profile. When comparing policies, you are no longer just comparing companies; you are comparing how much privacy you are willing to trade for potential premium discounts.
Furthermore, the rise of electric vehicles (EVs) has created a specialized niche in the market. If you are comparing insurance for an EV in 2026, you will notice significant variance between legacy insurers and newer, tech-focused underwriters who may have better data on battery replacement costs and specialized repair networks.
Essential Coverage Components to Compare
When you "compare all" insurance, you must ensure you are looking at equivalent products. Comparing a "basic" policy from one company to a "premium" policy from another is a common error that leads to poor financial decisions. Focus on these specific components:
Liability Coverage (BI/PD)
This is the foundation of every policy and is legally mandated in nearly every state. It consists of Bodily Injury (BI) and Property Damage (PD). In 2026, the standard "minimum" limits (e.g., 25/50/25) are often insufficient to cover the cost of a multi-car accident involving modern luxury vehicles or high medical bills. Experts generally recommend limits of at least 100/300/100 ($100,000 per person, $300,000 per accident for BI, and $100,000 for PD).
Collision and Comprehensive
Collision covers damage to your vehicle from an accident with another car or object, regardless of fault. Comprehensive covers "acts of God," such as theft, fire, vandalism, or weather damage. When comparing these, pay close attention to the deductible. A lower premium often hides a $1,500 or $2,000 deductible, which could be devastating if you don't have that cash on hand during an emergency.
Uninsured and Underinsured Motorist (UM/UIM)
Despite legal requirements, a significant percentage of drivers remain uninsured or carry only state-minimum coverage. UM/UIM protects you if you are hit by one of these drivers. In some jurisdictions, this coverage also applies to hit-and-run incidents. This is a critical comparison point, as some "budget" insurers may gloss over these options to present a lower initial quote.
Personal Injury Protection (PIP) and MedPay
Depending on whether you live in a "no-fault" state, PIP can be mandatory. It covers medical expenses for you and your passengers. When comparing, check if the insurer offers "excess medical" coverage, which can be a vital secondary layer if your primary health insurance has high out-of-pocket costs.

Evaluating Provider Reputation and Financial Strength
A low premium is worthless if the company lacks the liquidity to pay claims or provides a frustrating customer experience. To truly compare all auto insurance companies, you must look at third-party assessments of their corporate health and service quality.
- Financial Rating Agencies: Use A.M. Best or Standard & Poor’s to check an insurer's financial strength rating. Aim for companies with an "A" rating or higher. This ensures the company can survive a catastrophic year with high claim volumes.
- Claims Satisfaction Research: Organizations like J.D. Power release annual studies on auto insurance claims satisfaction. These reports analyze how quickly companies settle claims and the quality of their communication throughout the process.
- Complaint Index: The National Association of Insurance Commissioners (NAIC) provides a Consumer Complaint Index. A score of 1.0 is the national average; a score below 1.0 indicates fewer complaints than average, which is a strong signal of reliable service.
Comparison Table: Top Carriers by Segment (2026 Outlook)
The following table compares the typical strengths of major insurance archetypes found in the 2026 market.
| Provider Category | Ideal For | Key Strength | Potential Drawback |
|---|---|---|---|
| National Giants (e.g., State Farm, Geico) | General drivers wanting stability. | Robust mobile apps and massive local agent networks. | May not offer the most aggressive UBI discounts for low-mileage drivers. |
| Digital-First Insurers (e.g., Lemonade, Root) | Tech-savvy users and urban dwellers. | Extremely fast claims processing via AI and sleek interfaces. | Limited human support; premiums can fluctuate rapidly based on app data. |
| Mutual Insurers (e.g., Amica, USAA) | Long-term policyholders and military families. | High customer loyalty and potential for policyholder dividends. | Stricter eligibility requirements (e.g., military affiliation or high credit scores). |
| Specialty/Regional (e.g., Erie, Auto-Owners) | Drivers in specific states (Midwest/East Coast). | Highly personalized service and deep knowledge of local laws. | Limited availability; may lack advanced telematics features. |
The Mechanics of Comparing Quotes
To get the most accurate results when you compare all auto insurance, follow a systematic approach. Digital comparison tools (aggregators) are a great starting point, but they should not be your final destination.
Step 1: Information Gathering
You will need your Vehicle Identification Number (VIN), the social security numbers of all household drivers, and a copy of your current "Dec Page" (Declarations Page). This ensures you are inputting identical data across different platforms.
Step 2: Use an Aggregator for the "Wide Net"
Websites that aggregate quotes can give you a ballpark range of what 10–20 different companies might charge. However, be aware that these are often "lead generation" sites. Use a dedicated email address to avoid cluttering your primary inbox with marketing follow-ups.
Step 3: Direct Quotes for Accuracy
Aggregators often use "soft pulls" or estimated data. Once you identify the top three most competitive companies from the aggregator, visit their official websites directly. Re-enter your data to get a "firm" quote. This is where you can fine-tune your telematics preferences and specific endorsements, like glass coverage or roadside assistance.
Step 4: Consult an Independent Agent
Independent agents work with multiple carriers that do not always appear on comparison websites. They can often find "niche" insurers that specialize in your specific demographic or vehicle type, potentially uncovering lower rates that aren't available to the general public through direct search.
Common Mistakes When Comparing Auto Insurance
Avoid these pitfalls to ensure you don't end up with a policy that leaves you vulnerable:
- Ignoring the "Steps" in Liability: Many people see "50/100" and think they are well-covered. In 2026, with the average new car price exceeding $50,000, a $25,000 property damage limit is dangerously low. If you total someone else's vehicle, you will be personally liable for the remaining balance.
- Overlooking "Gap" Insurance: If you are financing a vehicle, compare the cost of "Gap" coverage. If your car is totaled, standard insurance pays the Actual Cash Value (ACV). If you owe more on your loan than the ACV, Gap insurance covers the difference. Buying this through your insurer is almost always cheaper than buying it through a dealership.
- Forgetting to Update Annual Mileage: If your work habits have changed (e.g., moving to a fully remote role), your premium should reflect that. Low-mileage drivers often pay significantly more than they should because they haven't updated this metric during their comparison.
- Focusing Solely on the Monthly Payment: A policy that costs $80 a month with a $2,500 deductible is often "more expensive" in the long run than a $110 a month policy with a $500 deductible, especially if you live in a high-traffic area prone to minor fender benders.
Specialized Comparison: Rideshare and Delivery Coverage
If you use your vehicle for companies like Uber, Lyft, or DoorDash, a standard personal auto policy is likely insufficient. Most personal policies explicitly exclude coverage the moment you log into a commercial app.
When comparing policies in 2026, specifically look for Rideshare Endorsements. Some companies offer this as a simple add-on for a few dollars a month, while others may require you to switch to a commercial policy. Failing to compare this specific detail can lead to a total denial of claims if an accident occurs while the app is active.
Frequently Asked Questions
Does checking multiple insurance quotes hurt my credit score?
In the United States, insurance companies typically perform a "soft pull" on your credit report. This allows them to see your insurance-focused credit score without impacting your official FICO score. Unlike applying for a credit card or a mortgage, comparing insurance quotes will not lower your credit rating.
Why is there such a large price difference between companies for the same coverage?
Insurers use proprietary algorithms to calculate risk. One company might have had a high number of claims in your specific zip code last year and raised rates to compensate. Another company might be trying to grow its market share in your region and is offering "loss leader" pricing to attract new customers. This is why comparing "all" options is essential every 12 to 18 months.
Can I change my insurance mid-term if I find a better deal?
Yes. You are not locked into your policy until the expiration date. If you find a better rate while comparing, you can switch immediately. Your current insurer is legally required to refund the "unearned premium"—the portion of the premium you paid for the days remaining on the policy—though some may charge a small "short-rate" cancellation fee.
What is the "Telematics Discount" and should I use it?
Telematics involves using a device or app to track your driving behaviors (braking, acceleration, speed, and time of day). While it can offer discounts of 10% to 40%, it also gives the insurer a window into your privacy. In 2026, some insurers have started using this data to increase rates for aggressive drivers, so read the terms carefully before opting in.
Are online comparison sites better than human agents?
Online sites are superior for speed and broad market overviews. Human agents (specifically independent ones) are superior for complex situations, such as bundling multiple properties, insuring high-value assets, or navigating a driving record with multiple recent infractions. A hybrid approach—using a site first, then confirming with an agent—is often the most effective strategy.
How does my credit score affect my auto insurance comparison?
In most states (except California, Hawaii, Massachusetts, and Michigan), insurers use a credit-based insurance score to help predict the likelihood of a claim. Drivers with higher credit scores typically receive significantly lower premium offers. If you have improved your credit score recently, re-comparing your insurance options could lead to substantial savings.
Final Recommendation for 2026
To achieve the best balance of cost and protection, perform a comprehensive comparison annually. Start by using an independent comparison tool to identify the top three value-leading carriers for your profile. Then, contact an independent agent to see if they can beat those rates with a regional or mutual insurer. Always prioritize a 100/300/100 liability limit and a deductible that aligns with your emergency savings. By treating insurance as a dynamic financial product rather than a "set and forget" utility, you ensure that you are never overpaying for the security of your vehicle and assets.
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
