
Deciding when to cancel full coverage auto insurance depends on the relationship between your vehicle's actual cash value (ACV) and the cost of your premiums. Generally, you should consider dropping collision and comprehensive coverage when the annual cost of these premiums, combined with your deductible, exceeds the potential payout you would receive from your insurer after a total loss.
In the current 2026 automotive landscape, vehicle technology has advanced significantly, making repair costs higher than ever. Consequently, the decision to transition from "full coverage" to "liability-only" requires a nuanced analysis of your financial health, the specific market value of your vehicle, and your personal risk tolerance.
Understanding "Full Coverage" in the 2026 Context
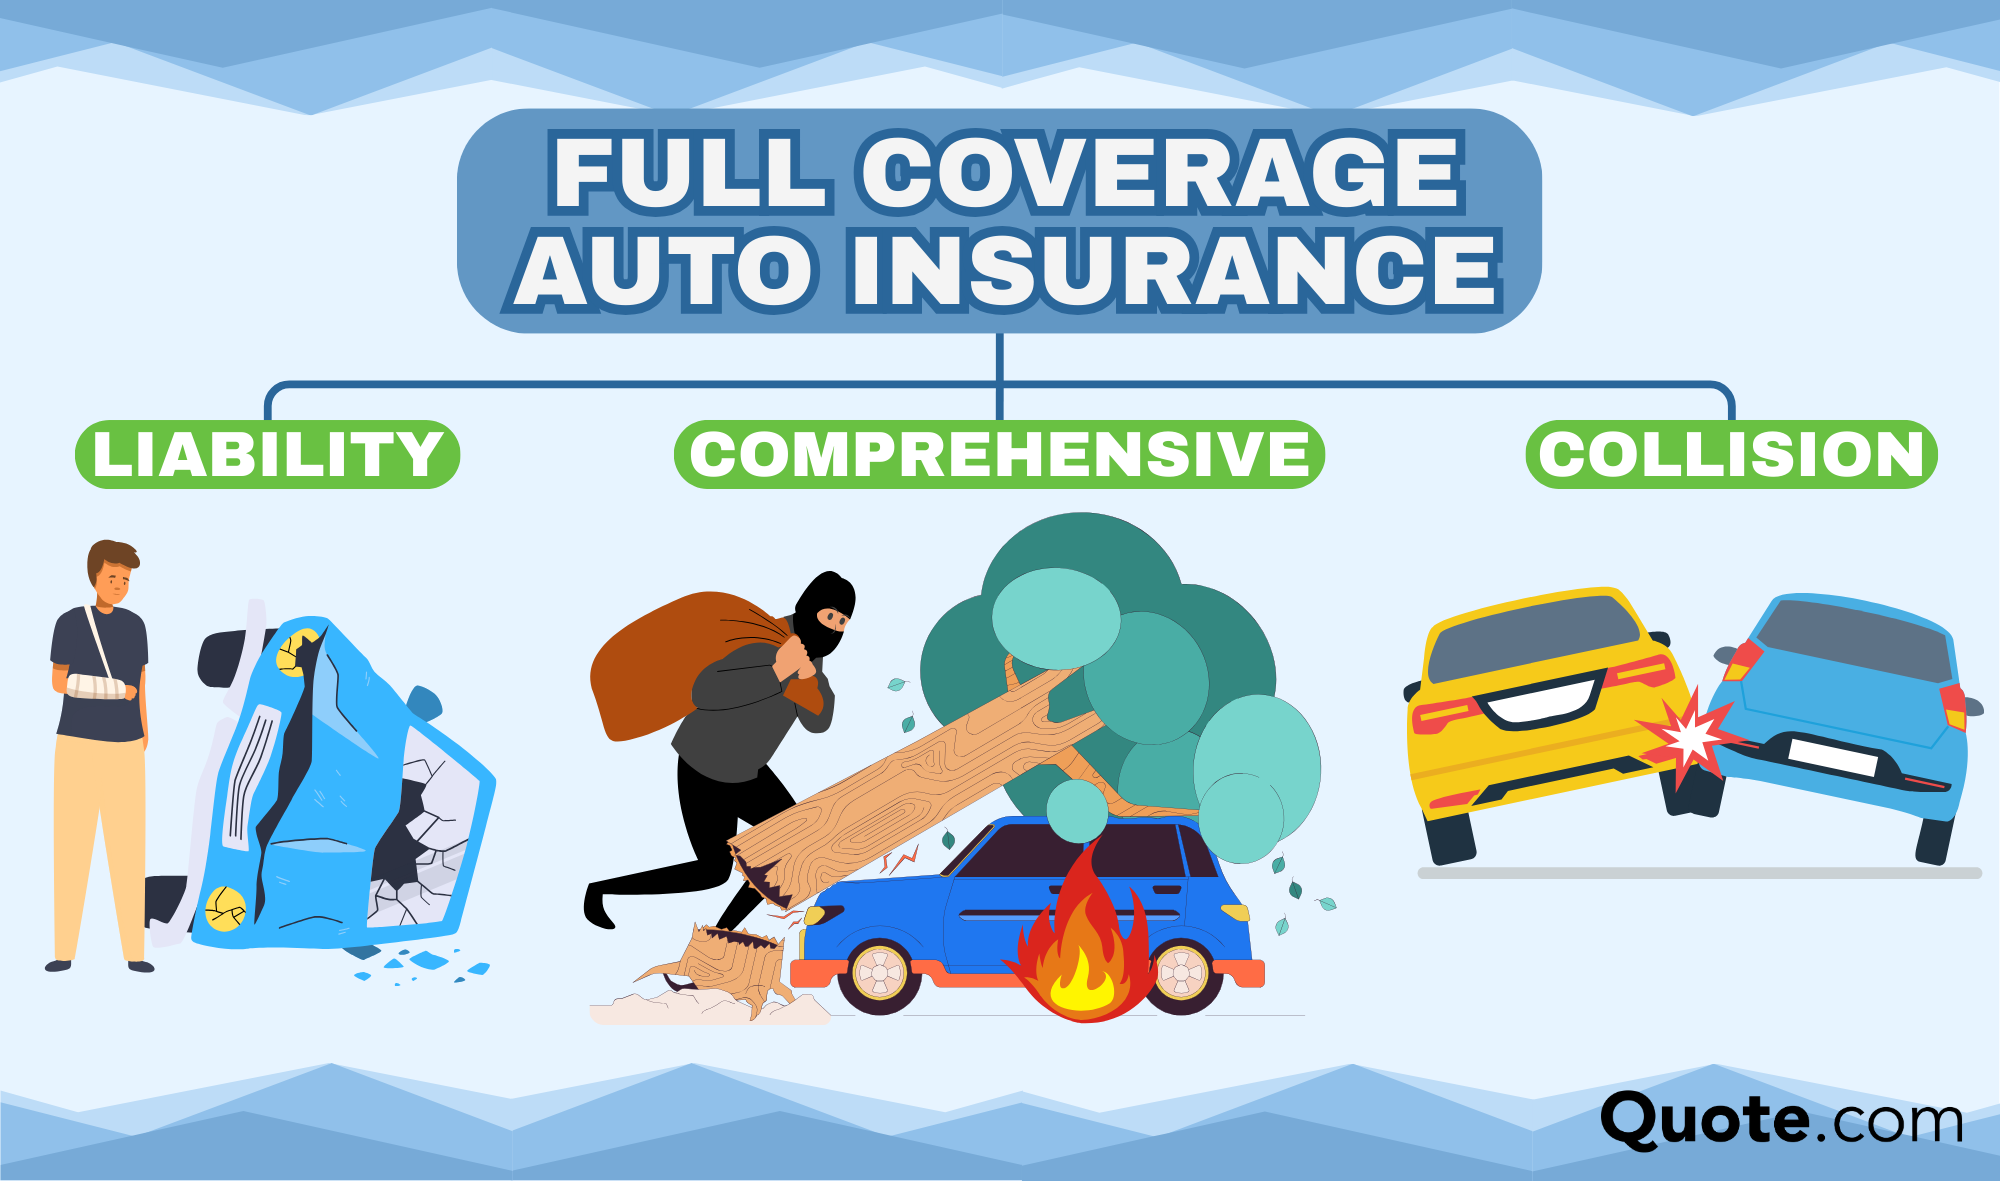
Before determining when to cancel these protections, it is essential to define what "full coverage" actually entails. In the insurance industry, there is no legal definition for "full coverage." Instead, it is a colloquial term used to describe a policy that includes liability insurance (required by law) plus two optional physical damage coverages: Collision and Comprehensive.
Collision Coverage
Collision insurance pays for damage to your vehicle resulting from an accident with another car or a stationary object, regardless of who is at fault. In 2026, as vehicles are increasingly equipped with sophisticated Advanced Driver Assistance Systems (ADAS), even minor fender benders can result in repair bills exceeding $5,000 due to the cost of calibrating sensors and cameras.
Comprehensive Coverage
Comprehensive insurance covers damage caused by "acts of God" or events outside of your control. This includes theft, vandalism, fire, hail, and collisions with animals. As climate-related events have become more frequent and severe in recent years, comprehensive coverage remains a vital shield for many drivers, even those with older vehicles.
The Mathematical Thresholds for Cancellation
The primary reason to cancel full coverage is that it no longer makes financial sense to pay for a benefit that the insurance company will likely never fully pay out. Insurance companies will only pay up to the Actual Cash Value (ACV) of the vehicle, minus your deductible.
The 10% Rule
A long-standing industry benchmark is the "10% Rule." This guideline suggests that if the annual cost of your collision and comprehensive coverage exceeds 10% of your car's book value, it is time to consider dropping them. For example, if your car is worth $6,000 and the combined premium for collision and comprehensive is $700 per year, you are paying nearly 12% of the car's value annually.
The "Cost-to-Benefit" Calculation
To perform a more precise 2026-specific calculation, use the following formula:
- Determine your vehicle’s ACV (using resources like Kelley Blue Book or NADA Guides).
- Subtract your deductible from the ACV.
- Subtract the annual cost of the collision and comprehensive premiums.
If the resulting number is negligible or negative, you are effectively "upside down" on your insurance investment. You are paying for a level of protection that provides a very small maximum potential payout.
Key Factors Influencing the Decision
While the math provides a baseline, several qualitative and environmental factors in 2026 influence whether you should pull the trigger on canceling coverage.
1. Vehicle Age and Mileage
Age was once the primary metric, but in 2026, mileage and the condition of high-tech components are often more relevant. A 10-year-old vehicle with low mileage might still command a high ACV, whereas a five-year-old vehicle used for high-volume delivery work might have depreciated to the point where full coverage is wasteful.
2. Personal Emergency Fund Status
The most critical question is: Can you afford to replace your vehicle tomorrow without an insurance check? If you have a robust emergency fund that can cover the cost of a replacement vehicle (or a significant down payment), you can afford the risk of dropping full coverage. If losing your car would mean losing your ability to get to work without any way to buy a new one, you should likely keep the coverage regardless of the math.
3. The "Repairability" Factor
Modern vehicles in 2026 often utilize specialized materials like carbon fiber or high-strength aluminum. If your vehicle requires specialized shops for repairs, the labor rates will be significantly higher. When you drop collision coverage, you are assuming 100% of the risk for these high-cost repairs.
4. Deductible vs. Value
If you have a $1,000 deductible on a car worth $3,000, your insurance company will only ever pay you a maximum of $2,000 in the event of a total loss. After factoring in the premiums you paid over the year, the "net benefit" might be less than $1,500.
When You Are Contractually Obligated to Keep Full Coverage
There are specific scenarios where you do not have the choice to cancel full coverage, regardless of the vehicle's value.
- Leased Vehicles: Leasing companies own the vehicle and will always require you to maintain high levels of collision and comprehensive coverage to protect their asset.
- Financed Vehicles: If you have an outstanding auto loan, the lienholder (the bank or credit union) will require full coverage. If you drop it, the lender may purchase "force-placed insurance," which is significantly more expensive and provides less protection for you.
- Business Use: If your vehicle is used for commercial purposes, specific business insurance requirements may mandate comprehensive and collision protection to cover assets essential to operations.
Evaluating the Risks of 2026: Parts Shortages and Inflation
As we move through 2026, the cost of used cars remains higher than historical averages, though it has stabilized from previous peaks. However, the cost of parts and skilled labor continues to rise. When you cancel full coverage, you are not just gambling on not having an accident; you are gambling on the stability of the automotive repair market. If you drop coverage and have a minor accident, you may find that the cost to repair the vehicle is higher than the car's actual value, effectively totaling the vehicle out of your own pocket.
Comparison Table: When to Keep vs. Drop Coverage
| Factor | Keep Full Coverage | Consider Dropping |
|---|---|---|
| Vehicle Value | Above $7,000 - $10,000 | Below $5,000 |
| Annual Premium | < 10% of Vehicle Value | > 10% of Vehicle Value |
| Deductible | Low ($250 - $500) | High ($1,000+) |
| Financial Buffer | No savings for a replacement | Sufficient savings to buy a new car |
| Lien Status | Financed or Leased | Owned outright (Title in hand) |
| Vehicle Tech | High (EV, ADAS, Sensors) | Low (Manual systems, older tech) |
Strategies Before Canceling Entirely
If you are on the fence, you don't necessarily have to jump straight to liability-only. There are intermediate steps to reduce costs while maintaining some protection.
Raise Your Deductible
Increasing your deductible from $500 to $1,000 or $1,500 can significantly lower your monthly premium. This allows you to keep coverage for catastrophic losses (like a total theft) while you take on the risk for smaller, more manageable repairs.
Drop Only Collision
In some cases, it makes sense to keep comprehensive but drop collision. Comprehensive coverage is typically much cheaper than collision. If you live in an area prone to hail or high theft rates but are a very safe driver with a short commute, keeping comprehensive provides a safety net against "unavoidable" risks for a fraction of the cost.
Verify "Actual Cash Value" Frequently
Insurance companies use proprietary software to determine ACV, but you can get a close estimate by checking the National Automobile Dealers Association (NADA) values. In 2026, ensure you are looking at the "Clean Trade-In" or "Private Party" value, as insurance payouts rarely match the "Retail" price you see on a dealer's lot.
How to Properly Cancel Your Coverage
Once you have decided to drop full coverage, the process must be handled correctly to avoid gaps or legal issues.
- Verify Title Status: Ensure you have the physical title or electronic confirmation that the lien has been released.
- Contact Your Agent: Inform your provider that you wish to remove "Physical Damage" coverage. Specify that you want to maintain your state-mandated liability limits.
- Confirm in Writing: Always get a revised "Declarations Page" showing the new coverage levels and the lower premium.
- Reallocate Savings: A smart financial move is to take the money you save on premiums and deposit it into a dedicated "car fund." This self-insurance strategy ensures that if an accident does happen, the money is already there.
Common Pitfalls to Avoid
The most common mistake drivers make in 2026 is dropping coverage based on the vehicle's age alone. A high-end luxury vehicle that is 10 years old may still have a replacement cost of $20,000, making full coverage essential. Conversely, a budget-friendly compact car may lose its value much faster.
Another pitfall is ignoring Uninsured/Underinsured Motorist Property Damage (UMPD). If you drop collision coverage and are hit by an uninsured driver, you may have no recourse for repairing your car unless you have UMPD. Check your state laws through the National Association of Insurance Commissioners (NAIC) to see if this coverage is available and recommended for you.
FAQs
If I cancel full coverage, am I still covered if someone else hits me?
Yes, if the other driver is at fault and has insurance, their Liability Coverage (Property Damage) will pay for your repairs. However, if they are uninsured or it was a hit-and-run, you will have no coverage for your vehicle unless you have Collision or Uninsured Motorist Property Damage coverage.
How does the 2026 used car market affect this decision?
Because used car prices have remained relatively high, your car might be worth more than you think. This "value retention" actually pushes the timeline for canceling full coverage further out. You should check your car's value every six months to ensure your insurance matches the current market reality.
Can I cancel full coverage if I have a "Title Loan"?
No. Just like a traditional auto loan, a title loan uses your vehicle as collateral. The lender will require you to maintain comprehensive and collision coverage to protect their interest in the asset until the loan is paid in full.
Does dropping full coverage affect my liability rates?
Generally, no. Removing collision and comprehensive changes the "physical damage" portion of your policy but does not directly increase your liability premiums. However, staying with the same insurer after dropping coverage may lead to a loss of certain "multi-coverage" discounts.
Should I drop full coverage on an electric vehicle (EV)?
Be very cautious here. In 2026, EV battery replacement costs remain high. Even a minor underside impact that damages the battery casing could result in a total loss. Unless the EV is very old and the battery health is significantly degraded, keeping full coverage is usually the safer financial move.
Final Recommendation
The decision to cancel full coverage auto insurance is a transition from transferring risk to assuming risk. For most drivers in 2026, the "sweet spot" for cancellation is when the vehicle's value drops below $5,000 and the owner has at least that much saved in a liquid account. If your vehicle is a vital tool for your livelihood and you lack the immediate funds to replace it, the peace of mind provided by collision and comprehensive coverage is often worth the premium, even if the mathematical "10% rule" suggests otherwise.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
