
Selecting an auto insurance provider in Colorado involves more than just meeting the state's minimum liability requirements; it requires evaluating the specific benefits and coverage enhancements offered by various carriers to ensure comprehensive protection. Colorado’s unique regulatory environment and driving conditions—ranging from high-altitude mountain passes to dense urban corridors—make understanding the value-added benefits of insurance policies essential for every motorist.
When researching auto insurance companies in Colorado, prospective policyholders often look for "benefits lists" to distinguish between bare-bones coverage and premium protection packages. These benefits frequently include features such as accident forgiveness, disappearing deductibles, gap coverage, and specialized roadside assistance. Navigating these offerings requires a clear understanding of the Colorado Division of Insurance (DOI) standards, which mandate specific liability minimums while allowing carriers to compete through supplemental coverage options. This guide details how to interpret these benefits and identifies the key factors Coloradans should consider to maximize their policy value in 2026.
Understanding Colorado Auto Insurance Mandates
Before assessing optional benefits, it is critical to understand the foundation of auto insurance in Colorado. According to the Colorado Division of Insurance, all drivers must carry liability insurance to legally operate a vehicle. As of 2026, the statutory minimum coverage limits are $25,000 for bodily injury or death to any one person in any one accident, $50,000 for bodily injury or death to all persons in any one accident, and $15,000 for property damage.
While these minimums satisfy legal requirements, they are often insufficient in the event of a significant accident. When you review an "auto insurance benefits list," you are typically looking at features that extend coverage far beyond these state-mandated floors. Understanding the difference between mandatory coverage and elective benefits allows you to prioritize your budget toward features that offer the most utility for your specific driving habits and financial situation.
Categorizing Common Insurance Benefits
Insurance carriers package their "benefits lists" in various ways, but most fall into three core categories: financial protection, convenience, and loss mitigation.
1. Financial Protection Benefits
These features provide direct monetary relief or shield you from significant out-of-pocket expenses beyond standard coverage.
- Gap Coverage: Essential for drivers with newer vehicles or those with high-interest financing. If your car is totaled, this pays the difference between the vehicle's actual cash value and the amount still owed on the loan.
- Accident Forgiveness: Many carriers offer this to prevent your premiums from spiking after your first at-fault accident, provided you have maintained a clean driving record for a set period.
- Disappearing Deductibles: Some insurers reward safe driving by reducing your collision deductible by a specific amount for every year you remain accident-free.
2. Convenience and Service Enhancements
These benefits aim to streamline the administrative or logistical side of auto insurance.
- Rental Car Reimbursement: Covers the cost of a rental vehicle while your primary car is in the shop for a covered repair.
- Mobile App Integration: Modern benefits include digital ID cards, telematics-based safe driving tracking, and instant digital claim filing.
- Original Equipment Manufacturer (OEM) Parts: Some premium policies guarantee that your vehicle will be repaired using factory-original parts rather than aftermarket equivalents.
3. Loss Mitigation and Safety Features
These benefits are designed to prevent incidents or assist you during roadside emergencies.
- Roadside Assistance: This may include lockout services, battery jumps, flat tire changes, and towing to a nearby service facility.
- New Car Replacement: More comprehensive than gap insurance, this feature covers the cost of replacing your totaled vehicle with a brand-new model of the same make and trim, rather than depreciated value.
Comparing Major Providers in Colorado
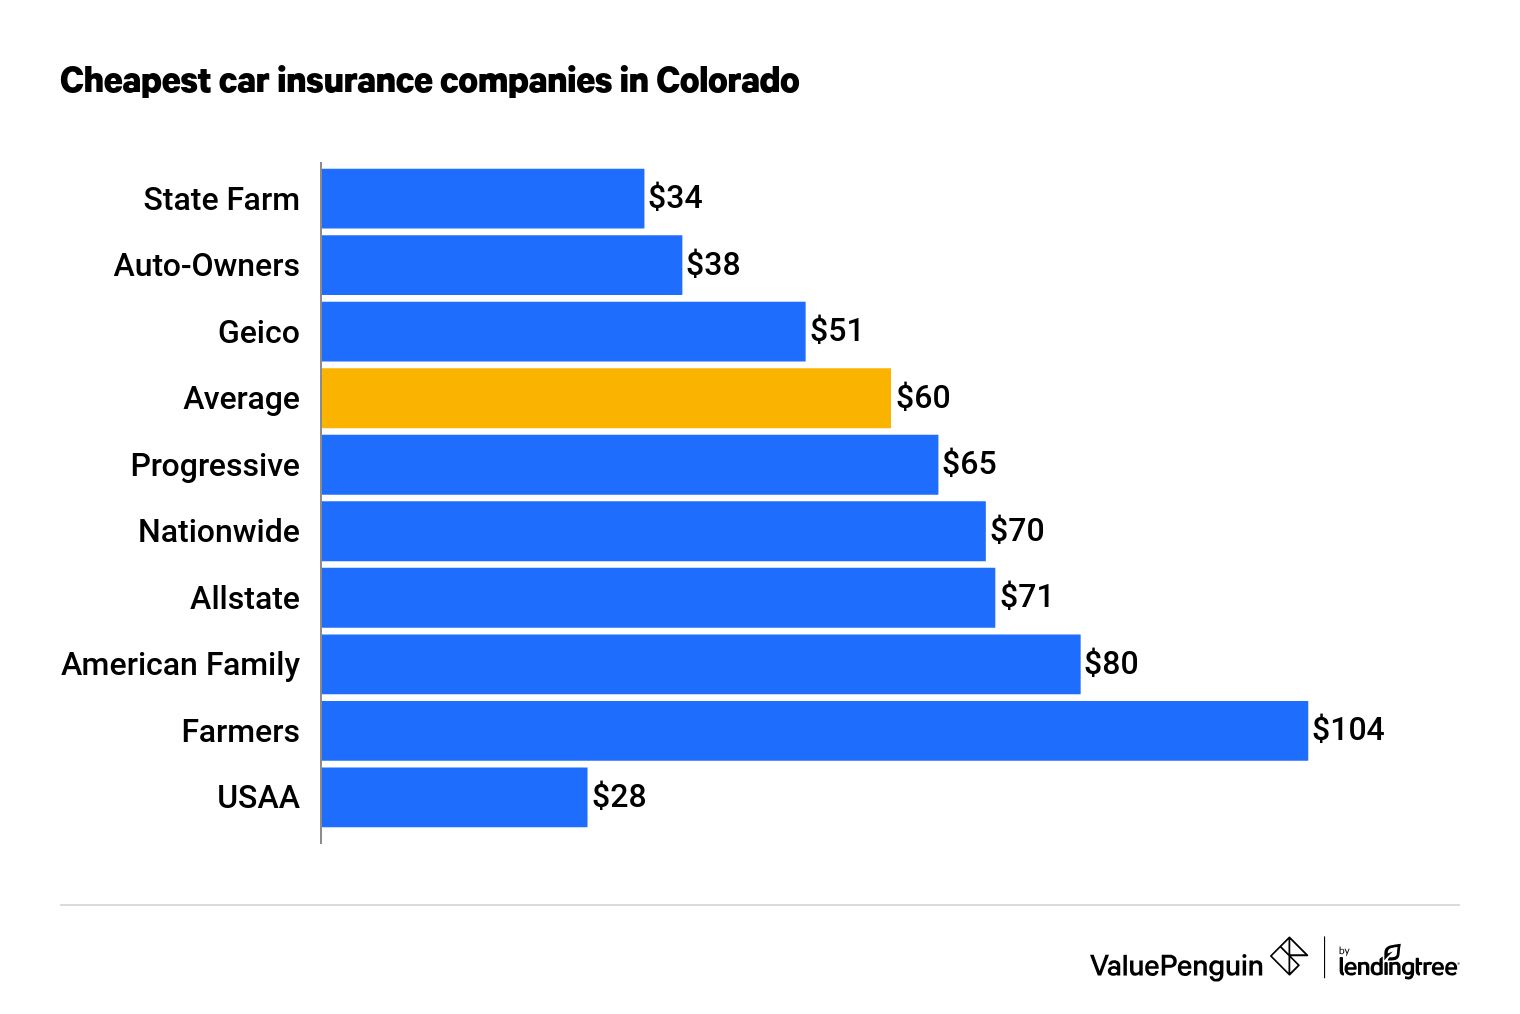
While the specific benefits list will fluctuate based on the underwriter, several major national and regional carriers operate extensively in Colorado. The following table provides a comparison of standard benefits commonly associated with top-tier carriers in the region.
| Benefit Feature | Major Carrier A | Major Carrier B | Major Carrier C |
|---|---|---|---|
| Accident Forgiveness | Optional | Included (Loyalty) | Optional |
| Gap Coverage | Yes | Yes | Yes |
| New Car Replacement | Yes | No | Limited |
| OEM Parts Coverage | Optional | Optional | Yes |
| Roadside Assistance | 24/7 Service | Basic Only | 24/7 Service |
Note: Availability of these benefits is subject to the specific policy terms, the driver’s profile, and the vehicle type. Always request a written schedule of coverages before finalizing your enrollment.
The Role of Telematics in 2026
In 2026, the most significant trend in auto insurance benefits is the shift toward telematics-based programs. Carriers like Progressive (Snapshot), State Farm (Drive Safe & Save), and Allstate (Milewise) offer programs that monitor your driving habits via mobile app or plug-in device.
The benefit of these programs is twofold. First, they provide tangible feedback on your driving behavior, such as rapid acceleration, harsh braking, and late-night driving. Second, they can lead to substantial premium discounts. For many Colorado residents, particularly those who work remotely or have low annual mileage, these telematics programs provide a "pay-as-you-drive" benefit that significantly lowers costs compared to traditional flat-rate policies.
Evaluating Benefits Against Colorado Driving Risks
When reviewing the benefits list of a potential insurer, consider the environmental factors prevalent in Colorado.
Mountain and Winter Driving
If you frequently traverse mountain passes such as I-70 or Vail Pass, roadside assistance that includes winching or specialized towing in remote areas is a high-value benefit. Standard roadside assistance may not cover heavy-duty recovery in snowy or off-road conditions. Check if your insurer’s roadside assistance benefit has limitations on tow distance or the type of terrain they service.
Hail and Weather Damage
Colorado is well-known for severe hail events that can cause significant body damage. Comprehensive coverage is not a "benefit" in the traditional sense, but the inclusion of "glass coverage" or "zero-deductible hail repair" is a highly desirable benefit in this region. Review your policy to see if the insurer offers a separate, lower deductible specifically for glass and hail-related claims.
Steps to Verify Benefits Before Purchasing
Never assume a benefit is included based on general marketing materials. To ensure you are getting the coverage you expect, follow these verification steps:
- Request a Specimen Policy: Ask the agent to provide a "specimen policy" or "schedule of coverages." This document contains the actual legal language regarding the benefits.
- Verify Exclusions: Every benefit has an exclusion. For example, gap coverage may not apply if the vehicle has been modified with aftermarket equipment. Read the fine print of the benefit.
- Check Geographic Limits: Confirm that benefits such as roadside assistance are valid throughout the entire state of Colorado and across state lines if you travel frequently.
- Confirm Renewability: Determine if the benefits are guaranteed for the life of the policy or if they can be rescinded at the insurer’s discretion during a renewal period.
Common Mistakes When Choosing Insurance
One of the most frequent errors consumers make is prioritizing the monthly premium cost over the benefits package. While a lower premium is attractive, it may come at the expense of necessary benefits that would save you thousands of dollars in the event of a total loss or serious accident.
Another mistake is failing to bundle. Many Colorado insurers offer significant "multi-policy discounts" if you bundle your auto insurance with home or renters insurance. Often, the savings from the bundle can be applied toward the cost of "upgrading" your auto policy with more robust benefits.
FAQ: Frequently Asked Questions
What is the difference between gap insurance and new car replacement?
Gap insurance only pays the difference between your loan balance and the car's actual cash value at the time of an accident. New car replacement, however, pays to buy you a brand-new vehicle of the same model and trim level, regardless of the depreciated value of your totaled car.
Is roadside assistance worth it if I have an auto club membership?
It depends on the coverage provided by your club. Some auto insurance roadside assistance plans offer higher reimbursement limits or better integration with your primary policy, which can simplify the claims process during an emergency. Compare the policy language carefully.
Can my insurance company remove a benefit at renewal?
Yes, in most cases, insurance companies can change the terms of optional benefits at the time of policy renewal. Always review your renewal notice to see if any coverages or benefits have been modified or removed.
Do Colorado insurance laws require me to buy full coverage?
Colorado law only requires liability coverage. "Full coverage" is not a legal term but rather an industry term for a combination of liability, collision, and comprehensive coverage. If you are financing your vehicle, your lender will almost certainly require you to maintain "full coverage" until the loan is paid off.
How do I check if my insurance carrier is licensed in Colorado?
You can visit the Colorado Division of Insurance website and use their "Company Search" tool to verify that your insurer is authorized to do business in the state. This is an important step to ensure your policy is backed by a reputable firm subject to state regulatory oversight.
Next Actions
To begin your search for the right auto insurance in Colorado:
- Gather your current declarations page to compare your current coverage levels against the market.
- Identify which "pain points" you encounter most often, such as mountain driving, high-mileage commuting, or aging vehicle concerns.
- Contact at least three different insurers—including a mix of large national carriers and local captive agents—to request a personalized quote that explicitly lists the supplemental benefits.
- Compare the "Total Value" rather than just the "Total Price," factoring in the cost of potential out-of-pocket expenses that these specific benefits would mitigate.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
