The Life Insurance Mortgage Protection Script Explained: A Professional Masterclass

A life insurance mortgage protection script is a structured communication framework designed to help insurance agents guide homeowners through the process of protecting their primary residence from foreclosure due to death, disability, or critical illness. These scripts prioritize identifying a client's specific financial vulnerabilities and presenting simplified-issue term life insurance as a targeted solution for mortgage debt.
Mortgage protection insurance (MPI) remains one of the most resilient niches within the life insurance industry. As we navigate the economic landscape of 2026, the complexity of household debt and the rising cost of housing have made these scripts more relevant than ever. For an agent, the script is not merely a set of lines to be read; it is a psychological roadmap that moves a prospect from a state of passive concern to one of active financial protection.
The Psychology Behind the Mortgage Protection Pitch
Understanding the "why" before the "how" is essential for any professional using a mortgage protection script. Unlike broad whole life or universal life policies, mortgage protection is sold on a specific, high-stakes premise: the preservation of the family home.
The script operates on the principle of pain identification and resolution. Most homeowners are aware that their mortgage is their largest monthly expense, but few have a concrete plan for how that expense would be managed if the primary earner were suddenly removed from the equation. The script is designed to bridge the gap between "it won't happen to me" and "I need a plan today."
In 2026, consumer behavior has shifted toward a preference for transparency and speed. Modern scripts have evolved away from high-pressure tactics, focusing instead on "field underwriting" and "consultative selling." This means the script acts as a diagnostic tool, helping the agent determine which carrier and product the client can actually qualify for before a formal application is ever submitted.
The Core Structure of a High-Converting Script
A professional mortgage protection script is typically divided into five distinct phases. Each phase serves a specific purpose in building rapport, establishing authority, and uncovering the client's needs.
1. The Opening and The Hook
The first 30 seconds of a mortgage protection call or meeting are the most critical. Most prospects are contacted because they recently purchased a home or refinanced, which triggered a public record notice or a lead card response.
The hook must immediately reference the "lead source." For example: "I’m calling regarding the request you sent back through the mail (or online) regarding the new mortgage you took out with [Lender Name]." By citing specific details like the lender name or the mortgage amount, the agent establishes immediate credibility and differentiates the call from generic telemarketing.
2. The Discovery Phase (Needs Analysis)
This is the most important part of the script. During discovery, the agent asks open-ended questions to determine the impact of a tragedy. Key questions in a 2026-compliant script include:
- "If something happened to you yesterday, how long could your family continue to make the $2,500 mortgage payment on just your spouse's income?"
- "Do you have any existing coverage through work, and if so, is that policy portable if you leave the company?"
- "Aside from the mortgage, what other debts would your family be left with?"
The goal here is to get the client to articulate the problem in their own words. When the client states, "My family would have to move out within three months," they have effectively sold themselves on the need for the product.
3. The Education and Solution Phase
Once the problem is established, the script shifts to explaining how mortgage protection differs from standard life insurance. In 2026, many mortgage protection policies are "living benefits" riders. The script should explain that these policies don't just pay out upon death; they also provide access to the death benefit if the policyholder suffers a heart attack, stroke, or cancer diagnosis.
The agent explains the three primary types of coverage:
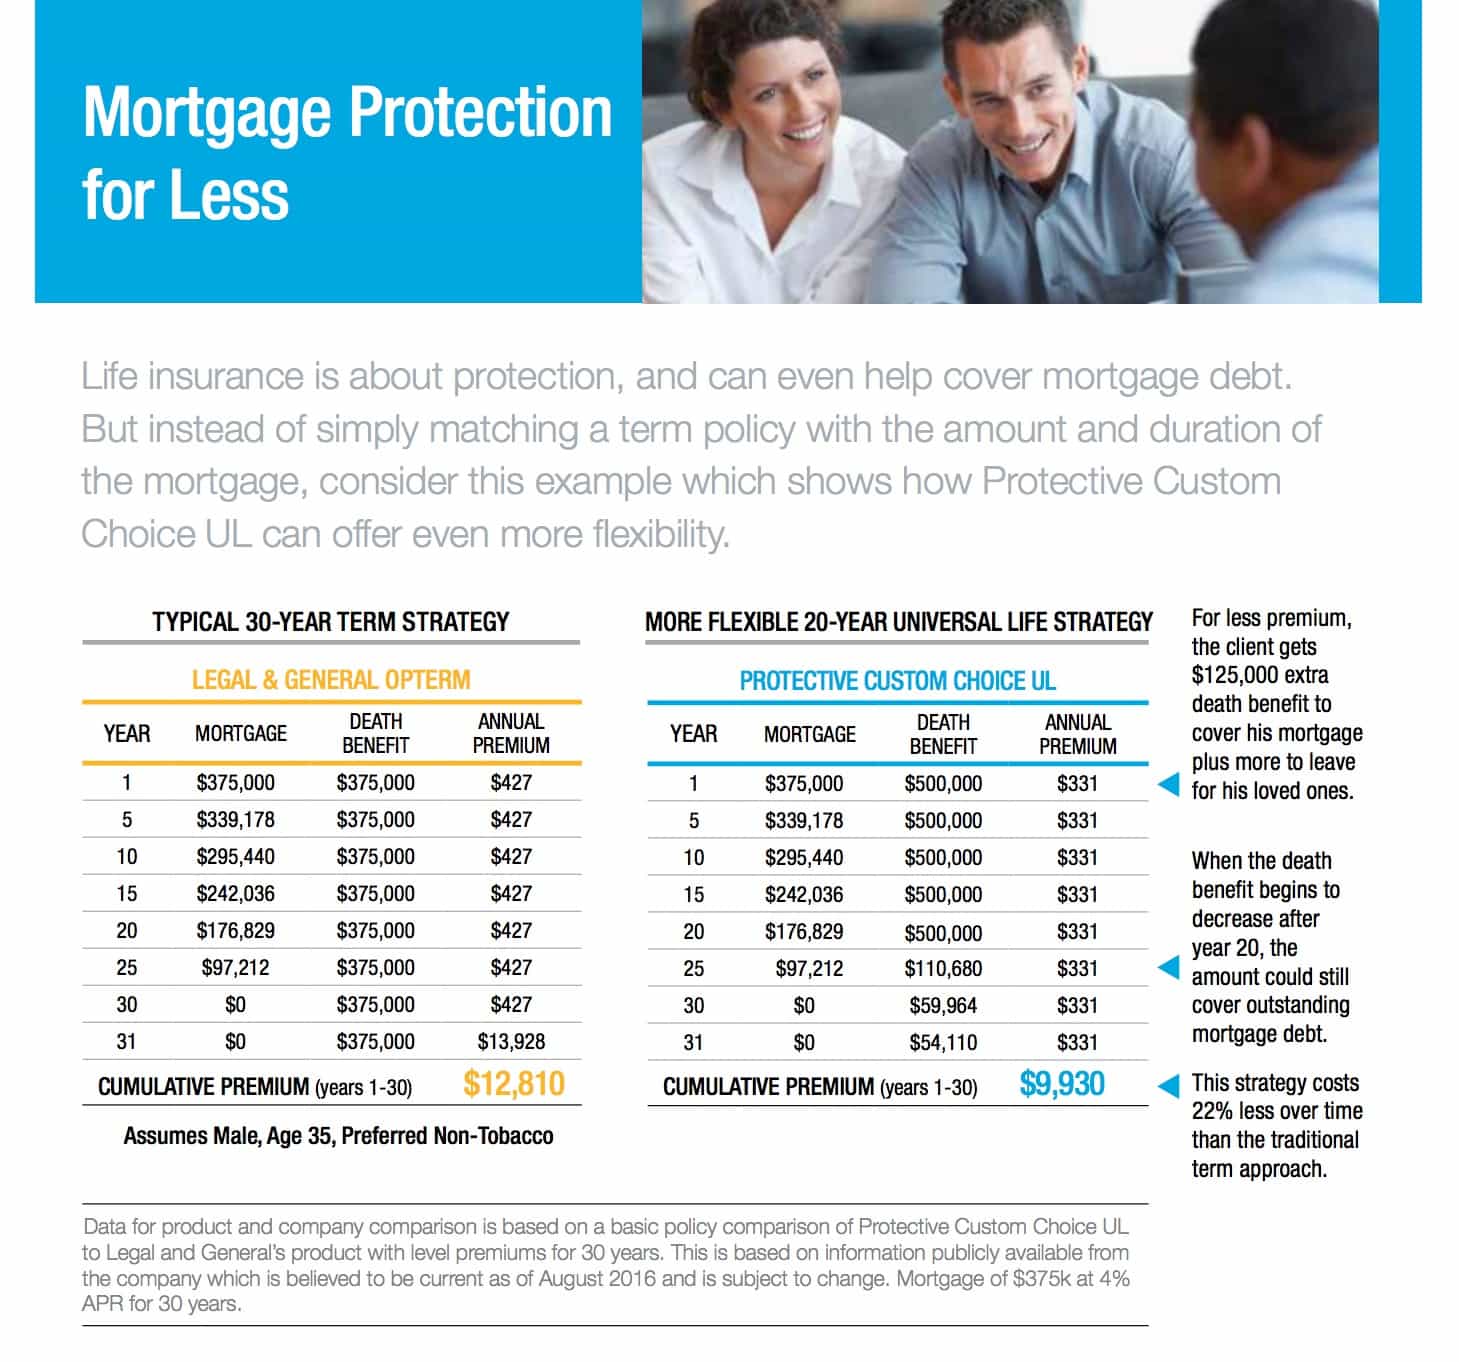
- Full Mortgage Payoff: The policy pays the entire balance of the loan.
- Equity Protection: A smaller policy designed to cover the mortgage for 2-5 years, giving the family time to sell the home or adjust their lifestyle.
- Disability Income/Mtg Payment Protection: Specifically covers the monthly payment if the owner cannot work.
4. Field Underwriting
To maintain high placement rates, the script must include a section on health and lifestyle. This isn't just about collecting data; it's about setting expectations. By asking about prescriptions, height/weight, and tobacco use, the agent avoids the "bait and switch" of quoting a price the client can't get.
5. The Closing (The Three-Option Method)
A successful script never asks, "Do you want to buy this?" Instead, it uses the Alternative Choice Close. The agent presents three different price points (e.g., Full Payoff, 50% Payoff, and 2-Year Pivot Plan) and asks, "Which of these monthly investments fits best into your current budget?"

Comparative Breakdown of Script Delivery Methods
The effectiveness of a mortgage protection script can vary based on the medium of delivery. As of 2026, virtual sales have reached parity with in-person sales, but the scripts require slight adjustments.
| Feature | In-Person (Kitchen Table) | Telesales (Phone) | Virtual (Zoom/Teams) |
|---|---|---|---|
| Rapport Building | High; relies on physical presence and "house vibes." | Low; must be established through tonality and pace. | Moderate; relies on visual cues and screen sharing. |
| Visual Aids | Physical brochures and handwritten charts. | Verbal imagery and "word pictures." | Digital presentations and live quote screens. |
| Length of Script | 45–60 minutes. | 15–25 minutes. | 30–40 minutes. |
| Compliance | Physical signatures required in many states. | Voice signatures or e-mail verification. | Screen-recorded consent and e-sign. |
| Key Advantage | Higher closing rates due to personal connection. | High volume; can reach more prospects per day. | Visual transparency builds trust quickly. |
Handling Common Objections in 2026
No script is complete without a robust section on rebuttal management. In the current economic environment, agents frequently encounter specific objections that require nuanced responses.
"I already have life insurance through my employer."
The Rebuttal: "That’s great that your company provides that benefit. Most people don't realize, however, that work-sponsored insurance is usually 'group term,' which means it stays with the job, not with you. If you were to change careers or if your health prevented you from working, you could lose that coverage exactly when you need it most. Does it make sense to have a small, private policy that stays with your house regardless of your employment status?"
"The price is too high."
The Rebuttal: "I completely understand. My job is to make sure your family is protected, but not at the expense of your current lifestyle. If the full payoff is too much, would it be more helpful to look at a plan that just covers your mortgage payments for the next two years while your family gets back on their feet? That would bring the cost down significantly. Would you like to see what that looks like?"
"I need to think about it."
The Rebuttal: "I hear you. Usually, when someone says they need to think about it, it’s either the price or the product itself. Which one is it for you? Keep in mind, my job is just to see if the insurance companies will even approve you first. We aren't making a final decision today; we are just seeing what you're eligible for. Shall we see if you qualify first?"
Regulatory Compliance and Ethical Considerations
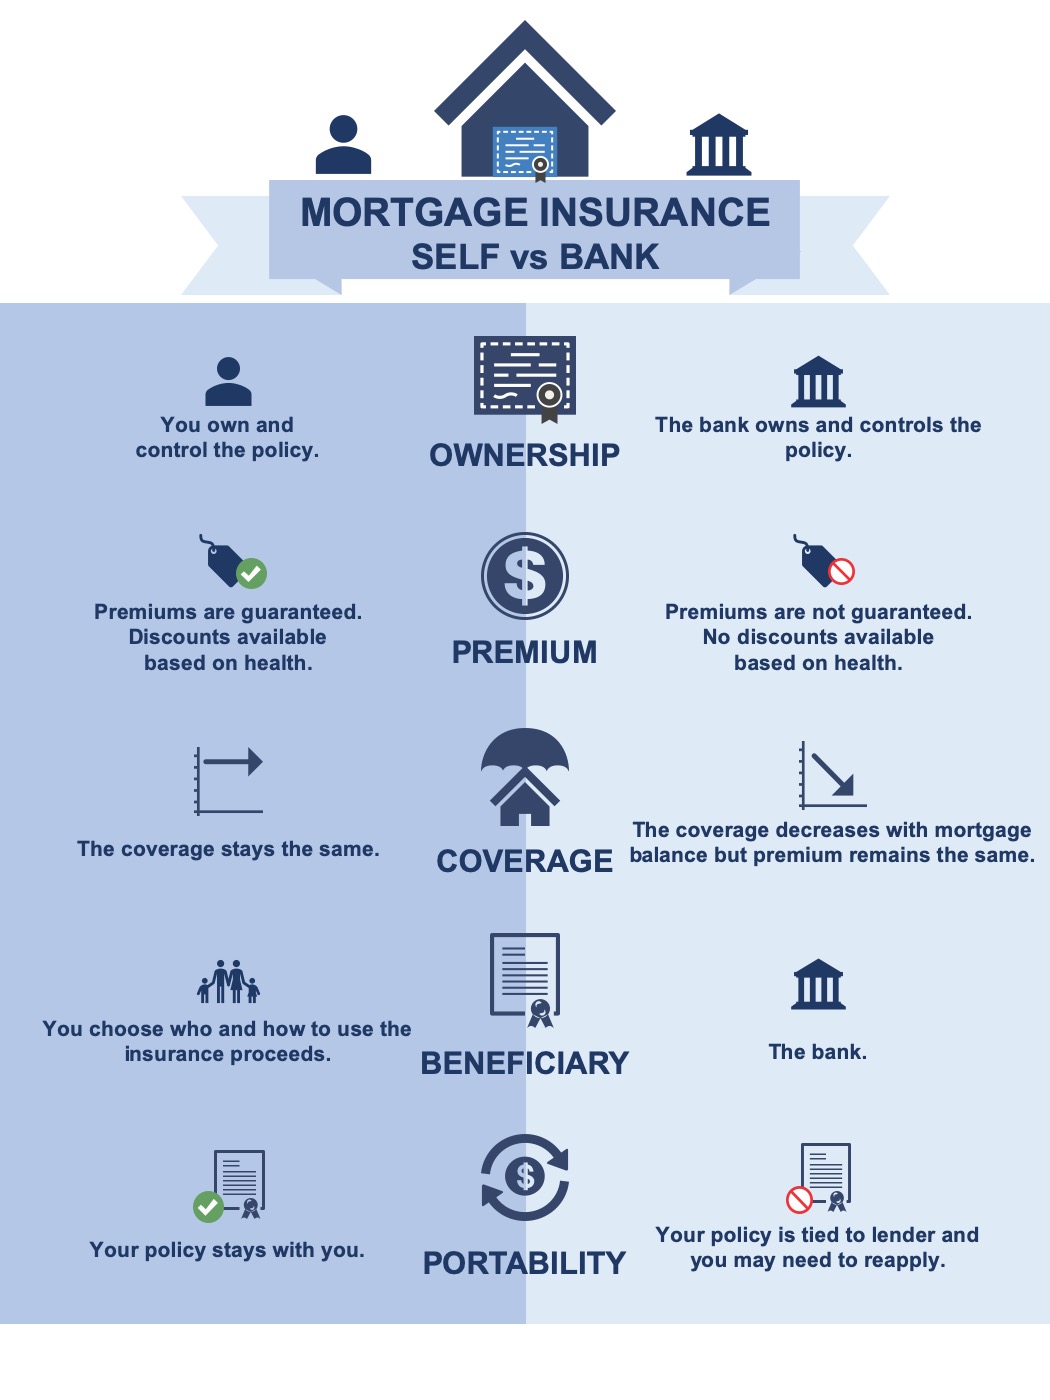
In 2026, the National Association of Insurance Commissioners (NAIC) and state-level regulators have increased scrutiny on mortgage protection sales to ensure "suitability." A script must never imply that the insurance is required by the lender to keep the loan, nor should it be confused with Private Mortgage Insurance (PMI), which protects the lender rather than the homeowner.
Agents must clearly state:
- They are independent or captive agents, not representatives of the bank.
- The policy is optional.
- The exact nature of the death benefit (e.g., level term vs. decreasing term).
Failure to follow these disclosure requirements can lead to "churning" allegations or the loss of an insurance license. Professional scripts now integrate these disclosures into the introduction to ensure transparency from the first minute of the conversation.
Advanced Strategies: Incorporating Living Benefits
The most significant evolution in mortgage protection scripts over the last few years has been the shift toward Living Benefits. In 2026, selling a policy that "only pays if you die" is considered outdated.
A modern script emphasizes that the homeowner is actually more likely to suffer a critical illness or a disabling injury during the life of a 30-year mortgage than they are to pass away. By framing the policy as "comprehensive mortgage health," agents can justify slightly higher premiums and provide much greater value.
Script Example for Living Benefits: "Mr. Prospect, if you were to have a stroke and couldn't work for six months, the bank would still expect their mortgage payment. This policy allows you to 'accelerate' your death benefit while you are still alive to pay those bills. It's essentially a backup plan for your health as much as it is for your life."
Frequently Asked Questions
What is the difference between mortgage protection and PMI?
Private Mortgage Insurance (PMI) is a fee charged by lenders when a homeowner has less than 20% equity in their home; it protects the lender if the borrower defaults. Mortgage Protection Insurance (MPI) is a life insurance policy owned by the homeowner that pays out to their beneficiaries to cover the mortgage debt in the event of death or disability.
Do I need a medical exam for mortgage protection?
Most mortgage protection policies sold in 2026 use "simplified issue" underwriting. This means there is typically no medical exam or blood draw required. Instead, the insurance company reviews your medical records, prescription history, and motor vehicle reports to make a decision, often within minutes or days.
Can the premium for mortgage protection increase over time?
If the script is based on a "Level Term" policy, the premiums are guaranteed to stay the same for the entire duration of the term (usually 15, 20, or 30 years). However, some older "Decreasing Term" policies or annual renewable terms may have different structures. Always confirm with the agent that the policy is a "Guaranteed Level Premium."
What happens if I pay off my mortgage early?
If you pay off your mortgage early, the life insurance policy remains in force as long as you continue to pay the premiums. Since the policy is not legally tied to the mortgage balance, your beneficiaries will receive the full face value of the policy in cash, which they can use for any purpose, not just housing costs.
Are the benefits from a mortgage protection policy taxable?
Under current 2026 tax laws in the United States, death benefits from a life insurance policy are generally received by beneficiaries free of federal income tax. However, it is always recommended to consult with a tax professional regarding specific estate tax implications for very large policies.
Practical Recommendation for Agents and Homeowners
For agents, the key to mastering the mortgage protection script is internalization, not memorization. When you memorize a script, you sound mechanical. When you internalize it, you can respond naturally to the client's emotions while still hitting the necessary psychological triggers and compliance markers. Practice the "Discovery Phase" more than the "Closing Phase," as a well-executed discovery makes the close inevitable.
For homeowners, use the information in this guide to evaluate the professional you are speaking with. A good agent will spend more time asking about your family's needs and your health history than they will "pitching" a specific price. Ensure that any policy discussed includes living benefits, as these provide the most comprehensive protection for a modern household.
Image Gallery
Select an image to open it in a new tab.





Lars Thomsen
Global Labor Markets and Economic Strategy Editor
