The landscape of auto insurance in the Oakland 94602 ZIP code has undergone a significant transformation leading into 2026, driven by a confluence of inflationary pressures, increased vehicle repair complexity, and localized risk factors. Residents in neighborhoods like Glenview, the Dimond District, and Oakmore are experiencing double-digit premium increases as insurers recalibrate their risk models to account for the heightened costs of medical care, litigation, and sophisticated automotive technology. To maintain affordable coverage, drivers must now navigate a complex market characterized by stricter underwriting and a greater emphasis on telematics and bundled policy discounts.
The State of the Auto Insurance Market in 2026
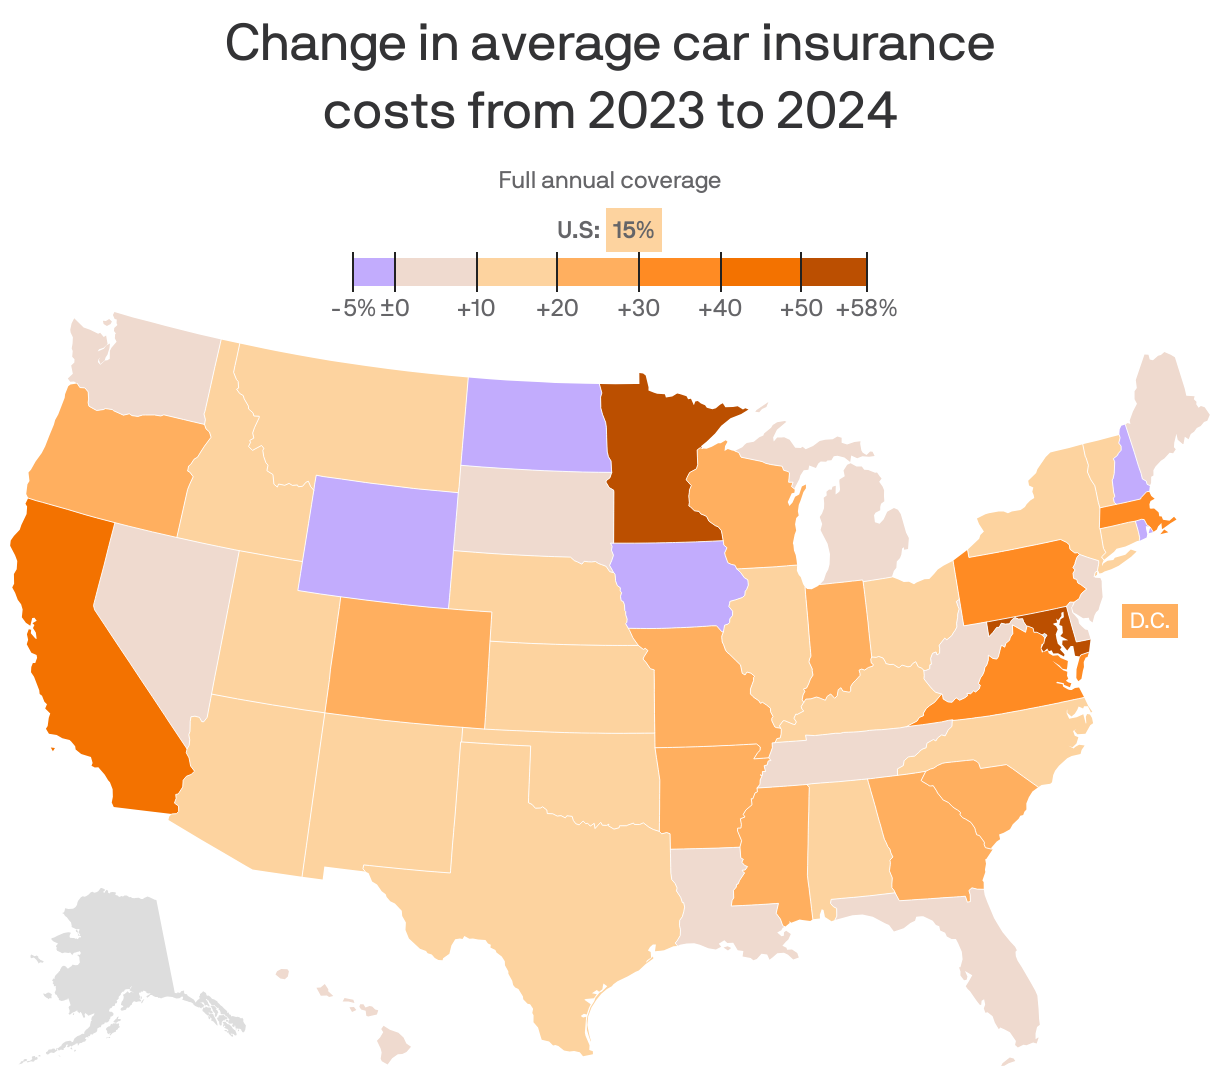
By 2026, the California insurance market has reached a critical inflection point. For several years, the California Department of Insurance (CDI) maintained a relatively tight grip on rate increases, providing a temporary shield for consumers. However, the subsequent "catch-up" period has seen a wave of approved rate hikes as carriers proved that their loss ratios—the ratio of claims paid to premiums collected—were becoming unsustainable.
In Oakland, and specifically within the 94602 ZIP code, these increases have been felt acutely. This area, known for its residential charm and proximity to major commuter arteries like the I-580 and Highway 13, presents a unique risk profile to actuaries. The rising costs are not merely a result of corporate greed but are rooted in the literal cost of "making a claimant whole" after an accident. From the price of a replacement bumper to the hourly rate of a specialized technician in the Bay Area, the baseline expenses for insurance companies have surged.
Localized Risk Factors in Oakland 94602
While statewide trends dictate the general direction of insurance premiums, hyper-local data determines the specific rates for 94602 residents. Several factors unique to this part of Oakland contribute to the shaping of current insurance costs.
Vehicle Theft and Vandalism Trends
Oakland has historically faced challenges with vehicle-related crimes, and the 94602 area is not immune. While neighborhoods like Oakmore and Glenview are primarily residential, their proximity to high-traffic commercial zones makes them targets for "smash-and-grab" thefts and catalytic converter theft. In 2026, insurers use advanced geocoding to assess risk; even if your specific street is quiet, the aggregate data for the 94602 ZIP code reflects the higher frequency of comprehensive claims compared to more rural or suburban districts in California.
Commuter Density and Infrastructure
The 94602 ZIP code serves as a major transit corridor. Drivers merging onto the Warren Freeway (Hwy 13) or navigating the winding roads of Joaquin Miller face higher statistical probabilities of fender-benders and multi-vehicle collisions. The density of parked cars on narrow streets in the Dimond District also increases the likelihood of "hit-and-run" incidents while parked, which drives up the cost of collision and uninsured motorist coverage.
Weather and Geographical Risks
While not as prone to flooding as some coastal areas, the hillsides of 94602 carry risks related to landslides during heavy atmospheric river events—a weather pattern that has become more frequent in recent years. Furthermore, the proximity to the wildland-urban interface in the Oakland Hills adds a layer of complexity to overall risk assessment, as evacuation events can lead to increased localized traffic accidents.
Macroeconomic Drivers Behind the Premium Hikes
The shift in auto insurance pricing is largely fueled by broader economic realities that have accelerated through 2025 and into 2026. Understanding these "invisible" costs helps clarify why even a perfect driving record might not prevent a rate increase.
The Complexity of Modern Vehicle Repair
In 2026, a "minor" collision is rarely minor in terms of cost. Most vehicles on the road in 94602 now feature Advanced Driver Assistance Systems (ADAS). A simple rear-end collision that once required only a new plastic bumper now involves replacing ultrasonic sensors, recalibrating radar modules, and updating software. The labor hours required for these technical calibrations, especially at Bay Area rates, have tripled the average cost of collision repairs over the last decade.
Medical Inflation and Legal Costs
The cost of healthcare continues to outpace general inflation. In the event of an injury-causing accident, the "Bodily Injury" portion of an insurance policy is hit harder than ever. Furthermore, "social inflation"—the trend of rising litigation costs and larger jury awards—has forced insurance companies to increase their reserves. This is particularly relevant in California, where the legal environment is highly active regarding personal injury claims.
The "Parts Gap" and Rental Reimbursement
Supply chain stability has improved since the early 2020s, but the specialized nature of modern parts means that repair wait times can still be lengthy. This extends the duration for which an insurer must pay for a rental car for the claimant. As daily rental rates in Oakland have climbed, the "Loss of Use" component of claims has become a significant financial burden for carriers.
Analyzing the Cost Impact: Coverage Comparison
To visualize how these factors manifest in your bill, consider the following breakdown of how different coverage types have been affected by rising costs in the 94602 area.
| Coverage Type | Primary Cost Driver in 2026 | Estimated Impact on Premium |
|---|---|---|
| Liability (Bodily Injury) | Medical inflation and legal settlements | High - Driven by healthcare costs |
| Collision | ADAS technology and high labor rates | Very High - Complexity of repairs |
| Comprehensive | Catalytic converter and vehicle theft | Moderate to High - Localized crime rates |
| Uninsured Motorist | Higher percentage of lapsed policies | Moderate - Economic pressure on all drivers |
| Rental Reimbursement | Extended repair times and rental fees | Moderate - Cumulative effect of delays |
Regulatory Landscape: Proposition 103 in 2026
The primary law governing insurance in California is Proposition 103, which requires that rates be approved by the Insurance Commissioner before they can be implemented. It also dictates that your "Good Driver" status must be the primary factor in determining your rate, followed by miles driven and years of driving experience.
However, in 2026, we are seeing the results of the "New Normal" in regulation. The California Department of Insurance has allowed carriers to incorporate more "secondary factors" into their pricing, such as the safety features of the vehicle and the specific claim history of the ZIP code. For 94602 residents, this means that while your personal record is paramount, the "neighborhood effect" is exerting more pressure on the final price than it did five years ago.
Strategies for Mitigating Rising Costs
While many factors shaping auto insurance are outside of an individual’s control, there are proactive steps that 94602 residents can take to offset the 2026 price surges.
Embracing Telematics (Usage-Based Insurance)
By 2026, almost every major carrier offers a telematics program—an app or plug-in device that monitors your driving habits. In a high-cost area like Oakland, "opting in" can provide a significant discount (often 10% to 25%) if you avoid hard braking, late-night driving, and speeding. For those who work from home or commute short distances to the Fruitvale BART station, these programs are often the most effective way to lower a premium.
Re-evaluating Deductibles
As repair costs rise, many drivers find that a $500 deductible is no longer economically efficient. Moving to a $1,000 or $1,500 deductible can significantly lower the annual premium. However, this should only be done if the driver has an emergency fund sufficient to cover that higher out-of-pocket cost in the event of an accident.
Bundling and Affinity Discounts
Bundling auto insurance with homeowners or renters insurance remains one of the most reliable ways to secure a discount. Given the rising costs of home insurance in the Oakland Hills and surrounding areas, finding a carrier that will underwrite both can lead to substantial "multi-line" savings. Additionally, check for affinity discounts related to alumni associations, professional organizations, or employers, as these are often overlooked.
Reviewing Annual Mileage
With the persistence of hybrid work models in the Bay Area, many 94602 residents are driving fewer miles than they did in the past. Since California law requires annual mileage to be a top-three rating factor, ensuring your insurer has an accurate (and low) mileage count is vital. If you have shifted from a daily commute to the Silicon Valley to a local Oakland office or remote work, your premium should reflect that reduced risk.
The Role of Uninsured Motorist Coverage in Oakland
One of the most critical components of an auto policy in 2026 is Uninsured/Underinsured Motorist (UM/UIM) coverage. As insurance costs rise, a growing number of drivers across California are either letting their policies lapse or opting for the state-minimum "15/30/5" liability limits, which are woefully inadequate for modern medical costs.
In a dense urban environment like Oakland, the statistical likelihood of being involved in an accident with an uninsured driver is higher than the national average. 94602 residents should view UM/UIM coverage not as an "extra" but as a fundamental protection for their own assets and health. If an uninsured driver hits you on Park Blvd, your own insurance will step in to pay for your medical bills and car repairs, provided you have this coverage in place.
Common Pitfalls to Avoid
When trying to save money on insurance in a high-cost environment, it is easy to make mistakes that lead to long-term financial vulnerability.
- Lowering Liability Limits to the Minimum: California's minimum requirements (currently $15,000 per person/$30,000 per accident) haven't kept pace with inflation. A single night in an Oakland hospital can exceed $15,000. If you are at fault, you are personally responsible for the difference, which can lead to wage garnishment or loss of assets.
- Failing to Report Secondary Drivers: In the 94602 area, multi-generational households are common. If a teenager or a visiting relative frequently drives your car and isn't on the policy, the insurer may deny a claim or cancel the policy for material misrepresentation.
- Ignoring the "Comprehensive" Value: If you drive an older car with low resale value, you might be paying more for comprehensive and collision coverage than the car is worth. Conversely, if you have a newer EV or luxury vehicle common in the Oakmore area, you cannot afford to skip these coverages due to the exorbitant cost of parts.
Frequently Asked Questions
Why is 94602 more expensive than neighboring ZIP codes?
Insurance pricing is based on "territory ratings." While 94602 is highly desirable, its proximity to high-crime corridors and its own density of street-parked cars can result in higher comprehensive claim frequencies than more isolated or gated communities. Additionally, the traffic volume on the 580/13 interchange affects the liability risk for all local residents.
Does my credit score affect my insurance rate in Oakland?
Under California's Proposition 103, insurers are generally prohibited from using credit scores as a primary factor in determining auto insurance rates. This is a significant difference compared to most other states. Your rate is primarily determined by your driving record, miles driven, and years of experience.
How do EV repair costs impact my 94602 premium?
If you drive an Electric Vehicle (EV), your premiums are likely higher because of the "total loss" threshold. Minor battery damage or the specialized labor required for EV high-voltage systems can make repairs significantly more expensive than internal combustion engines. This "EV premium" is a major factor shaping the market in 2026.
Will my rate go down if I move from Oakland to a different city?
Potentially. If you move to a ZIP code with lower population density, lower crime rates, and fewer reported accidents, your "territory" risk decreases. However, California's mandatory "Good Driver" discount will follow you anywhere in the state, serving as the foundation of your premium regardless of your location.
Is telematics mandatory in California for 2026?
No, telematics programs are optional. However, as "standard" rates continue to rise due to inflation, many carriers are making their best rates accessible only to those who prove their safety via telematics. It is becoming a de facto requirement for those seeking the lowest possible cost.
Moving Forward: Next Steps for 94602 Drivers
To navigate the rising costs of auto insurance in Oakland 94602, the most effective action you can take is to conduct a "coverage audit" every six months. Do not allow your policy to auto-renew without first checking if your annual mileage has changed, if new safety features on your vehicle qualify for discounts, or if a competing carrier has updated its local risk model to your advantage.
Consulting with an independent insurance agent who understands the Oakland market is often more beneficial than using automated online quote tools. Independent agents can access multiple carriers and may find "niche" insurers that are currently targeting the 94602 demographic. By staying informed and proactive, you can protect your financial well-being against the tide of rising automotive costs.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
