
The distribution of life insurance purchases follows a clear bell-curve pattern, peaking among individuals aged 30 to 50. This demographic represents the "sweet spot" where high financial responsibility—such as mortgages and child-rearing—intersects with relative health and affordable premiums. While younger groups focus on locking in low rates and older groups prioritize estate planning, the mid-life cohort remains the primary driver of market volume.
The Correlation Between Life Stages and Insurance Adoption
To understand the distribution of life insurance purchases, one must first view life insurance not just as a financial product, but as a response to specific life milestones. The statistical distribution is not random; it is a direct reflection of when individuals typically encounter significant financial risks. In 2026, the landscape of these milestones has shifted slightly due to delayed homeownership and extended career paths, yet the fundamental motivations remain tied to the protection of dependents and debt obligations.
The "distribution" refers to the percentage of the population within specific age brackets that hold active life insurance policies or have recently purchased new coverage. Historically, and continuing into 2026, the highest density of active purchasers resides in the 30–45 age range. This is the period when most individuals transition from individual financial responsibility to "linked" responsibility—where their income is essential for the survival or lifestyle maintenance of others.
Conversely, the distribution tapers off at both ends of the age spectrum. Younger adults (18–25) often lack the perceived need or the discretionary income, while older adults (65+) may find premiums cost-prohibitive or may have already achieved "self-insurance" through the accumulation of assets. Understanding these nuances requires a deep dive into the specific motivations and barriers faced by each age bracket.
Demographic Breakdown: Purchasing Patterns by Age Group
The Early Adopters (Ages 18–25)
In 2026, the purchase rate among the 18–25 demographic remains the lowest, typically hovering between 10% and 15%. The primary barrier for this group is a combination of "optimism bias"—the belief that death or disability is too far in the future to warrant current expense—and competing financial priorities like student loan repayments or entry-level housing costs.
However, a growing segment of this group is purchasing "starter" term policies or permanent life insurance to lock in insurability. By purchasing a policy while at peak health, these individuals secure the lowest possible "Preferred Plus" rates, which can save tens of thousands of dollars over the life of the policy compared to waiting until age 40. Technical underwriting in 2026 increasingly uses predictive modeling for this group, often allowing for "accelerated underwriting" which bypasses medical exams for healthy young adults.
The Peak Growth Phase (Ages 26–40)
This is the most critical segment for the insurance industry. The distribution spikes significantly here, with nearly 50% to 60% of individuals in this bracket seeking some form of coverage. The primary drivers are marriage, the birth of a first child, and the acquisition of a primary residence.
For these purchasers, Term Life Insurance is the dominant product. It provides a high death benefit for a relatively low premium, which is necessary when a household is "cash poor" but "responsibility rich." In 2026, we see a heavy emphasis on "laddering" policies within this age group—buying multiple term policies of varying lengths (e.g., a 10-year, 20-year, and 30-year policy) to match the declining balance of a mortgage and the increasing independence of children.
The Consolidation Phase (Ages 41–55)
As individuals enter their 40s and 50s, the motivation for purchasing life insurance shifts from pure protection to a mix of protection and wealth accumulation. While the number of new policies issued might begin to decline compared to the 30s, the total coverage amount often increases.
This demographic is often referred to as the "Sandwich Generation," as they are simultaneously supporting college-aged children and aging parents. The technical complexity of the policies purchased here often increases. There is a higher distribution of Universal Life (UL) and Variable Universal Life (VUL) products in this bracket, as these individuals look for vehicles that offer both a death benefit and a cash-value component that can supplement retirement income or provide tax-advantaged wealth transfer.
The Legacy and Final Expense Phase (Ages 56–75)
Beyond age 55, the purchase distribution shifts toward "Final Expense" or "Whole Life" policies. The goal is no longer to replace 20 years of income, but rather to cover funeral costs, settle outstanding small debts, or pay potential estate taxes.
Premiums for new policies in this age group are significantly higher due to the increased mortality risk. Consequently, the distribution shows a preference for smaller face amounts (e.g., $10,000 to $50,000). In 2026, "Guaranteed Issue" policies are popular among the 65+ demographic, as these do not require a medical exam, making them accessible to those with managed chronic health conditions like Type 2 diabetes or hypertension.

Technical Factors Influencing Age-Based Distribution
The distribution of life insurance is not merely a matter of consumer choice; it is also dictated by the technical realities of the insurance industry’s actuarial tables and underwriting standards.
1. The Cost of Waiting (Premium Escalation)
Life insurance premiums are calculated based on the "Probability of Death" within a given year. As an individual ages, this probability increases exponentially, not linearly.
- Age 25 to 35: Premiums may increase by 5% to 8% total over the decade.
- Age 45 to 55: Premiums for the same coverage can increase by 50% to 100%.
- Age 65+: New coverage often becomes five to ten times more expensive than a policy initiated in one's 30s.
This "cost of waiting" creates a natural pressure that pushes the bulk of purchases into the 30–40 age bracket, where the value-to-risk ratio is most favorable for the consumer.
2. Underwriting and Insurability
Insurability is a "perishable asset." As people age, they are statistically more likely to develop health issues (high blood pressure, high cholesterol, etc.) that move them from a "Preferred" rating to a "Standard" or "Substandard" rating. This technical transition effectively "prices out" a portion of the older demographic, contributing to the lower distribution of new policy purchases in the 60+ category.
Comparison of Age Groups and Insurance Characteristics
The following table outlines how different age segments interact with the life insurance market in 2026.
| Age Group | Primary Motivation | Preferred Policy Type | Typical Coverage Amount | Purchase Barrier |
|---|---|---|---|---|
| 18–25 | Locking in rates / Insurability | Term or Starter Whole Life | $100k – $250k | Low perceived need |
| 26–40 | Mortgage & Child Protection | 20 or 30-Year Term | $500k – $2M+ | Budget constraints |
| 41–55 | Income Replacement / Education | Term or Universal Life | $1M – $3M | Health changes |
| 56–70 | Estate Planning / Debt Clearance | Whole Life or GUL | $50k – $500k | High premium costs |
| 71+ | Final Expenses / Legacy | Guaranteed Issue | $5k – $25k | Extreme cost / Eligibility |
Market Drivers and Trends in 2026
The distribution of life insurance by age is also being reshaped by technological and economic trends specific to 2026.
The Rise of Embedded Insurance
For the younger demographics (20s and 30s), life insurance is increasingly being "embedded" into other financial products. When a 30-year-old takes out a mortgage or starts a high-balance savings account, life insurance is often offered as an integrated add-on. This has slightly increased the distribution among younger cohorts who might not have sought out an independent agent.
Digital Underwriting and AI
By 2026, the use of Artificial Intelligence in underwriting has reached a mature state. AI algorithms can now analyze "alternative data"—such as prescription history, motor vehicle records, and even lifestyle data—to provide instant approval. This "frictionless" purchasing process has significantly boosted purchase rates among Gen Z and Millennials, who historically avoided the lengthy medical exam process required by traditional underwriting.
Economic Inflation and Face Value Adjustments
Inflationary pressures leading up to 2026 have forced a shift in the distribution of "coverage amounts." While the number of people buying remains steady, the amount of coverage purchased by the 30–50 age group has increased by roughly 20% to account for the rising cost of living, education, and healthcare that the death benefit is intended to cover.
Strategic Considerations for Consumers by Age
Navigating the distribution of life insurance requires an understanding of where you sit on the "risk-cost" curve.
For the Under-30s: The primary goal is to secure a "Convertible Term" policy. This allows you to pay low premiums now while having the contractual right to convert to a permanent policy later without a medical exam, regardless of any health issues you may develop in your 30s or 40s.
For the 30–50 Bracket: This is the time to maximize coverage. The "Human Life Value" approach should be used to calculate needs—multiplying current income by the number of years until retirement, plus outstanding debts. Because this group represents the peak of the purchase distribution, competition among insurers for this business is high, often leading to the most innovative and competitively priced products.
For the 50+ Bracket: Focus on "right-sizing" coverage. As children leave the house and mortgages are paid down, the need for massive term policies diminishes. The strategy often shifts to "Permanent" coverage that will be there for a lifetime, focusing on liquidity for heirs rather than simple income replacement.
FAQ
Why does the distribution of life insurance purchase peak in the 30s and 40s?
The peak occurs because this is the life stage where financial "fragility" is highest. Most individuals in this bracket have high debt (mortgages) and dependents (children) who rely entirely on their income. Simultaneously, premiums are still relatively affordable because the statistical risk of mortality is low compared to older ages, making it the most logical time for a consumer to buy.
Is the distribution of life insurance different for men versus women?
Yes, historically and in 2026, the distribution shows that women are slightly less likely to have adequate individual coverage compared to men, often due to the "gender protection gap." However, women typically pay lower premiums because they have a longer life expectancy. In recent years, the gap has narrowed as more women become primary or co-equal breadwinners in households.
How has the age of first-time life insurance purchasers changed by 2026?
The average age of a first-time purchaser has trended slightly upward. As people delay marriage and parenthood until their early or mid-30s, the "trigger" for purchasing life insurance also shifts later. However, the 2026 market has seen a counter-trend of Gen Z buyers purchasing very small policies in their early 20s as part of a "financial wellness" lifestyle.
Do premiums increase every year as I get older?
It depends on the policy type. If you have a Level Term policy, your premium stays exactly the same for the duration of the term (e.g., 20 years). If you wait to buy a new policy, the starting premium will be higher for every year you age. Some "Annually Renewable Term" policies do increase every year, but these are less common for long-term family protection.
Can I still get life insurance if I am over 70?
Yes, but the distribution of available products narrows significantly. At 70+, you are likely looking at "Final Expense" or "Simplified Issue" whole life insurance. These policies have much lower death benefits (usually under $50,000) and are designed to cover burial costs rather than replace income.
What is the biggest mistake people make regarding age and life insurance?
The most common mistake is treating life insurance as a "later" problem. Because the distribution of cost is exponential, waiting just five years (e.g., from age 35 to 40) can result in a 30-40% increase in total premiums paid over the life of the policy. Additionally, waiting increases the risk of a "medical lockout," where a new diagnosis makes coverage either unaffordable or unavailable.
Final Recommendation
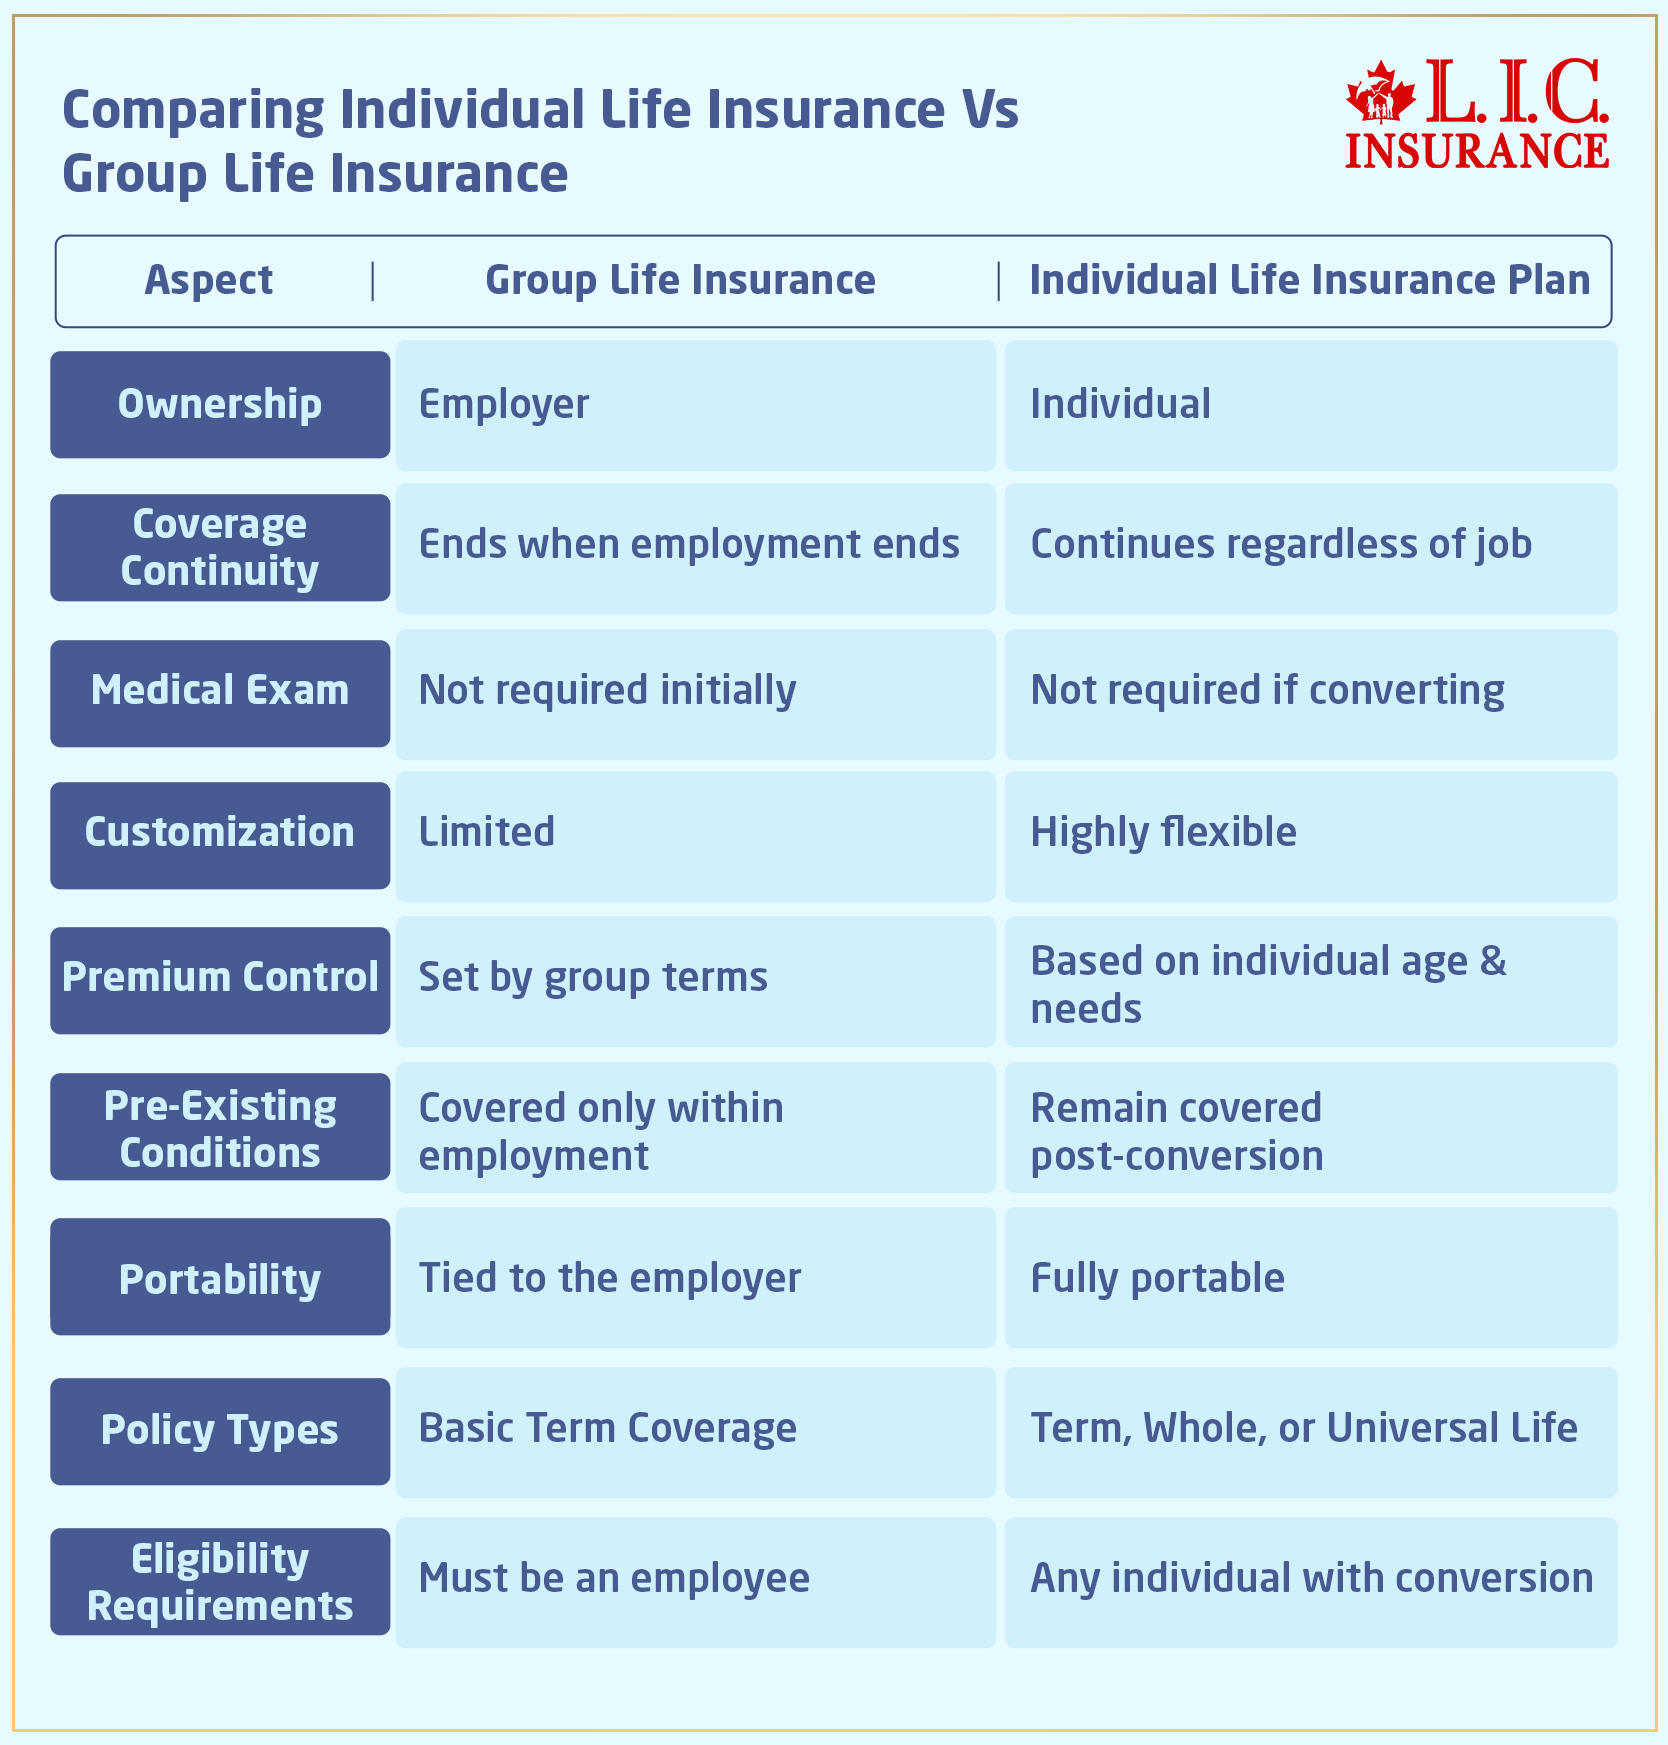
If you are currently between the ages of 25 and 45, you are in the optimal window to secure the highest amount of coverage for the lowest cost. For those in this bracket, the recommended action is to secure a 30-year level term policy that covers at least 10 to 12 times your annual income. If you are over age 50, prioritize a review of existing group policies through your employer and consider supplementing them with a small permanent policy to ensure coverage continues after retirement, when employer-sponsored plans typically lapse. Regardless of age, the most effective strategy is to purchase coverage based on your current "insurability" rather than waiting for a specific life event that might coincide with a change in your health profile.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
