How to Use the Ramsey Student Loan Calculator to Plan Your Debt Payoff
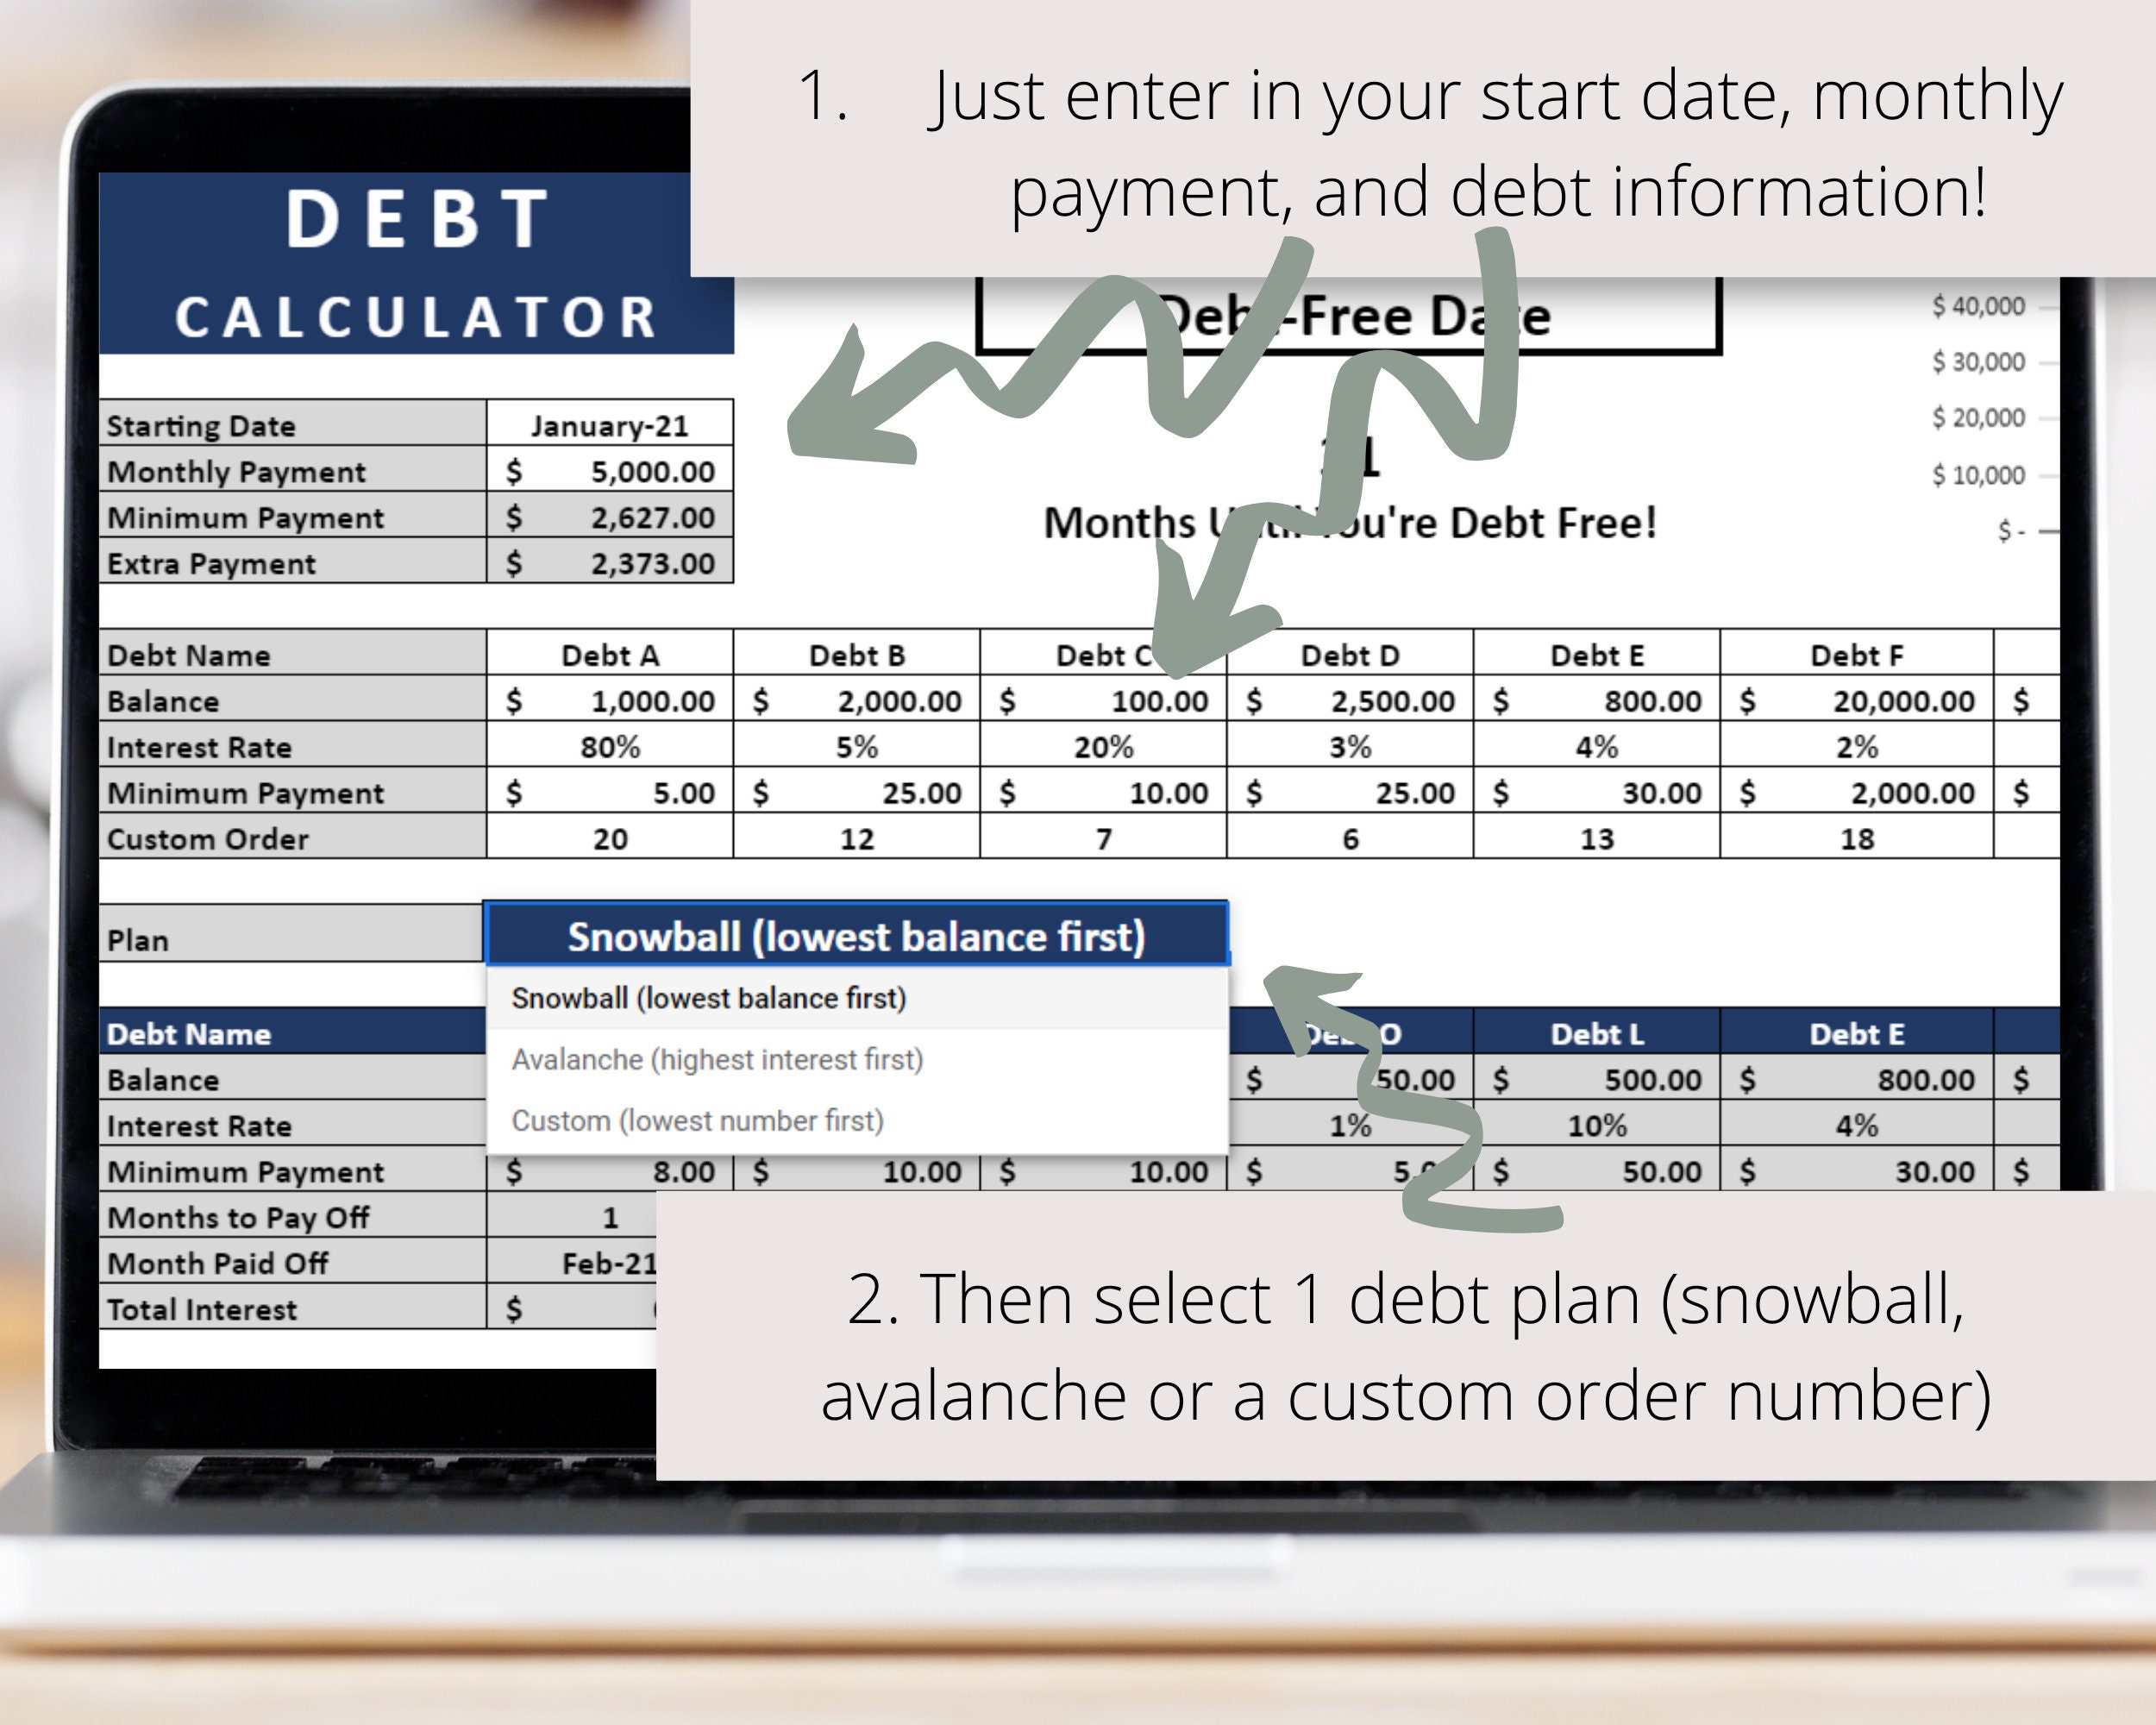
The Ramsey Student Loan Calculator is a specialized financial tool designed to help borrowers determine their debt-free date using the Debt Snowball method. By inputting your total loan balance, interest rate, and monthly contribution, the calculator visualizes how extra payments accelerate your progress toward eliminating student debt and reducing total interest costs.
Understanding the Role of the Ramsey Student Loan Calculator in 2026
As we navigate the financial landscape of 2026, student loan debt remains one of the most significant hurdles for individuals seeking to build wealth. The Ramsey Student Loan Calculator serves as a strategic roadmap rather than a simple math exercise. Unlike traditional calculators that prioritize interest rate optimization (the "Avalanche" method), this tool is built on the foundation of Dave Ramsey’s Baby Steps—specifically Baby Step 2, which focuses on the Debt Snowball.
The core philosophy behind this calculator is that personal finance is 80% behavior and only 20% head knowledge. By using the tool to see a concrete "Debt-Free Date," users receive a psychological boost that sustains their motivation through the often long and grueling process of repayment. In the current economic environment, where interest rates on new federal and private loans have fluctuated, having a clear, behavior-driven plan is essential for maintaining financial focus.
The calculator helps users move past the overwhelming feeling of a large balance by breaking the debt down into manageable monthly targets. It specifically highlights how even a small "extra" payment—the amount you pay above the minimum—can shave years off your repayment timeline. This is particularly relevant in 2026, as borrowers continue to balance student loan obligations with rising costs of living and housing.
How to Gather Your Data for Accurate Calculations
Before you sit down to use the Ramsey Student Loan Calculator, you must gather precise data. Estimations often lead to "math drift," where your projected payoff date is months or even years off from reality. To get the most out of the tool, you need to aggregate information for every individual loan you hold, whether they are federal or private.
Start by logging into the Federal Student Aid (FSA) portal to view your total federal balance, including Subsidized, Unsubsidized, and PLUS loans. For private loans, you will need to access each specific lender's dashboard. For each loan, you require three specific data points: the current principal balance, the annual percentage rate (APR), and the minimum monthly payment.
It is also vital to distinguish between your "minimum payment" and your "planned payment." The minimum is what the lender requires to keep the loan in good standing. However, the Ramsey method relies on you identifying "found money" in your budget to apply as an extra payment. By 2026 standards, a zero-based budget is the most effective way to identify this extra cash flow. Once you have these numbers, you can input them into the calculator to see the difference between "business as usual" and "gazelle intensity."
Step-by-Step Guide to Using the Calculator
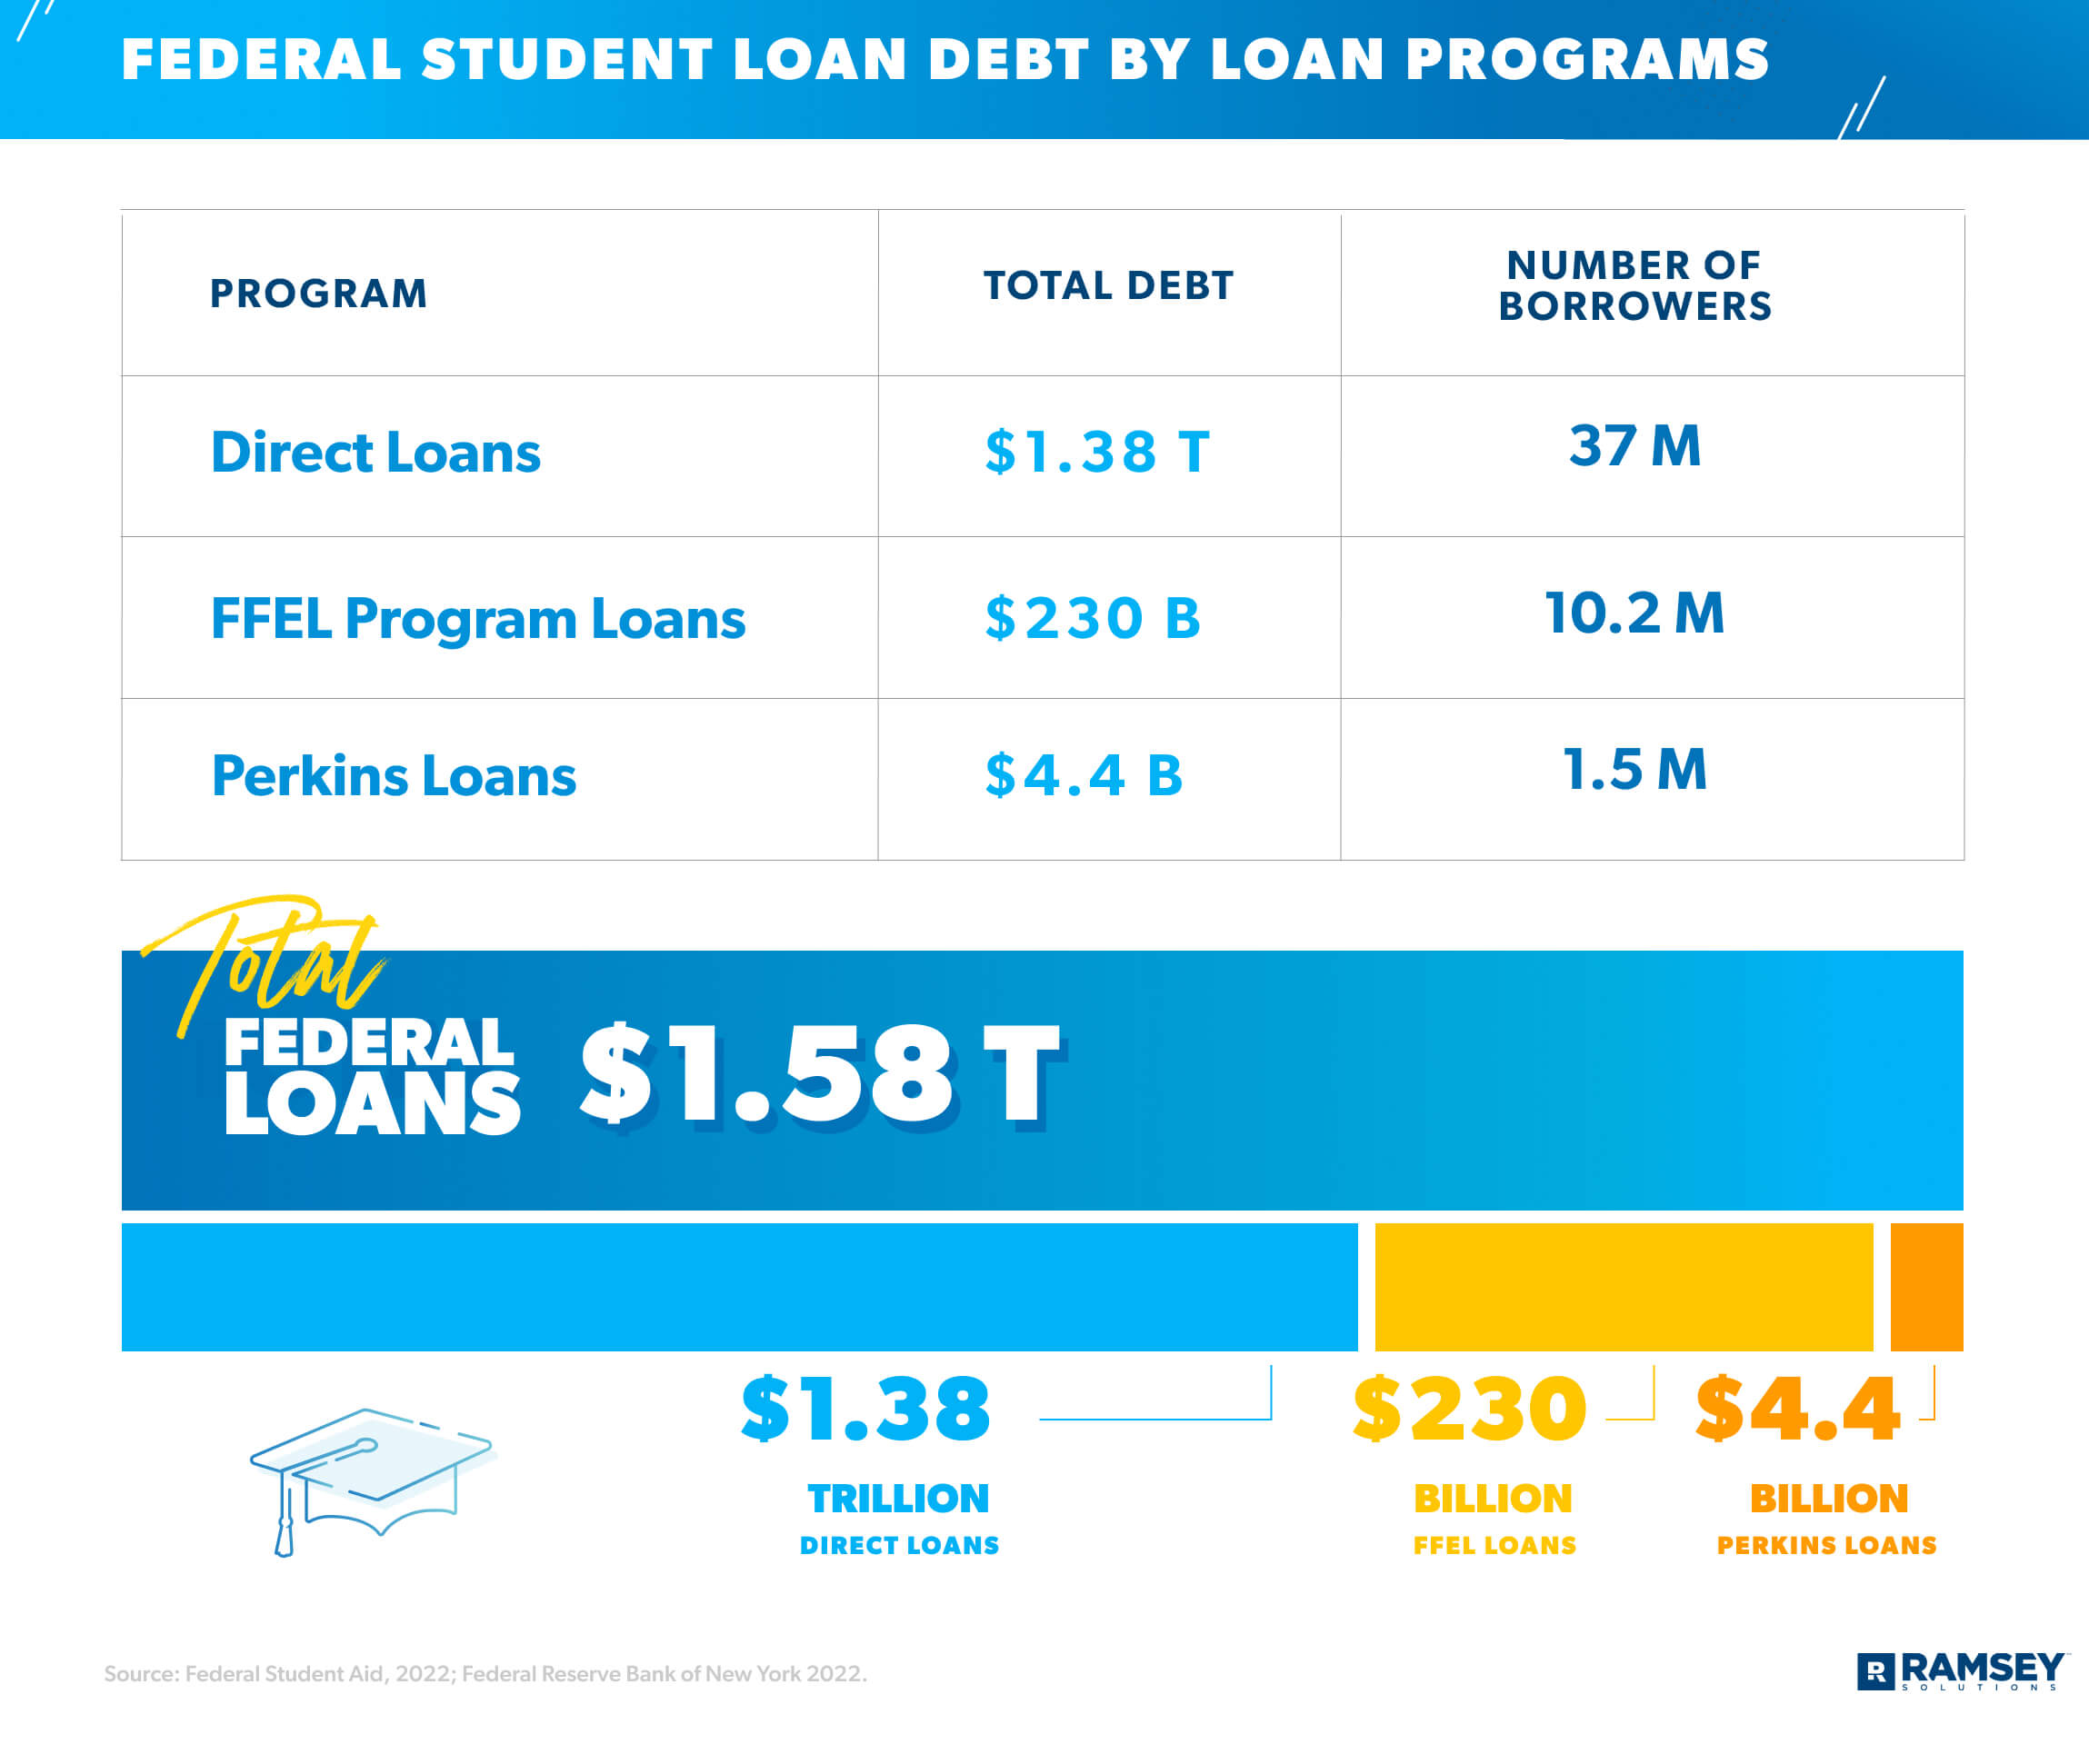
Using the Ramsey Student Loan Calculator is straightforward, but the way you interpret the results determines your success. Follow these steps to ensure you are utilizing the tool according to the Debt Snowball principles.
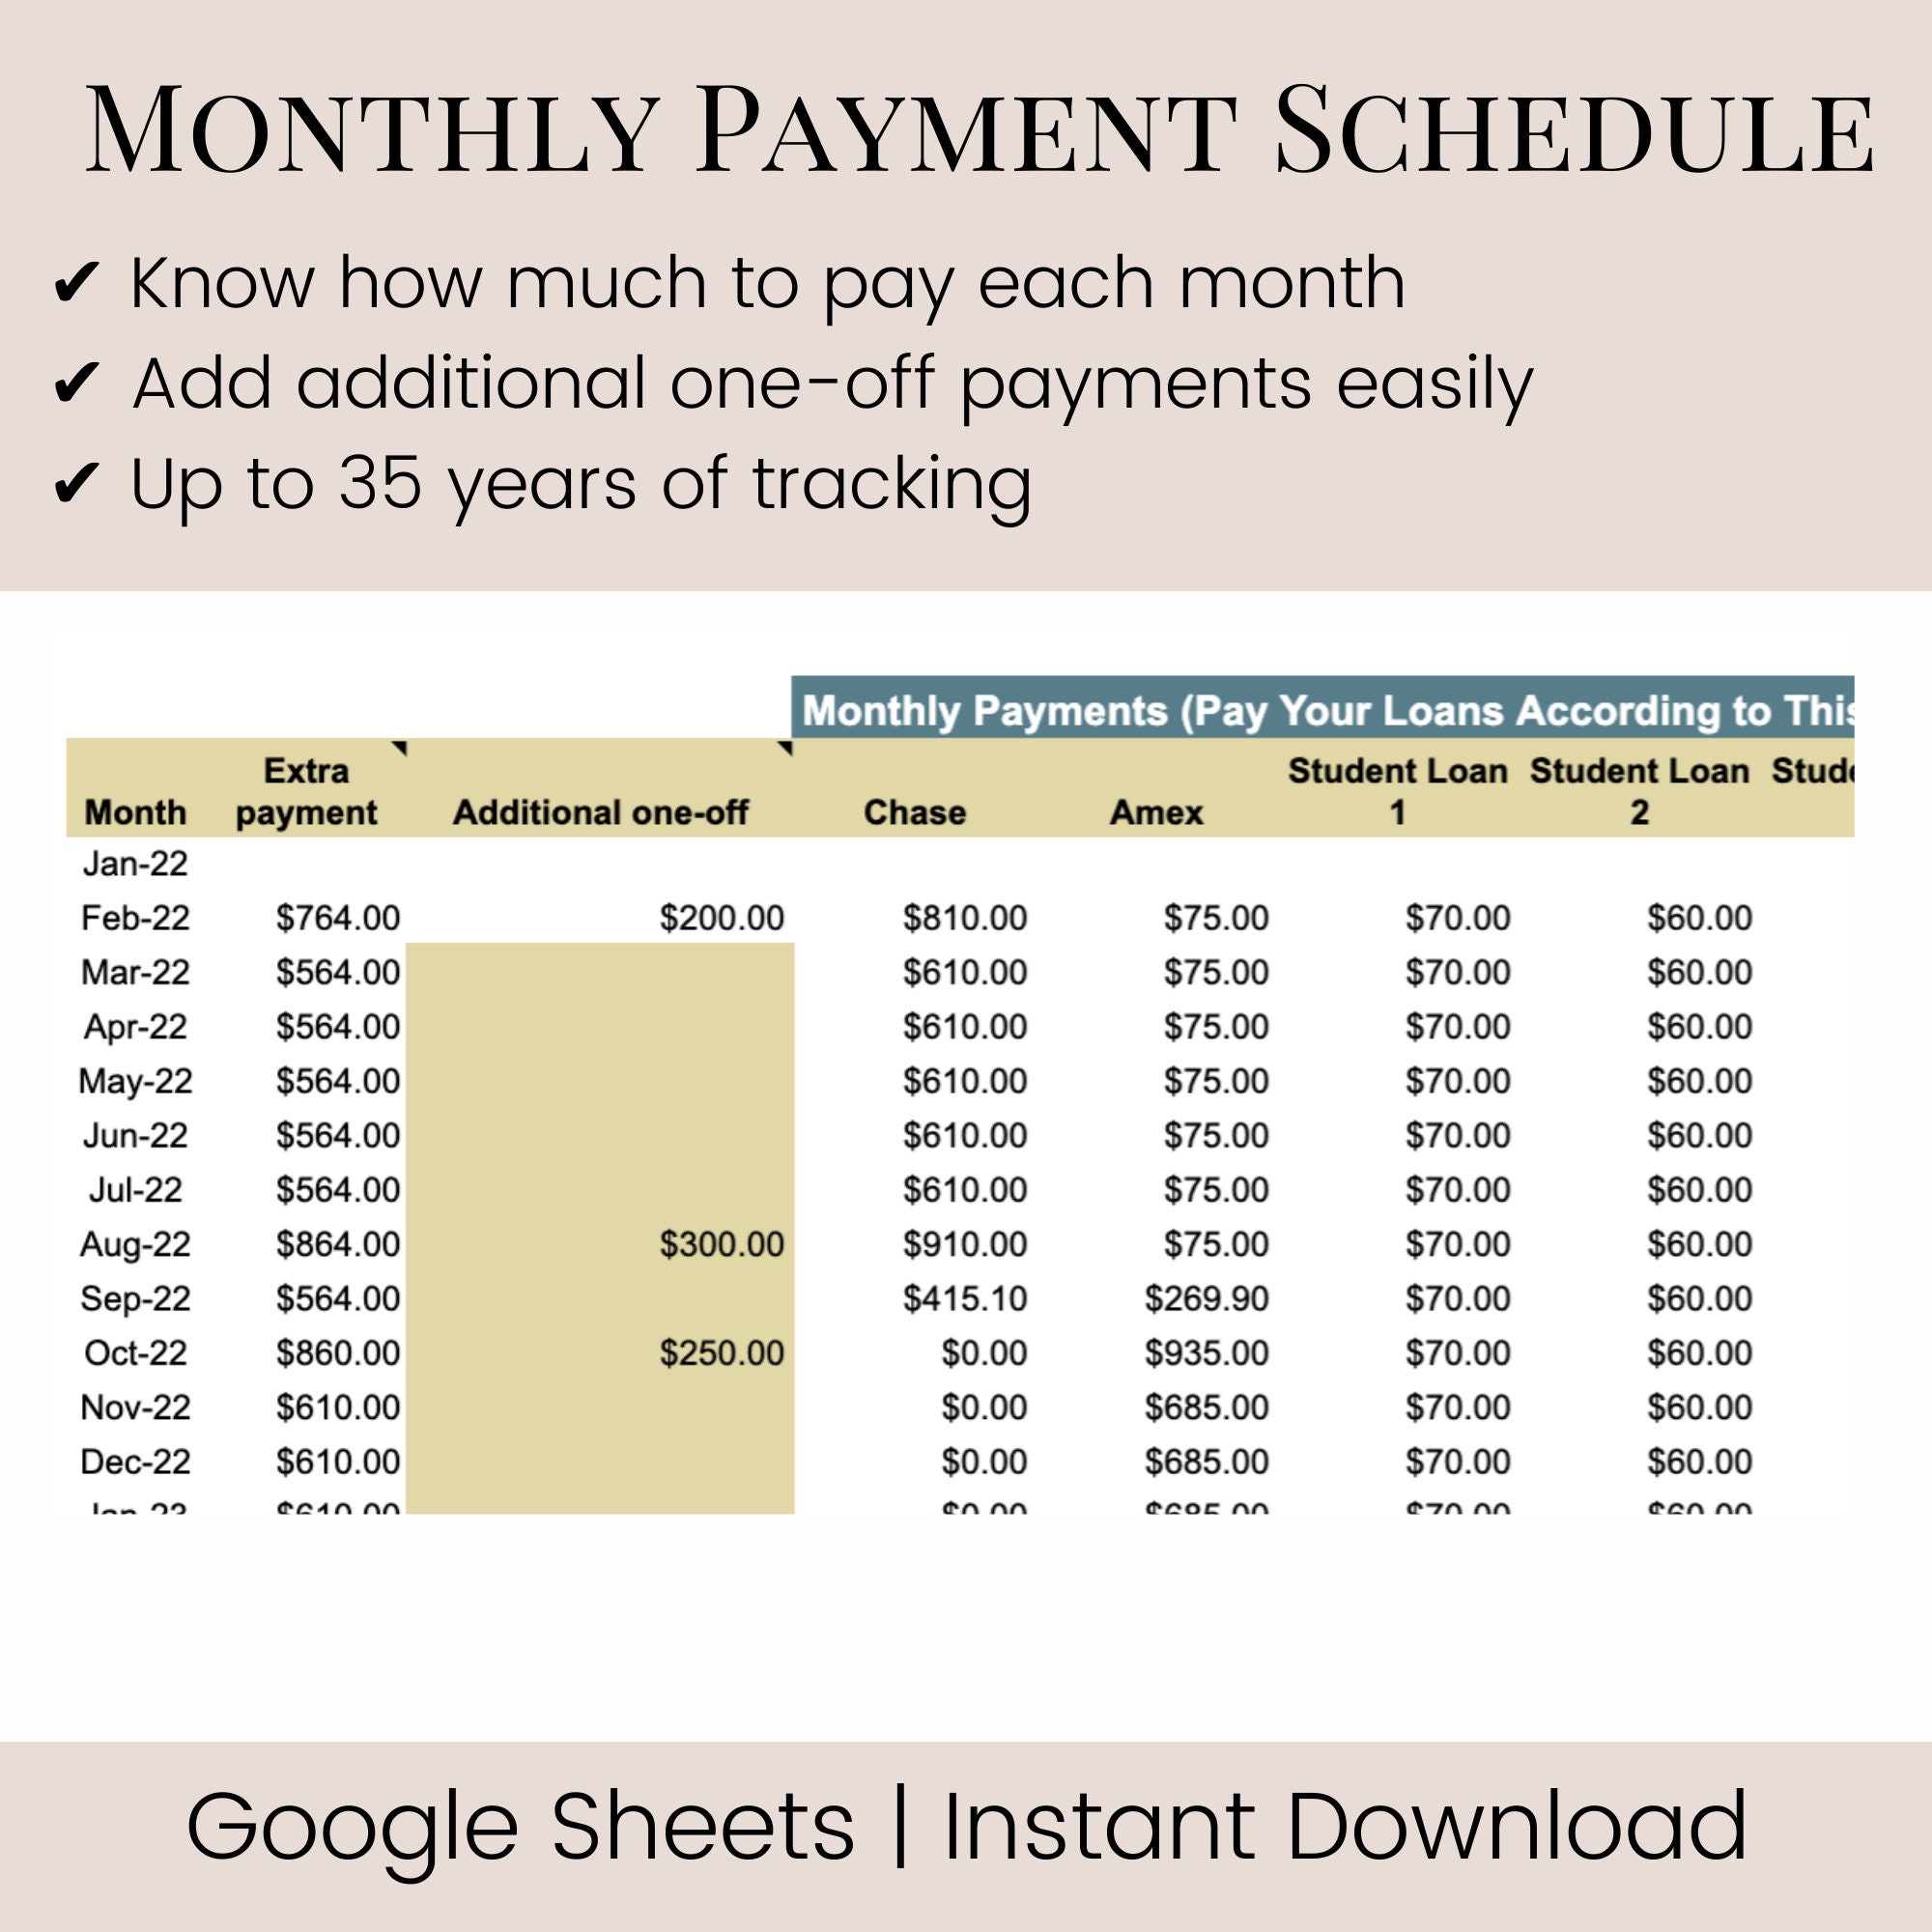
- Enter Your Total Loan Balance: If you have multiple loans, you can either enter them one by one to see individual payoff dates or sum them up for a global view. Ramsey typically recommends listing them from smallest balance to largest balance, regardless of interest rate.
- Input the Interest Rate: Use the specific APR provided by your lender. Even a 0.5% difference can change your total interest paid by thousands of dollars over the life of a large loan.
- Specify Your Current Monthly Payment: This is the minimum amount you are currently obligated to pay.
- Add the "Extra" Monthly Payment: This is the most critical field. This represents the money you’ve "scraped together" by cutting expenses or taking on extra work. The calculator will immediately update your payoff date based on this figure.
- Analyze the Results: Look at the "Total Interest Saved" and the "Time Saved" metrics. These figures are your primary motivators.
The calculator provides a visual representation of your progress. In 2026, many users find that by increasing their extra payment by just $100 or $200, they can move their debt-free date from 2035 to 2029. Seeing this transition in real-time on the screen helps solidify the commitment to the lifestyle sacrifices required by the Ramsey plan.
The Debt Snowball vs. The Debt Avalanche
One of the most frequent questions regarding the Ramsey Student Loan Calculator is why it doesn't prioritize loans with the highest interest rates. This is the fundamental difference between the Debt Snowball (Ramsey’s preferred method) and the Debt Avalanche.
The Debt Avalanche method instructs you to pay off the loan with the highest interest rate first. While this makes sense on paper because it saves the most money mathematically, it often fails in practice because borrowers lose steam. Student loans are often large and "monolithic"; if your highest interest loan is also your largest balance ($50,000 at 7%), it might take years to see that first "win."
Conversely, the Ramsey Student Loan Calculator encourages the Debt Snowball. You pay off your smallest balance first. The psychological win of crossing a loan off your list provides the "dopamine hit" needed to tackle the next one. As each loan is eliminated, the minimum payment from that loan is rolled into the payment for the next loan, causing the "snowball" to grow larger and faster.
Comparison of Payoff Strategies (Example Case)
The following table illustrates how different payment intensities affect a hypothetical $40,000 student loan balance at a 6% interest rate in 2026.
| Payment Strategy | Monthly Payment | Total Interest Paid | Years to Pay Off | Debt-Free Year |
|---|---|---|---|---|
| Minimum Only | $444.00 | $13,280 | 10 Years | 2036 |
| Standard + $200 | $644.00 | $7,450 | 6.1 Years | 2032 |
| Gazelle Intensity (+$500) | $944.00 | $4,720 | 3.9 Years | 2030 |
| Aggressive (+$1,000) | $1,444.00 | $2,980 | 2.5 Years | 2028 |
Note: Figures are estimates based on standard amortization formulas used in 2026. Individual results may vary based on specific loan terms.
The Impact of Interest Accrual and Capitalization
A common mistake when using the Ramsey Student Loan Calculator is failing to account for how student loan interest actually works. Unlike some forms of consumer debt, student loan interest is typically calculated on a daily basis (daily simple interest). This means that every day you carry a balance, a small amount of interest is added to your account.
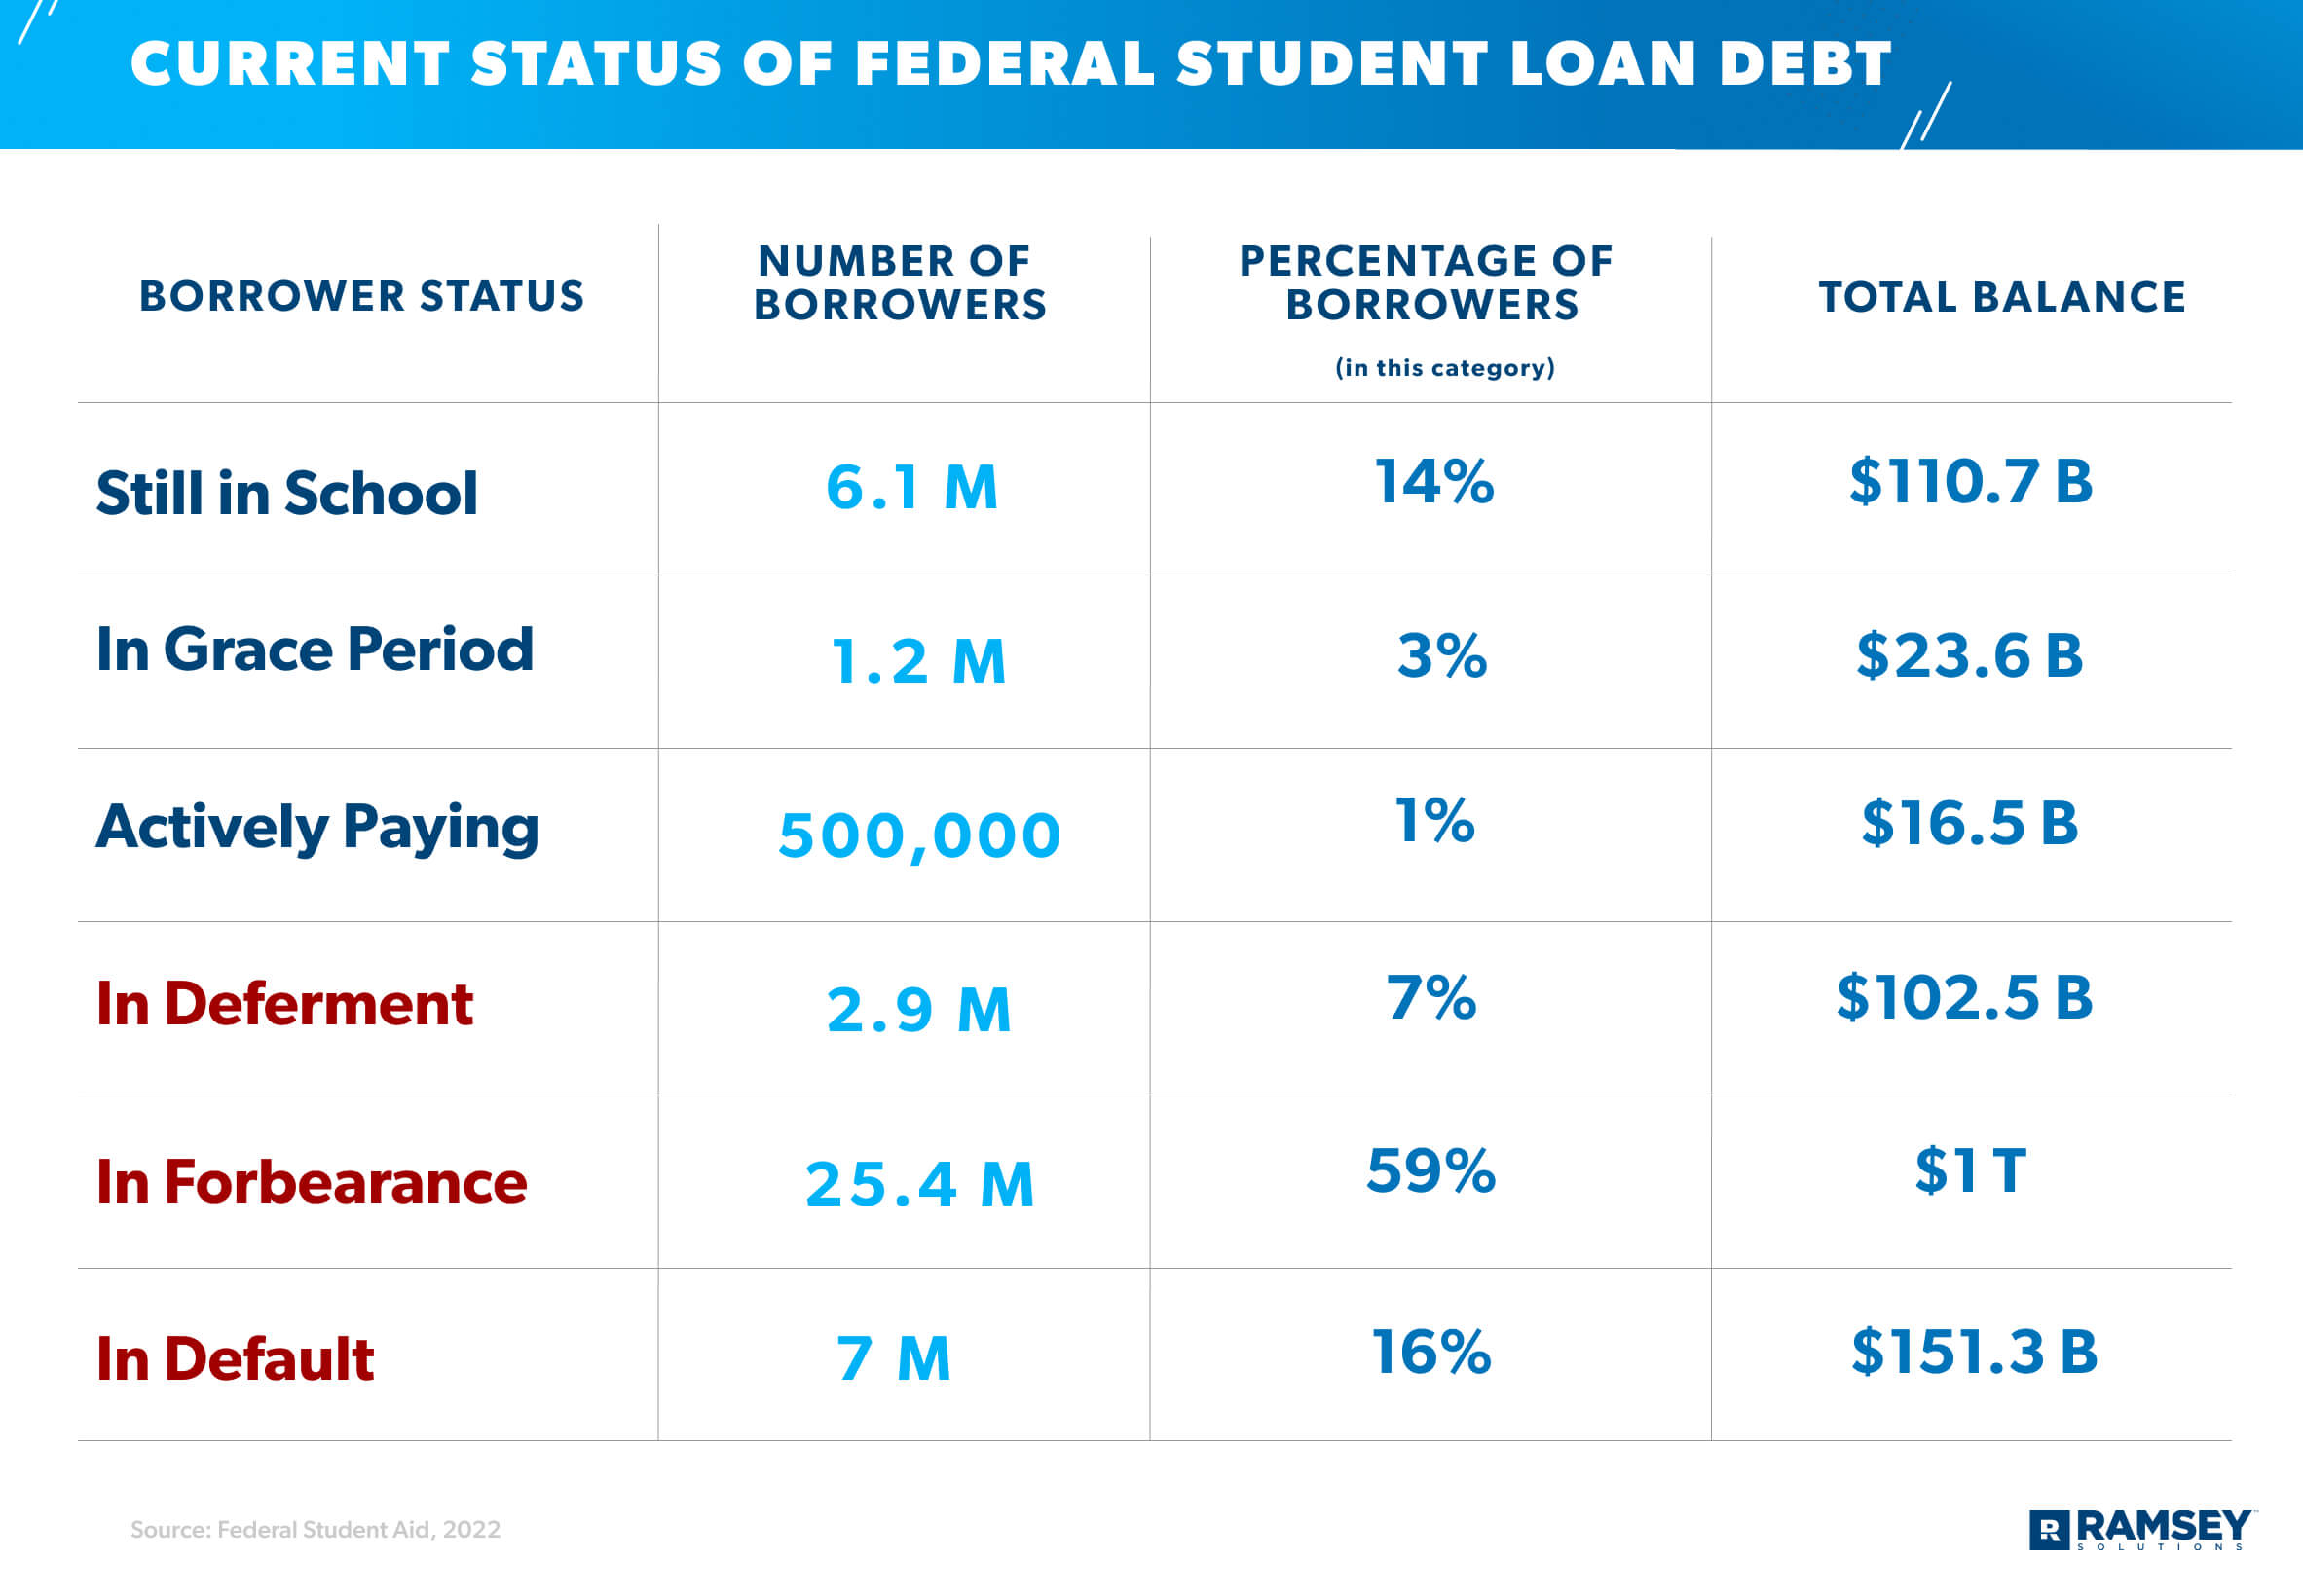
If you are in a period of deferment or forbearance, or if your minimum payment doesn't cover the interest (negative amortization), that interest can "capitalize." This means the unpaid interest is added to the principal balance, and you then begin paying interest on top of interest. While the Ramsey calculator is an excellent tool for planning, you must ensure that your "Extra Payment" is at least enough to cover the monthly interest accrual to see actual progress on the principal.
In 2026, borrowers must be particularly vigilant about capitalization events, such as when exiting a grace period or changing repayment plans. The Ramsey calculator works best when you are in "active repayment" mode, where every extra dollar is hitting the principal balance of your smallest loan.
Psychological Advantages of the Ramsey Approach
The effectiveness of the Ramsey Student Loan Calculator lies in its ability to quantify hope. For many, student debt feels like a life sentence. The calculator translates abstract numbers into a timeline. When a user sees that they can be debt-free in 3.5 years instead of 15, their behavior changes. They stop looking at the debt as a permanent line item in their budget and start looking at it as a temporary enemy to be defeated.
This psychological shift is known as the "Endowment Effect" in reverse; by visualizing the "future self" who is free of payments, the user becomes more willing to give up present-day luxuries. In 2026, with the proliferation of "buy now, pay later" schemes and easy credit, the Ramsey calculator acts as a necessary anchor to reality. It reminds the user that the fastest way to a high net worth is not through clever interest rate arbitrage, but through the total elimination of debt and the reclamation of their most powerful wealth-building tool: their income.
Common Obstacles and How to Troubleshoot the Calculator
While the tool is robust, users occasionally encounter discrepancies between the calculator’s projections and their actual bank statements. Understanding these variables is key to maintaining an accurate payoff plan.
- Variable Interest Rates: If you have private student loans with variable rates, the calculator’s projection may become inaccurate if the LIBOR or SOFR indices shift. It is advisable to re-run your numbers every six months to adjust for rate changes.
- Payment Timing: The calculator assumes payments are made consistently on the same day each month. If you pay late, more of your payment will go toward interest and less toward principal, slightly extending your payoff date.
- Lender Allocation Rules: Some lenders automatically apply extra payments to the next month’s minimum payment instead of the current principal. When using the Ramsey strategy, you must specifically instruct your lender to apply any "overage" to the principal balance of the specific loan you are targeting.
- Consolidation and Refinancing: If you consolidated your loans, you no longer have a "snowball" of small wins; you have one large "avalanche." Ramsey often advises against consolidation if it lowers your motivation, though it may be considered if it significantly lowers interest rates and you remain committed to the same aggressive payoff schedule.
Integrating the Calculator with a Zero-Based Budget
The Ramsey Student Loan Calculator is most effective when paired with a zero-based budget, such as that found in the EveryDollar app. A zero-based budget ensures that every dollar you earn is assigned a "job" before the month begins. By calculating your necessary living expenses (Four Walls: Food, Utilities, Shelter, Transportation) and subtracting them from your total income, you discover the exact amount available for your "extra payment."
In 2026, many households are finding success by "side-hustling" specifically for the student loan snowball. If you earn an extra $500 a month through freelance work or a part-time job, you can plug that $500 into the Ramsey calculator to see the immediate impact. Often, that one extra stream of income can cut a five-year payoff plan down to three years. This synergy between budgeting and the calculator creates a feedback loop of success.
Frequently Asked Questions
Does the Ramsey Student Loan Calculator account for Public Service Loan Forgiveness (PSLF)?
The Ramsey philosophy generally discourages relying on PSLF due to the high historical rejection rates and the fact that it keeps the borrower in debt for at least ten years. The calculator is designed for those who want to pay off their debt as quickly as possible through their own income rather than waiting for government intervention. If you are pursuing PSLF, the calculator can still show you how much interest you would save if you chose to pay the debt off early instead.
Can I use the calculator for multiple loans at once?
Yes, you can aggregate your loans. To follow the Ramsey method strictly, however, you should focus on the smallest loan first. You can use the calculator to determine the payoff date for Loan 1, then take the total amount you were paying on Loan 1 and add it to the minimum of Loan 2, re-running the calculation for the new balance.
Is the Ramsey Student Loan Calculator free to use?
As of 2026, the basic version of the student loan calculator remains a free resource on the Ramsey Solutions website. It is intended to provide a gateway into the broader Ramsey ecosystem, including books like The Total Money Makeover and financial coaching services.
How do I handle interest-free periods or 0% promotional rates?
If you are in a 0% interest period (which is rare in 2026 but possible with certain private loan promotions), you should still use the calculator. Set the interest rate to 0% to see how much faster your principal disappears. This is the most effective time to pay down debt, as 100% of your payment goes toward the balance.
What if my minimum payment is $0 due to an Income-Driven Repayment (IDR) plan?
If your minimum payment is $0, the calculator still works. You simply treat your "Extra Payment" as your total payment. However, be aware that if your $0 payment doesn't cover the accruing interest, your balance will grow. The Ramsey method suggests ignoring the $0 "allowance" and paying as much as possible to kill the debt quickly.
Moving Forward: Your Path to Debt Freedom
Once you have used the Ramsey Student Loan Calculator and have your "Debt-Free Date" in hand, the next step is action. The calculator is a map, but you still have to drive the car. Write your payoff date on a piece of paper and post it where you can see it daily—on your fridge or your bathroom mirror.
Commit to the "Gazelle Intensity" that Dave Ramsey advocates. This means cutting out non-essential spending, avoiding new debt (like car loans or credit cards), and potentially increasing your income through a second job or career advancement. The student loan calculator has shown you what is possible; your daily habits will determine if that possibility becomes your reality. By the time you reach the date projected by the tool, you will have not only a zero balance but also the financial discipline necessary to build lasting wealth in the years following 2026.
Image Gallery
Select an image to open it in a new tab.