
Finding life insurance for seniors over 90 years old typically involves identifying specialized final expense or burial insurance policies, as traditional term or whole life options are rarely available at this age. In 2026, the "cheapest" options are generally small-face-value permanent policies ranging from $2,000 to $10,000, designed specifically to cover funeral costs and immediate end-of-life debts rather than large-scale wealth transfer.
The Reality of Life Insurance Eligibility After Age 90
As of 2026, the landscape for senior life insurance has evolved to account for increased human longevity, but age 90 remains a significant actuarial threshold. Most mainstream insurance carriers cap their new applications at age 80 or 85. When a senior reaches 90, the pool of available insurance providers shrinks considerably. The primary reason for this is the statistical proximity to the average life expectancy; insurers view any policy issued at this age as a "near-certain" claim in the immediate future.
To find the cheapest life insurance at this stage, it is essential to understand that "cheap" is a relative term. You are essentially prepaying for a guaranteed payout, with the insurer adding a margin for administrative costs and the risk that the policyholder might pass away sooner than the premium accumulation covers. Consequently, premiums at age 90 are high relative to the death benefit. However, for families looking to avoid a sudden $10,000 to $15,000 funeral bill, these policies provide a structured way to manage that financial burden.
The focus for 90-year-olds is almost exclusively on Final Expense Insurance, also known as burial insurance or funeral insurance. These are small whole life policies that do not require a medical exam and remain in force as long as the premiums are paid.
Primary Types of Policies for Seniors Over 90
When searching for the most affordable coverage at age 90 or older, you will encounter three main structures. Choosing the right one depends entirely on the senior’s current health status and the family's budget.
1. Simplified Issue Life Insurance
This is often the most cost-effective path if the senior is in relatively good health. Simplified issue policies do not require a physical medical exam (no blood draws or urine samples). Instead, the applicant answers a series of "Yes/No" health questions on the application. The insurer will also check prescription drug databases and MIB (Medical Information Bureau) records.
Because the insurer assumes some level of health based on these questions, they can offer lower premiums than "guaranteed" plans. If a 90-year-old can qualify for simplified issue, they avoid the "waiting period" that plagues other senior products, meaning the full death benefit is active from day one.
2. Guaranteed Issue (GI) Life Insurance
If the senior has significant health issues—such as recent heart failure, active cancer treatment, or advanced dementia—Guaranteed Issue is often the only remaining option. As the name suggests, coverage cannot be turned down regardless of health. There are no medical questions and no exams.
The trade-off for this "guaranteed" acceptance is twofold:
- Cost: These are the most expensive policies per dollar of coverage.
- Graded Death Benefit: Almost every GI policy issued to a 90-year-old in 2026 includes a two-year waiting period. If the insured passes away from natural causes during the first 24 months, the beneficiary only receives the premiums paid plus a small amount of interest (usually 5% to 10%), rather than the full face value.
3. Pre-Need Funeral Insurance
While technically an insurance product, these are often sold directly by funeral homes. They allow you to lock in 2026 service prices and pay for the funeral in a lump sum or over a few years. While this can be the "cheapest" way to handle a funeral because it prevents price inflation, it lacks the flexibility of a standard life insurance policy, which pays cash directly to a beneficiary to be used for any purpose (such as medical bills or legal fees).

Comparative Cost of Coverage (2026 Estimates)
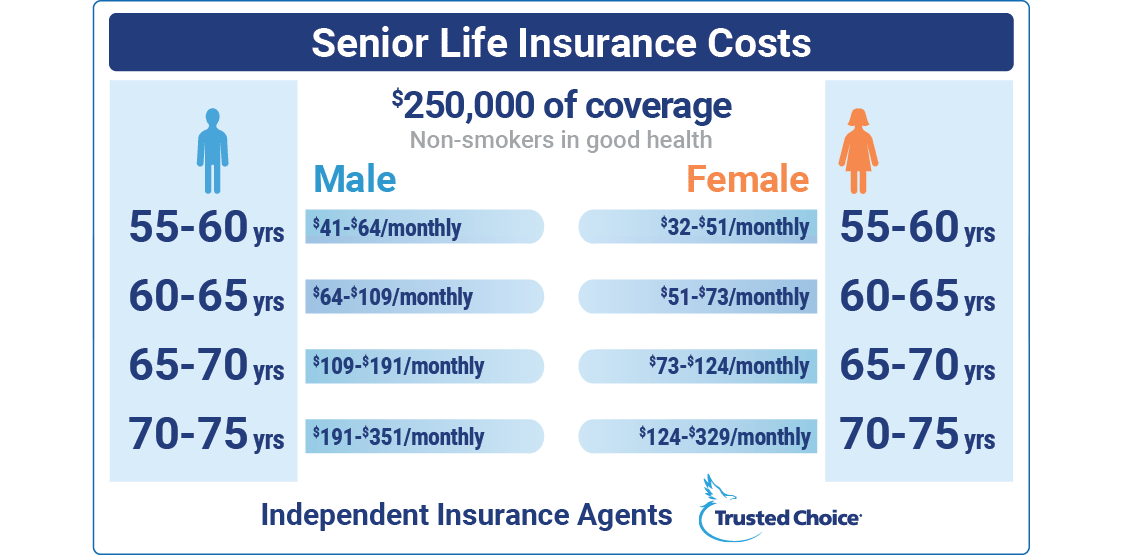
The following table provides an estimate of monthly premiums for a non-smoking male and female at age 90. These figures represent "best-case" pricing for final expense products with a $5,000 and $10,000 death benefit.
| Gender | Death Benefit | Estimated Monthly Premium (Simplified Issue) | Estimated Monthly Premium (Guaranteed Issue) |
|---|---|---|---|
| Female (Age 90) | $5,000 | $85 – $110 | $120 – $150 |
| Female (Age 90) | $10,000 | $165 – $210 | $235 – $290 |
| Male (Age 90) | $5,000 | $115 – $145 | $160 – $195 |
| Male (Age 90) | $10,000 | $225 – $285 | $310 – $380 |
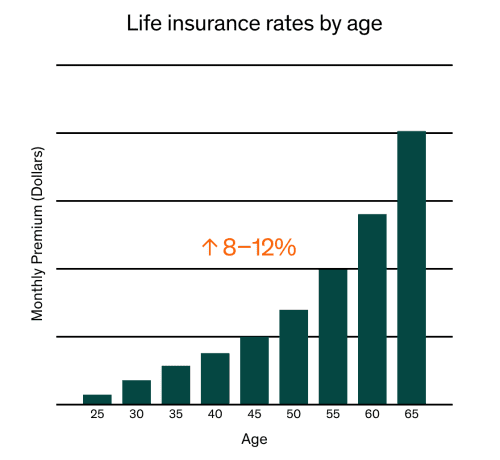
Note: Rates vary significantly by state and specific carrier. Premiums for ages 91-95 typically increase by 10-15% for each year of age at the time of application.
Key Technical Details: The 2-Year Waiting Period
Understanding the Graded Death Benefit is critical when purchasing insurance for someone over 90. Because insurers are taking on extreme risk at this age, they must protect themselves from "adverse selection"—the tendency for people who know they are dying to buy insurance.
In 2026, most policies for the 90+ demographic will include a clause stating that for the first two years, the full benefit is only paid if death is accidental (e.g., a fall or car accident). If death occurs due to illness or natural causes within that window, the payout is limited to a return of premiums.
For a 90-year-old, this represents a significant gamble. If the individual is currently in hospice or has a terminal diagnosis with a short life expectancy, paying into a life insurance policy may be less efficient than simply placing that money into a high-yield savings account or a dedicated funeral trust.
Requirements and Underwriting at Age 90
While medical exams are absent, "underwriting" still exists for the cheapest plans. For simplified issue policies, insurers in 2026 typically look for the following:
- Activities of Daily Living (ADLs): Can the senior feed themselves, dress, bathe, and move independently? If a senior requires nursing home care or 24/7 home health assistance for basic needs, they will likely be moved to a Guaranteed Issue pool.
- Cognitive Function: Many applications ask about Alzheimer’s, dementia, or memory loss medications (like Aricept or Namenda).
- Recent Hospitalizations: Insurers usually look back at the last 12 to 24 months. If there have been multiple hospitalizations for chronic conditions like COPD or congestive heart failure, the "cheapest" rates will be unavailable.
- Tobacco Use: Even at 90, smoking status matters. Smoker rates are significantly higher than non-smoker rates.
Strategies to Lower Costs for Seniors Over 90
To ensure you are getting the absolute lowest price possible, consider the following tactical approaches:
- Buy Only What You Need: Do not over-insure. Calculate the exact cost of a cremation or a simple burial in 2026. If a cremation costs $3,000, do not buy a $10,000 policy. The premium difference between $5k and $10k at age 90 can be over $1,200 per year.
- Annual vs. Monthly Payments: If the family can afford it, paying the premium annually rather than monthly can often save 5% to 8% in "fractional premium" fees charged by insurance companies.
- Independent Brokers: Avoid "captive" agents who only sell one brand. An independent broker can shop across the 5 or 6 niche companies that still offer 90+ coverage to find the one with the lowest rate for that specific health profile.
- Check Social or Fraternal Organizations: Sometimes organizations like the AARP (if they have a current 2026 partnership) or specific religious fraternal groups offer group rates that might be slightly lower than individual retail rates.
Common Mistakes to Avoid
- Waiting "One More Year": In the 90+ bracket, premiums increase drastically every 12 months. More importantly, many companies that offer coverage at 90 stop entirely at age 91 or 92.
- Lying on the Application: Since insurers check pharmacy databases, any omission of health issues will lead to a declined claim later. If the senior has a health condition, it is better to accept a higher-priced Guaranteed Issue policy than to have a Simplified Issue policy rescinded for fraud after death.
- Replacing Existing Policies: If the senior already has a policy from years ago, do not cancel it. Even if the premiums have gone up, a new policy started at age 90 will almost certainly be more expensive and will reset the two-year contestability period.
Alternatives to Life Insurance at Age 90
If the quotes for life insurance are prohibitively expensive, there are other ways to handle final expenses:
- Payable-on-Death (POD) Accounts: You can set up a specific savings account and name a beneficiary. The funds bypass probate and go directly to the beneficiary upon the owner's death to pay for the funeral.
- Irrevocable Funeral Trusts (IFT): This is a specialized trust where you deposit money specifically for funeral costs. In many states, these funds are "exempt assets" for Medicaid qualification, which is helpful if the senior is trying to qualify for long-term care assistance.
- Self-Funding: If the senior has $5,000 to $10,000 in liquid assets, it is usually more financially sound to keep that money in a liquid account rather than paying it to an insurance company in the form of high premiums at age 90.
Frequently Asked Questions
Can I get term life insurance for a 90-year-old?
No. In 2026, term life insurance is virtually non-existent for anyone over the age of 80 or 85. Term insurance is designed for temporary needs (like a mortgage), and at age 90, the "need" for insurance is considered permanent (end-of-life expenses). Therefore, only Whole Life or Final Expense products are available.
Does a 90-year-old need a medical exam to get the cheapest rate?
No. For the 90+ age group, insurance companies rely on health questionnaires and database checks rather than physical exams. A physical exam is generally considered too risky and unnecessary for the small face values ($5,000–$15,000) typically issued at this age.
How long does it take for a policy to be approved?
Simplified and Guaranteed Issue policies are often approved very quickly—sometimes within 24 to 48 hours. Because there is no medical exam to schedule, the process relies entirely on the digital verification of health records.
Will the premiums increase as the senior gets older?
If you purchase a Whole Life or Final Expense policy, the premiums are locked in for life. They will never increase regardless of how long the senior lives or how much their health declines after the policy is issued.
Is the payout taxable?
Generally, no. Under current 2026 tax laws, life insurance death benefits are paid out to beneficiaries free of federal income tax. However, if the death benefit is paid to the "estate" rather than a named person, it may be subject to estate taxes if the total estate exceeds federal or state thresholds.
Final Recommendation
If you are seeking the cheapest life insurance for a senior over 90, your first step should be to consult an independent agent who specializes in high-age final expense cases. Avoid "big name" term insurance providers and focus on carriers that offer small-benefit whole life.
Prioritize Simplified Issue if the senior can answer "No" to major health questions (cancer, stroke, or heart failure within the last two years), as this will provide the lowest premium and immediate coverage. If the senior has significant health challenges, a Guaranteed Issue policy is the final safety net, but be prepared for a two-year waiting period before the full death benefit becomes active. If the premiums quoted exceed 10% of the death benefit per year (e.g., paying $1,000 a year for a $5,000 policy), carefully consider whether self-funding or a funeral trust might be a more efficient use of the family's resources.
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
