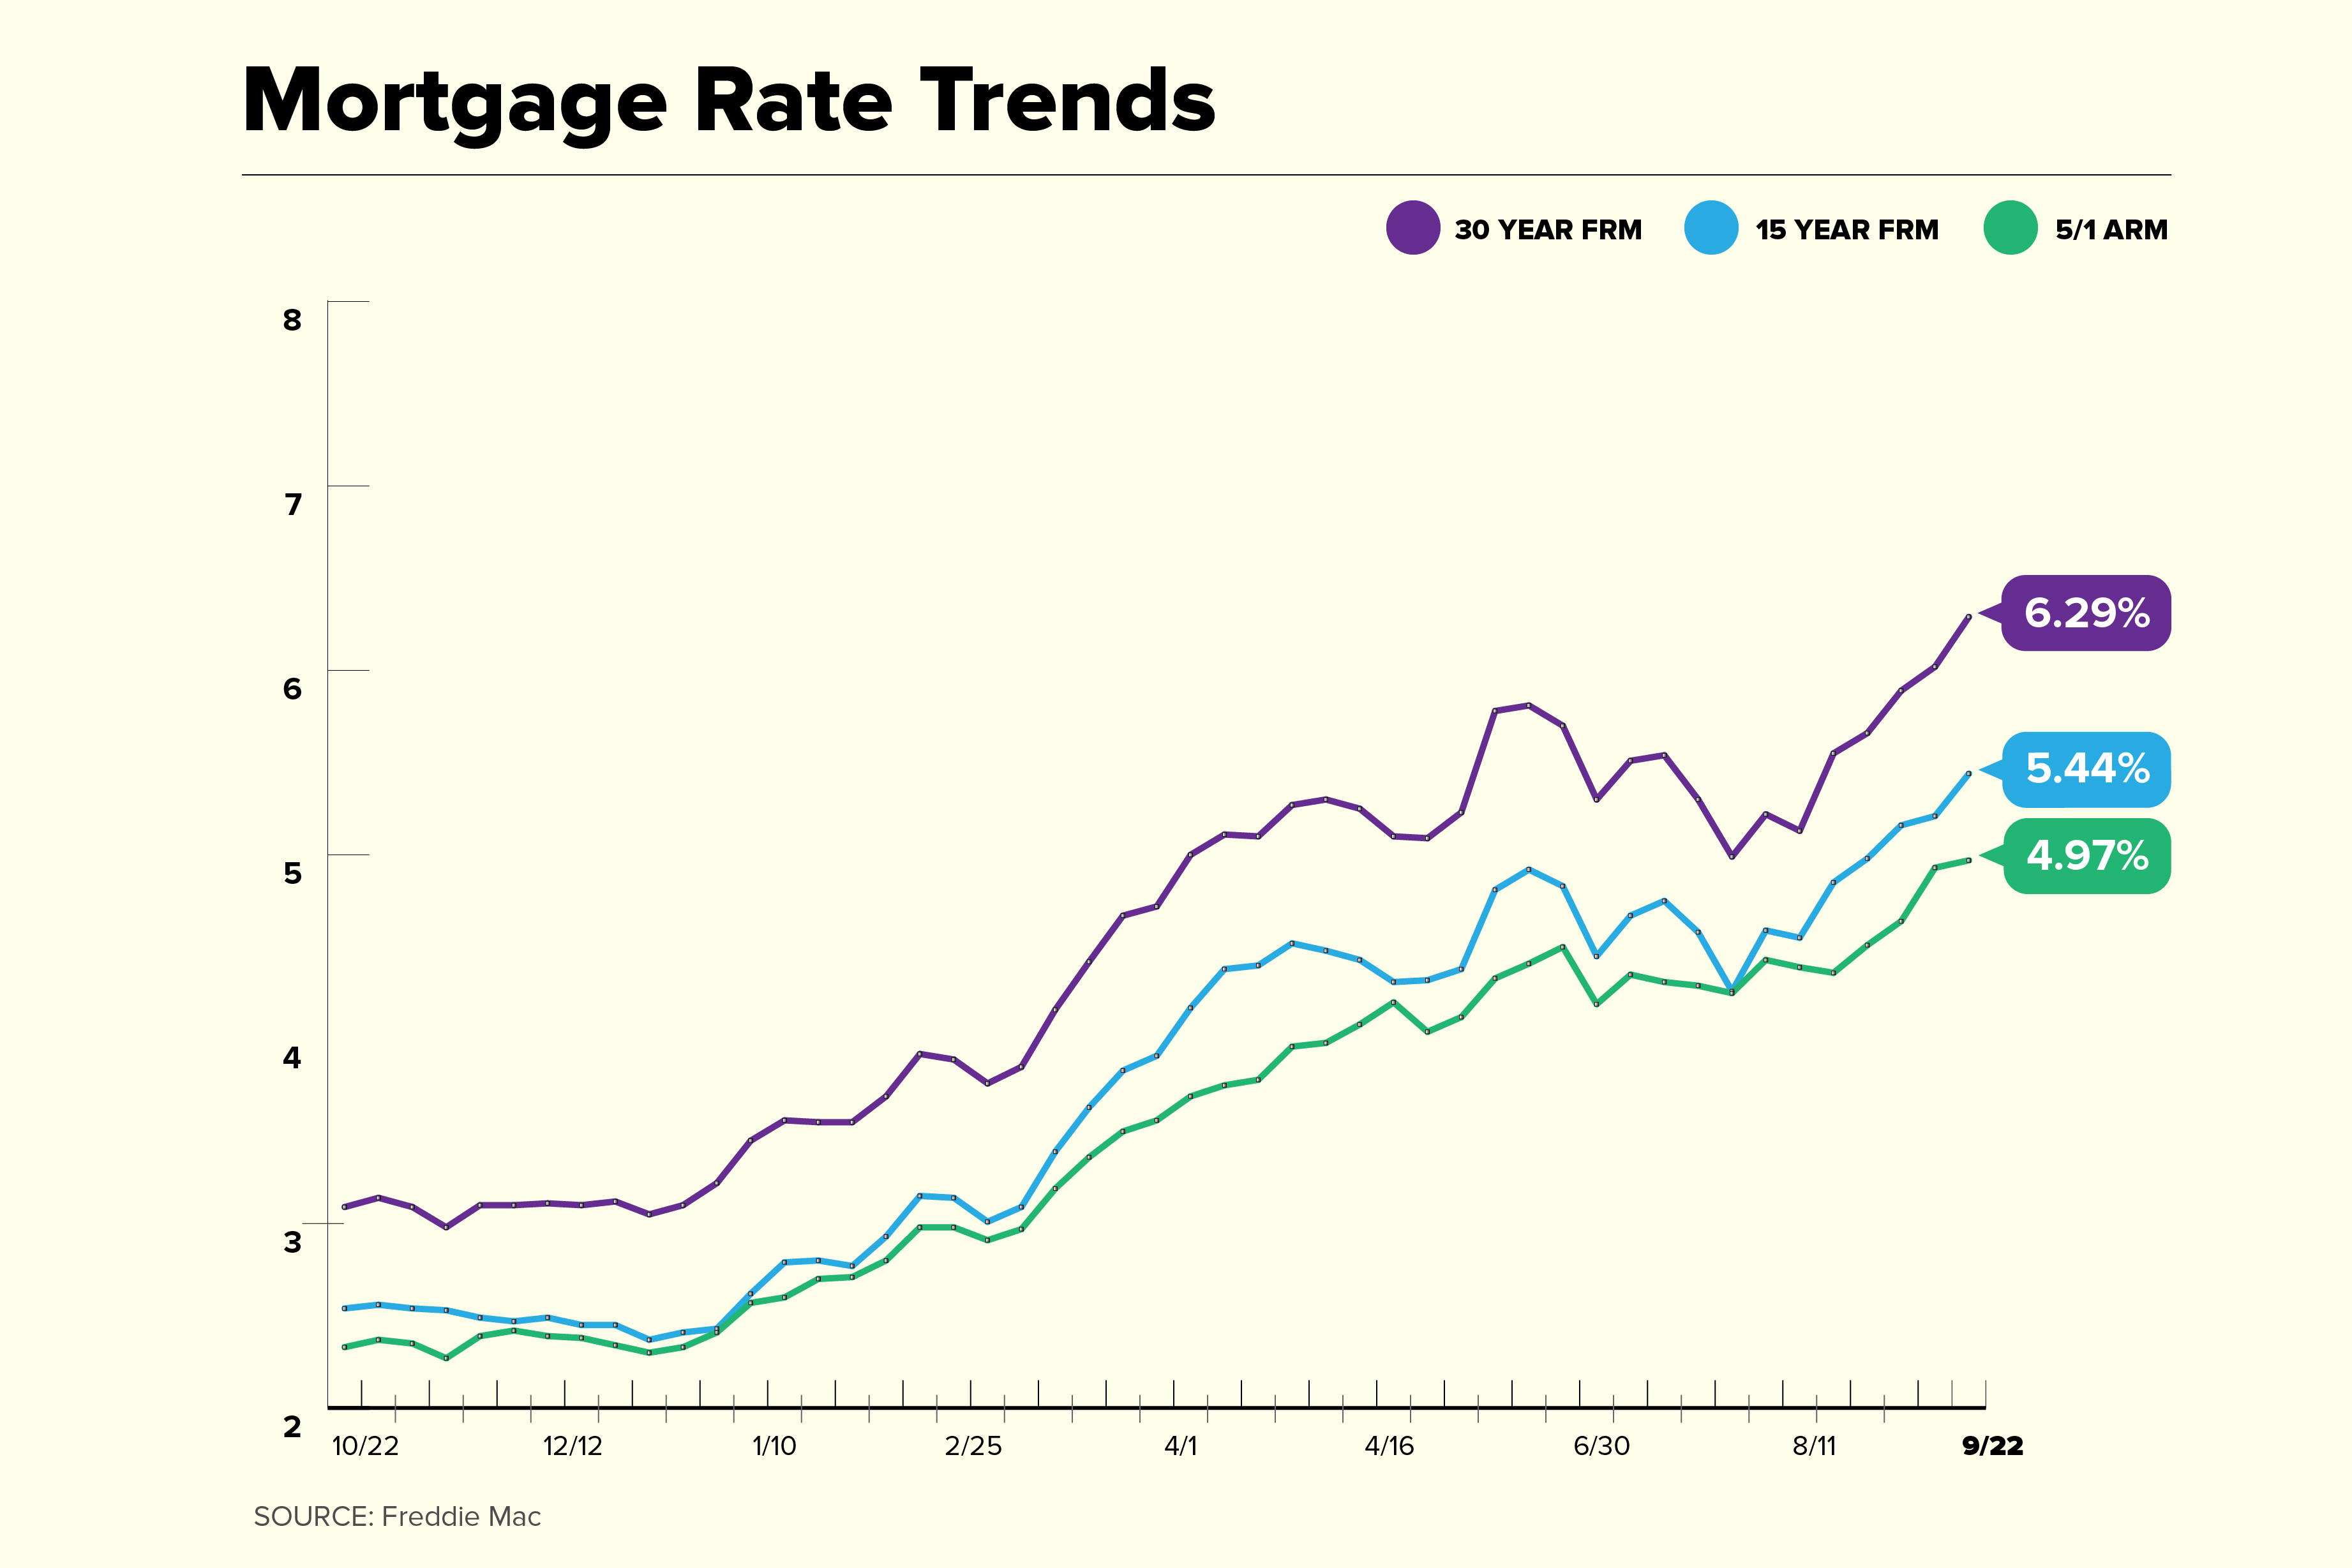
Monitoring Chase refinance rate changes requires an understanding of macroeconomic indicators, Federal Reserve monetary policies, credit markets, and specific lender pricing structures. When interest rates shift, homeowners frequently look to refinance their mortgages to lower monthly payments, shorten loan terms, or extract home equity. Because Chase (JPMorgan Chase Bank, N.A.) operates as one of the largest financial institutions in the United States, its mortgage rates and underwriting guidelines serve as a key benchmark for the broader housing finance industry. Evaluating how these rates change involves looking past daily advertised figures to examine the underlying financial mechanics, borrower eligibility criteria, and strategic financial planning required to secure favorable terms.
The Macroeconomic Drivers of Mortgage Rate Fluctuations
Mortgage interest rates do not exist in a vacuum; they respond dynamically to broad economic conditions, inflation data, employment reports, and central bank actions. While the Federal Reserve does not directly set consumer mortgage rates, its decisions regarding the federal funds rate profoundly influence the yield curve and, consequently, the pricing of long-term debt instruments like the 30-year fixed-rate mortgage.
The Relationship Between Treasury Yields and Mortgage Rates
To understand how Chase refinance rates change, one must examine the secondary mortgage market, particularly the yield on the 10-year U.S. Treasury note. Mortgage lenders typically price fixed-rate home loans at a spread above the 10-year Treasury yield. When investors anticipate economic growth, inflation, or fiscal policy shifts, bond prices fall and yields rise. As Treasury yields climb, lenders adjust their advertised refinance rates upward to maintain investor demand for mortgage-backed securities (MBS) on the secondary market.
Conversely, economic downturns, geopolitical uncertainties, or flight-to-safety events often drive investors toward government bonds, causing Treasury yields to drop and paving the way for lower refinance rates. Chase, like other major institutions, reprices its mortgage offerings daily—and sometimes intraday—based on these shifting capital market conditions.
Federal Reserve Policy and Short-Term vs. Long-Term Rates
Borrowers often confuse Federal Reserve rate cuts with immediate drops in fixed mortgage rates. When the Federal Open Market Committee (FOMC) adjusts the federal funds rate, it directly impacts short-term borrowing costs, such as prime rates, credit cards, and home equity lines of credit (HELOCs). Adjustable-rate mortgages (ARMs) tied to short-term indexes also react swiftly to Fed policy.
Fixed-rate mortgages, however, are more closely tethered to long-term inflation expectations and the 10-year Treasury yield. If the Federal Reserve lowers the federal funds rate to stimulate a slowing economy, fixed mortgage rates may already have factored in that expectation weeks or months in advance. Therefore, monitoring Chase refinance rate changes requires distinguishing between the specific loan product (fixed versus adjustable) and the corresponding economic benchmark driving its price.
Types of Refinancing Offered by Chase
Refinancing a mortgage involves replacing an existing home loan with a new one, typically with different terms, interest rates, or borrowing amounts. Borrowers generally pursue two primary pathways: a rate-and-term refinance or a cash-out refinance. Each option serves distinct financial goals and carries different pricing structures and underwriting requirements.
Rate-and-Term Refinancing
A rate-and-term refinance alters the interest rate, the loan term, or both, without increasing the principal balance of the loan (aside from closing costs). Homeowners typically choose this option to:
- Secure a lower interest rate to reduce monthly mortgage payments.
- Switch from an adjustable-rate mortgage (ARM) to a predictable fixed-rate mortgage.
- Transition from a 30-year term to a 15-year term to build equity faster and pay less total interest over the life of the loan.
When Chase implements rate changes, rate-and-term refinances are the most direct beneficiaries of downward market movements, as lower baseline rates immediately translate into interest savings for qualified applicants.
Cash-Out Refinancing
A cash-out refinance replaces an existing mortgage with a new loan for a higher amount than what is currently owed, allowing the homeowner to receive the difference in cash. This capital can be used for home renovations, debt consolidation, education expenses, or other major financial needs.
Because cash-out refinancing exposes the lender to higher risk—increasing the loan-to-value (LTV) ratio—Chase and other major lenders typically price cash-out refinances slightly higher than rate-and-term refinances. Risk-based pricing adjustments, often referred to as loan-level price adjustments (LLPAs), apply based on credit scores, property types, and LTV ratios.
| Refinance Type | Primary Purpose | Typical Risk Profile | Rate Impact Compared to Standard Benchmark |
|---|---|---|---|
| Rate-and-Term (Fixed) | Lower monthly payment or shorten loan term | Standard | Baseline market rate |
| Rate-and-Term (ARM) | Lower initial payments, flexibility for short-term ownership | Moderate-High | Often lower initially, subject to future adjustment |
| Cash-Out Refinance | Access home equity for external expenses | Higher | Generally higher due to increased LTV and risk adjustments |
Borrower Eligibility and Qualification Standards
Securing competitive rates during a period of Chase refinance rate changes depends heavily on an individual borrower's financial profile. Lenders evaluate several key risk metrics before locking in a final interest rate.
Credit Score Requirements
Credit scores remain a primary determinant of the interest rate a borrower receives. Chase evaluates credit reports from major bureaus to assess past repayment behavior, credit utilization, and debt loads. Borrowers with excellent credit scores (typically 740 and above) qualify for the most favorable advertised rates. Those with lower scores may still qualify for a refinance, but risk-based pricing will typically result in a higher interest rate or require additional credit enhancements, such as a lower LTV ratio.
Loan-to-Value (LTV) and Home Equity
Loan-to-value ratio measures the size of the requested mortgage relative to the appraised value of the property. For a conventional rate-and-term refinance, lenders prefer an LTV of 80% or lower, allowing the homeowner to retain at least 20% equity. Higher LTV ratios are permitted under certain programs, but anything above 80% on a conventional loan generally necessitates private mortgage insurance (PMI), which adds to the monthly cost of the loan. For cash-out refinances, Chase and industry standards typically cap the maximum LTV at 80% or lower, depending on the property type and occupancy status.
Debt-to-Income (DTI) Ratio
The debt-to-income ratio compares a borrower's monthly debt payments (including the proposed new mortgage payment, car loans, student loans, and minimum credit card payments) to their gross monthly income. Chase enforces specific DTI caps to ensure borrowers have sufficient income to service the debt comfortably. While maximum allowable DTI ratios vary by loan program and overall credit profile, maintaining a lower DTI strengthens loan approval odds and can influence pricing terms.
Steps to Take When Tracking and Executing a Refinance
Navigating interest rate volatility requires a strategic approach to timing, locking, and finalizing a mortgage refinancing application. Homeowners must balance market observation with operational readiness.
1. Monitor Daily Rate Trends and Establish a Target Rate
Because Chase updates its mortgage pricing frequently based on bond market movements, tracking daily rate trends is essential. Rather than attempting to time the absolute bottom of the market—which is notoriously difficult—homeowners should establish a target interest rate or monthly payment reduction threshold that meets their financial goals.
2. Review and Optimize Your Financial Profile
Before formally applying, pull credit reports to check for errors, pay down revolving debts to improve credit utilization, and gather necessary financial documentation, including tax returns, W-2s, and bank statements. A pristine financial profile ensures that when you lock in a rate, you qualify for the best pricing tier available.
3. Evaluate Closing Costs and Break-Even Analysis
Refinancing is not free; closing costs typically range from 2% to 6% of the loan amount, covering origination fees, appraisal fees, title insurance, and recording fees. Calculate the break-even point by dividing the total closing costs by the monthly savings achieved through the lower interest rate. If you plan to sell the home before reaching the break-even point, refinancing may not be financially advantageous.
4. Lock Your Rate and Complete Underwriting
Once you submit an application and choose a favorable rate environment, work with a Chase mortgage loan officer to lock in your rate. A rate lock guarantees a specific interest rate for a set period (such as 30, 45, or 60 days) while the loan moves through processing, property appraisal, and underwriting verification.
Alternatives to Traditional Bank Refinancing
If Chase refinance rate changes result in market rates that do not align with your financial goals, several alternatives exist to achieve liquidity or reduce borrowing costs without executing a full mortgage refinance.
- Home Equity Lines of Credit (HELOCs): If you need cash for home improvements or consolidation but want to keep your existing low first-mortgage rate intact, a HELOC allows you to borrow against your home equity through a revolving line of credit with a separate variable or fixed rate structure.
- Home Equity Loans: Similar to a HELOC, a home equity loan provides a lump sum of cash backed by your property equity, but with a fixed interest rate and predictable monthly payments, preserving your primary mortgage.
- Loan Modification: For homeowners experiencing financial hardship rather than seeking market-driven savings, working directly with loan servicers for a permanent loan modification may adjust terms without the underwriting standards and costs of a traditional refinance.
Frequently Asked Questions About Chase Refinance Rate Changes
How often do Chase mortgage refinance rates change?
Chase updates its mortgage and refinance interest rates daily, and occasionally multiple times per day, in response to fluctuations in the bond market, secondary mortgage pricing, and broader macroeconomic conditions.
Does Chase offer a rate-lock extension if my refinance takes longer than expected?
Yes, lenders typically offer rate-lock extension options if underwriting or appraisal delays push closing past the initial lock expiration date. However, extension fees may apply depending on market movements and who caused the delay.
How do I know if refinancing with Chase is worth the closing costs?
Calculate your break-even timeline by dividing the total closing costs by your monthly savings. For example, if closing costs total $4,000 and your new rate saves you $200 per month, your break-even point is 20 months. If you plan to stay in the home longer than 20 months, the refinance is generally considered beneficial.
Can I refinance my mortgage with Chase if my property value has decreased?
Refinancing is more difficult if home values have dropped, as your Loan-to-Value (LTV) ratio increases. If your LTV exceeds 80% on a conventional loan, you may face private mortgage insurance requirements, or you may need to bring cash to the closing table to reduce the loan balance.
What documents are required to lock in a refinance rate with Chase?
Standard documentation includes recent pay stubs, W-2 forms or tax returns (for self-employed borrowers), bank statements verifying assets, and information regarding existing debts and property insurance.
Conclusion and Next Actions
Monitoring Chase refinance rate changes requires keeping a close eye on macroeconomic trends, Treasury yields, and your personal financial standing. Because rates fluctuate daily, preparation is your best tool for capturing a favorable market window. Begin by reviewing your credit score, calculating your current home equity, and determining whether a rate-and-term or cash-out refinance aligns with your long-term financial strategy. Consult directly with a Chase mortgage specialist or utilize online rate calculators to evaluate current offers, assess total closing costs, and execute a rate lock when your financial targets are met.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
