
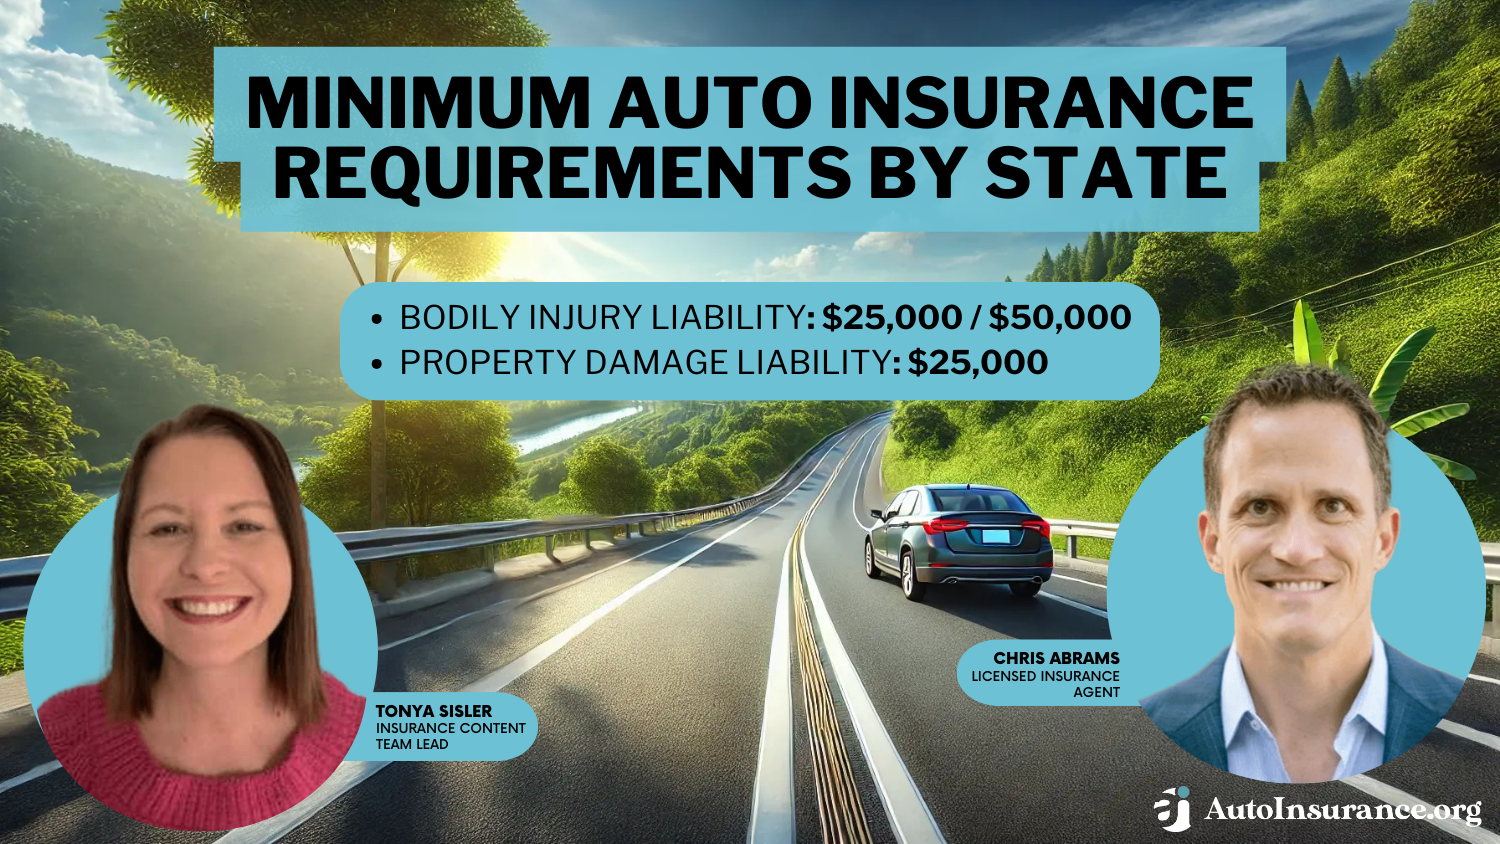
Auto insurance in Bedford, Texas, consists of state-mandated liability limits combined with optional but critical protections like Personal Injury Protection (PIP) and Comprehensive coverage. While Texas law requires a minimum of 30/60/25 liability, a functional Bedford policy typically includes additional safeguards against local risks such as North Texas hail storms and high-density traffic on Highway 183.
Navigating the complexities of vehicle protection in the Mid-Cities region requires a clear understanding of what is legally required versus what is practically necessary. In Bedford, an auto insurance policy is not a singular "product" but a modular contract composed of several distinct types of coverage. Each component addresses a different financial risk, from damaging someone else's property to repairing your own vehicle after a Tarrant County supercell storm.
The Foundation: Texas State Minimum Liability
To legally operate a motor vehicle in Bedford, you must meet the financial responsibility requirements set by the Texas Transportation Code. In 2026, the state continues to operate under the "30/60/25" rule. This is the bedrock of any Bedford auto policy, but it is important to understand that this coverage is designed to protect others, not you.
Bodily Injury Liability
The "30/60" portion of your policy refers to bodily injury.
- $30,000 per person: This is the maximum amount your insurance will pay for medical expenses, lost wages, and pain and suffering for a single person you injure in an accident.
- $60,000 per accident: This is the total cap for all people injured in a single incident. If you are involved in a multi-car pileup on the Airport Freeway (Hwy 183), this $60,000 limit can be exhausted almost instantly.
Property Damage Liability
The "25" refers to $25,000 in property damage liability. This covers repairs to the other driver’s vehicle, or stationary property like fences, buildings, or utility poles. In 2026, with the average price of a new vehicle often exceeding $50,000, the Texas minimum of $25,000 is frequently insufficient. If you cause an accident in Bedford that totals a late-model SUV, you could be held personally liable for the remaining balance once your insurance hits that $25,000 limit.
Personal Injury Protection (PIP) and Medical Payments
Texas insurance law requires insurance companies to offer you Personal Injury Protection (PIP) when you purchase a policy. In Bedford, where commuting to Fort Worth or Dallas is standard, PIP is a vital component of a policy.
Personal Injury Protection (PIP)
PIP is a "no-fault" coverage, meaning it pays out regardless of who caused the accident. It covers medical bills, funeral expenses, and—critically—80% of lost income if your injuries prevent you from working. Unless you reject PIP in writing, your Bedford insurer is required to include it. Most standard policies start with a $2,500 limit, but higher limits are available and often recommended for those without robust disability insurance.
Medical Payments (MedPay)
MedPay is similar to PIP but more restrictive. It covers medical and funeral expenses for you and your passengers but does not cover lost wages. Unlike PIP, MedPay may require subrogation, meaning if you win a settlement from the at-fault driver, your insurance company might ask to be reimbursed for the medical bills they paid.
Uninsured and Underinsured Motorist Coverage (UM/UIM)
Despite the Texas Sure program, which helps law enforcement verify insurance in real-time, a significant percentage of drivers in the DFW Metroplex remain uninsured. Furthermore, many drivers carry only the state minimums described above.
Uninsured/Underinsured Motorist (UM/UIM) coverage protects you when the "at-fault" driver has no insurance or lacks high enough limits to cover your total damages. In Bedford, this coverage typically mirrors your liability limits. If you have a 100/300/100 liability policy, you would ideally have 100/300/100 in UM/UIM.
There are two parts to this coverage:
- UM/UIM Bodily Injury: Pays for your medical bills, pain and suffering, and long-term treatment.
- UM/UIM Property Damage: Pays for repairs to your vehicle. In Texas, this usually comes with a $250 deductible.
Physical Damage Coverage: Collision and Comprehensive
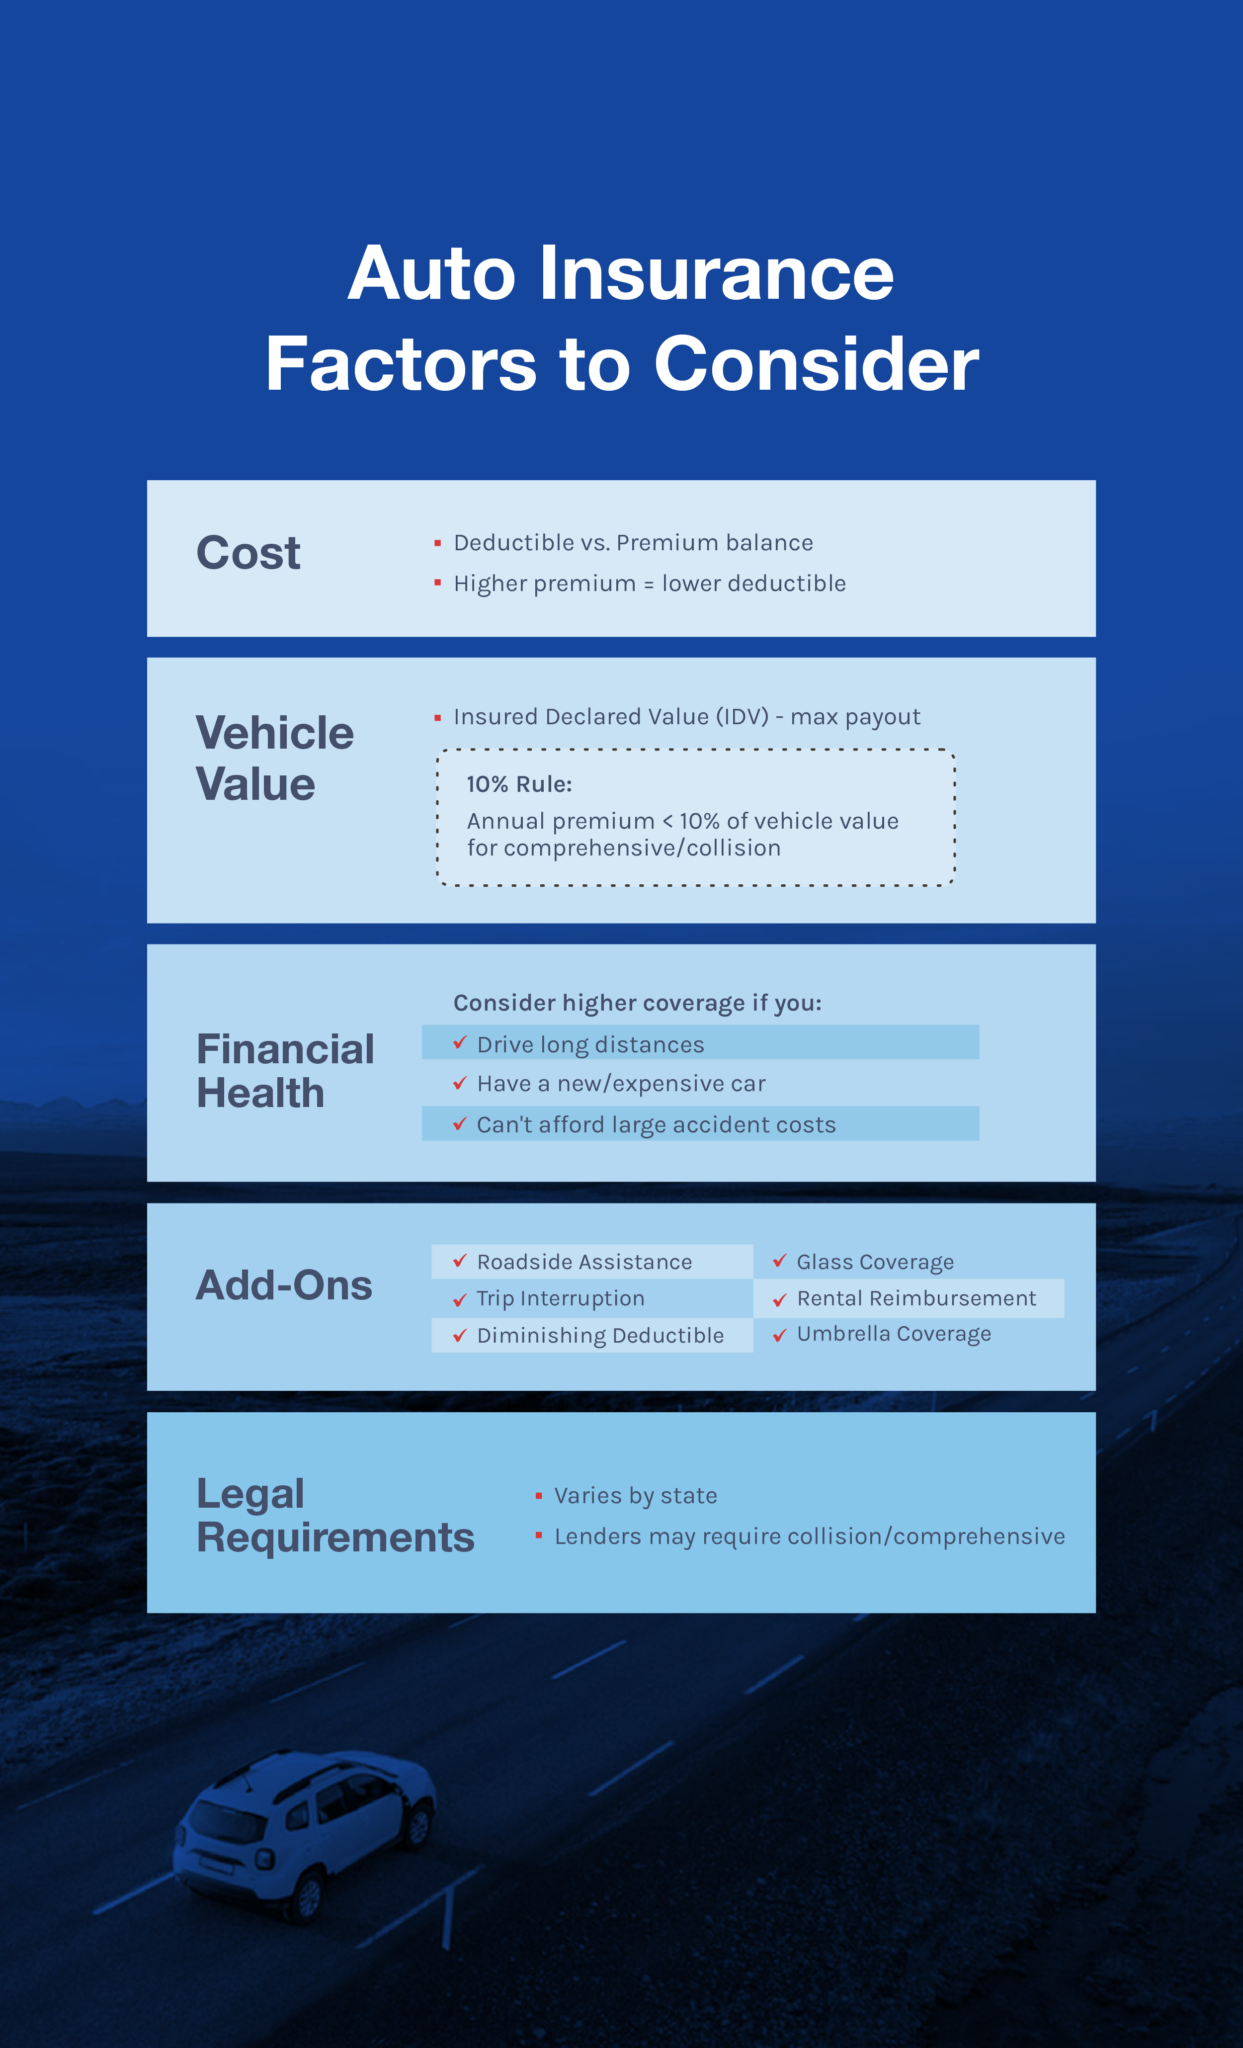
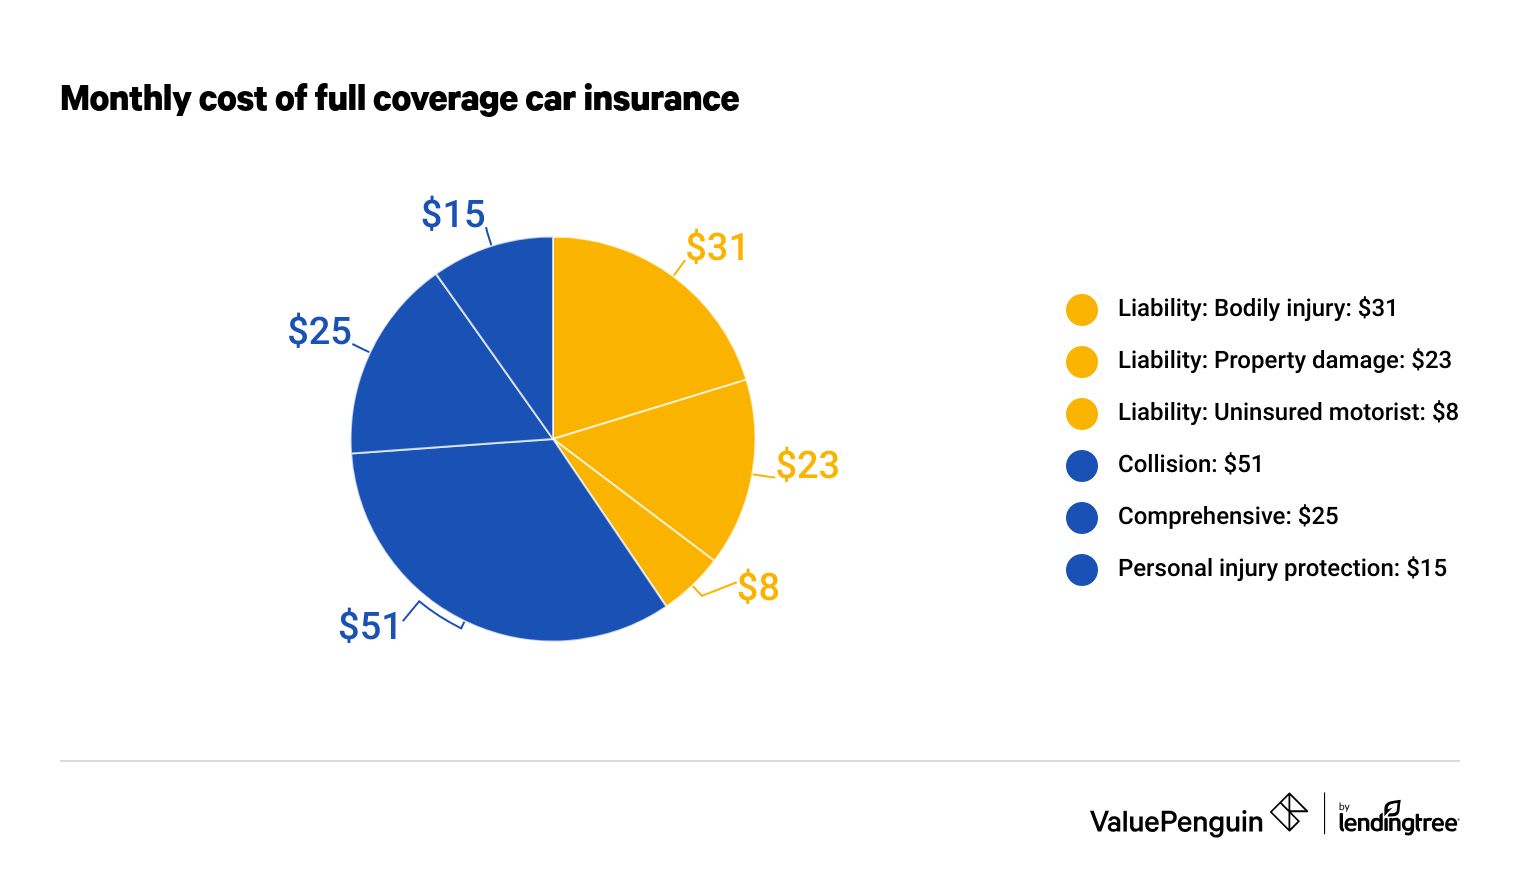
If you are financing or leasing a vehicle in Bedford, your lender will require "full coverage," which is a colloquial term for the combination of Collision and Comprehensive insurance.
Collision Coverage
This covers damage to your vehicle resulting from a collision with another vehicle or an object (like a guardrail or a tree). In Bedford’s high-traffic corridors, such as State Highway 121 and the 183/121 interchange, fender-benders are common. Collision coverage ensures that your vehicle is repaired or replaced (up to its actual cash value) regardless of fault, minus your chosen deductible.
Comprehensive Coverage (The "Hail" Protection)
For Bedford residents, Comprehensive coverage is perhaps the most important optional add-on. Often called "other than collision," it protects your vehicle from:
- Weather Events: North Texas is notorious for devastating hail storms and high winds.
- Theft and Vandalism: Protection if your car is stolen or keyed.
- Flood: Essential during the flash flooding events common in the HEB (Hurst-Euless-Bedford) area.
- Animal Strikes: Coverage for hitting a deer or other animals.
- Glass Breakage: Many insurers allow for a lower deductible specifically for windshield repairs.
Understanding "Actual Cash Value" (ACV) and Gap Insurance
It is a common misconception that auto insurance includes the "replacement cost" of your vehicle. In Bedford, as in the rest of Texas, standard policies pay the Actual Cash Value (ACV). ACV is the market value of the car at the moment of the loss, accounting for depreciation.
If you owe $35,000 on a truck but its ACV is only $28,000 following a total loss on Central Drive, your insurance will only pay the $28,000. Gap Insurance is an optional coverage that bridges this "gap" between the ACV and your loan balance. For residents driving newer vehicles with long-term financing, this is a critical inclusion to prevent significant out-of-pocket debt following an accident.
Supplemental Coverages and Endorsements
A comprehensive policy in Bedford often includes "quality of life" endorsements that handle the logistics of an accident.
- Rental Reimbursement: If your car is in a Bedford body shop for two weeks following a hail storm, this pays for a rental car (usually with a daily limit like $30 or $50).
- Towing and Labor: Provides roadside assistance if you break down or have a flat tire.
- Custom Parts and Equipment (CPE): If you have added aftermarket wheels, lift kits, or high-end audio systems, standard policies will not cover them unless you add a CPE endorsement.
Coverage Comparison Table
The following table outlines the differences between the legal minimums and a "comprehensive" policy structure typical for Bedford drivers in 2026.
| Coverage Type | Texas State Minimum | Recommended Bedford Policy | Purpose |
|---|---|---|---|
| Bodily Injury | $30k/$60k | $100k/$300k | Protects your assets from lawsuits. |
| Property Damage | $25,000 | $100,000 | Covers damage to modern, expensive vehicles. |
| PIP | Offered ($2.5k) | Accepted ($5k - $10k) | Covers your medical and 80% lost wages. |
| UM/UIM | Optional | Equal to Liability | Protects you from hit-and-runs/uninsured. |
| Collision | Not Required | Included ($500 Ded.) | Fixes your car after an accident. |
| Comprehensive | Not Required | Included ($500 Ded.) | Fixes car after hail, theft, or flood. |
| Gap Insurance | Not Included | Included (if financed) | Pays off loan if car is totaled. |
Local Factors Influencing Bedford Auto Insurance
When an actuary determines what your Bedford insurance includes and what it costs, they look at specific local data points. Bedford’s location in the center of the DFW Metroplex creates a unique risk profile.
- Traffic Density: The convergence of several major highways in the HEB area increases the statistical likelihood of multi-vehicle accidents.
- Weather Patterns: Bedford sits in a region prone to "hail alleys." Policies here almost always emphasize comprehensive limits.
- Crime Rates: While Bedford is generally considered safe, proximity to major urban centers influences rates for theft and catalytic converter theft.
- Commute Times: Longer commutes to Dallas or Fort Worth increase "time on road" exposure, which often results in higher premiums but necessitates higher liability limits.
How to Verify Your Coverage Limits
To ensure your policy actually includes what you think it does, you must review your Declarations Page (often called the "Dec Page"). This document summarizes your coverages, limits, deductibles, and the specific vehicles insured. In 2026, most carriers provide this via a mobile app or a secure online portal.
Check for the "Exclusions" section as well. Standard Bedford policies typically exclude coverage for:
- Using your vehicle for ride-sharing (Uber/Lyft) without a specific endorsement.
- Intentional acts of damage.
- Racing or off-roading.
- Wear and tear or mechanical breakdowns (this is what a warranty is for, not insurance).
Frequently Asked Questions
Does Bedford auto insurance cover hail damage automatically?
Hail damage is covered only if you have Comprehensive Coverage on your policy. It is not included in basic liability or collision coverage. Because Bedford is in a high-risk area for hail, most local agents strongly recommend a comprehensive plan with a manageable deductible.
Is Personal Injury Protection (PIP) mandatory in Bedford?
By law, insurance companies must offer you PIP. While you are not required to keep it, you must sign a written rejection if you do not want it. Most experts advise against rejecting it because it provides immediate financial relief for medical bills and lost wages regardless of who caused the accident.
Will my insurance cover a rental car while mine is being repaired?
This is only included if you have specifically added Rental Reimbursement coverage to your policy. It is not a standard feature of "full coverage." Most policies offer this for a small additional premium and provide a daily allowance for a rental vehicle for a set number of days (usually 30).
Does my policy cover me if I drive for a delivery service like DoorDash?
Standard personal auto insurance policies in Bedford usually exclude "business use" or "delivery for a fee." If you are using your vehicle for delivery or ride-sharing, you must add a Business Use Endorsement or a specific ride-share rider. Failing to do so could result in a denied claim.
What is the difference between UM and UIM?
Uninsured Motorist (UM) applies when the other driver has no insurance at all or if you are the victim of a hit-and-run. Underinsured Motorist (UIM) applies when the other driver has insurance, but their limits are too low to pay for the full extent of your injuries or vehicle damage.
Practical Recommendation for Bedford Drivers
For the average driver in Bedford, TX, relying on state minimum coverage is a significant financial risk. Given the rising costs of vehicle repairs and medical care in 2026, a policy should ideally include at least $100,000/$300,000/$100,000 in liability limits. Furthermore, because of the regional weather, Comprehensive coverage with a glass-specific deductible is highly recommended. Always verify that your policy includes Uninsured Motorist coverage to protect yourself against the high volume of underinsured drivers traversing the DFW highways. Review your Declarations Page annually to ensure your deductibles still align with your emergency savings.
Image Gallery
Select an image to open it in a new tab.



Mateo Castillo
Decentralized Finance and E-Payments Strategist
