
The FV factor, or Future Value factor, is a mathematical multiplier used in finance to determine the future worth of a present sum of money based on a specific interest rate over a set period. Its real value lies in its ability to quantify the time value of money, allowing investors, businesses, and individuals to make informed decisions about compounding growth, retirement planning, and capital project feasibility.
The Mathematical Foundation of the FV Factor
At its core, the Future Value (FV) factor is derived from the fundamental principle that a dollar today is worth more than a dollar tomorrow due to its potential earning capacity. When you invest money, it generates interest, and that interest, in turn, generates more interest—a process known as compounding. The FV factor is the mathematical bridge that allows you to calculate this trajectory.
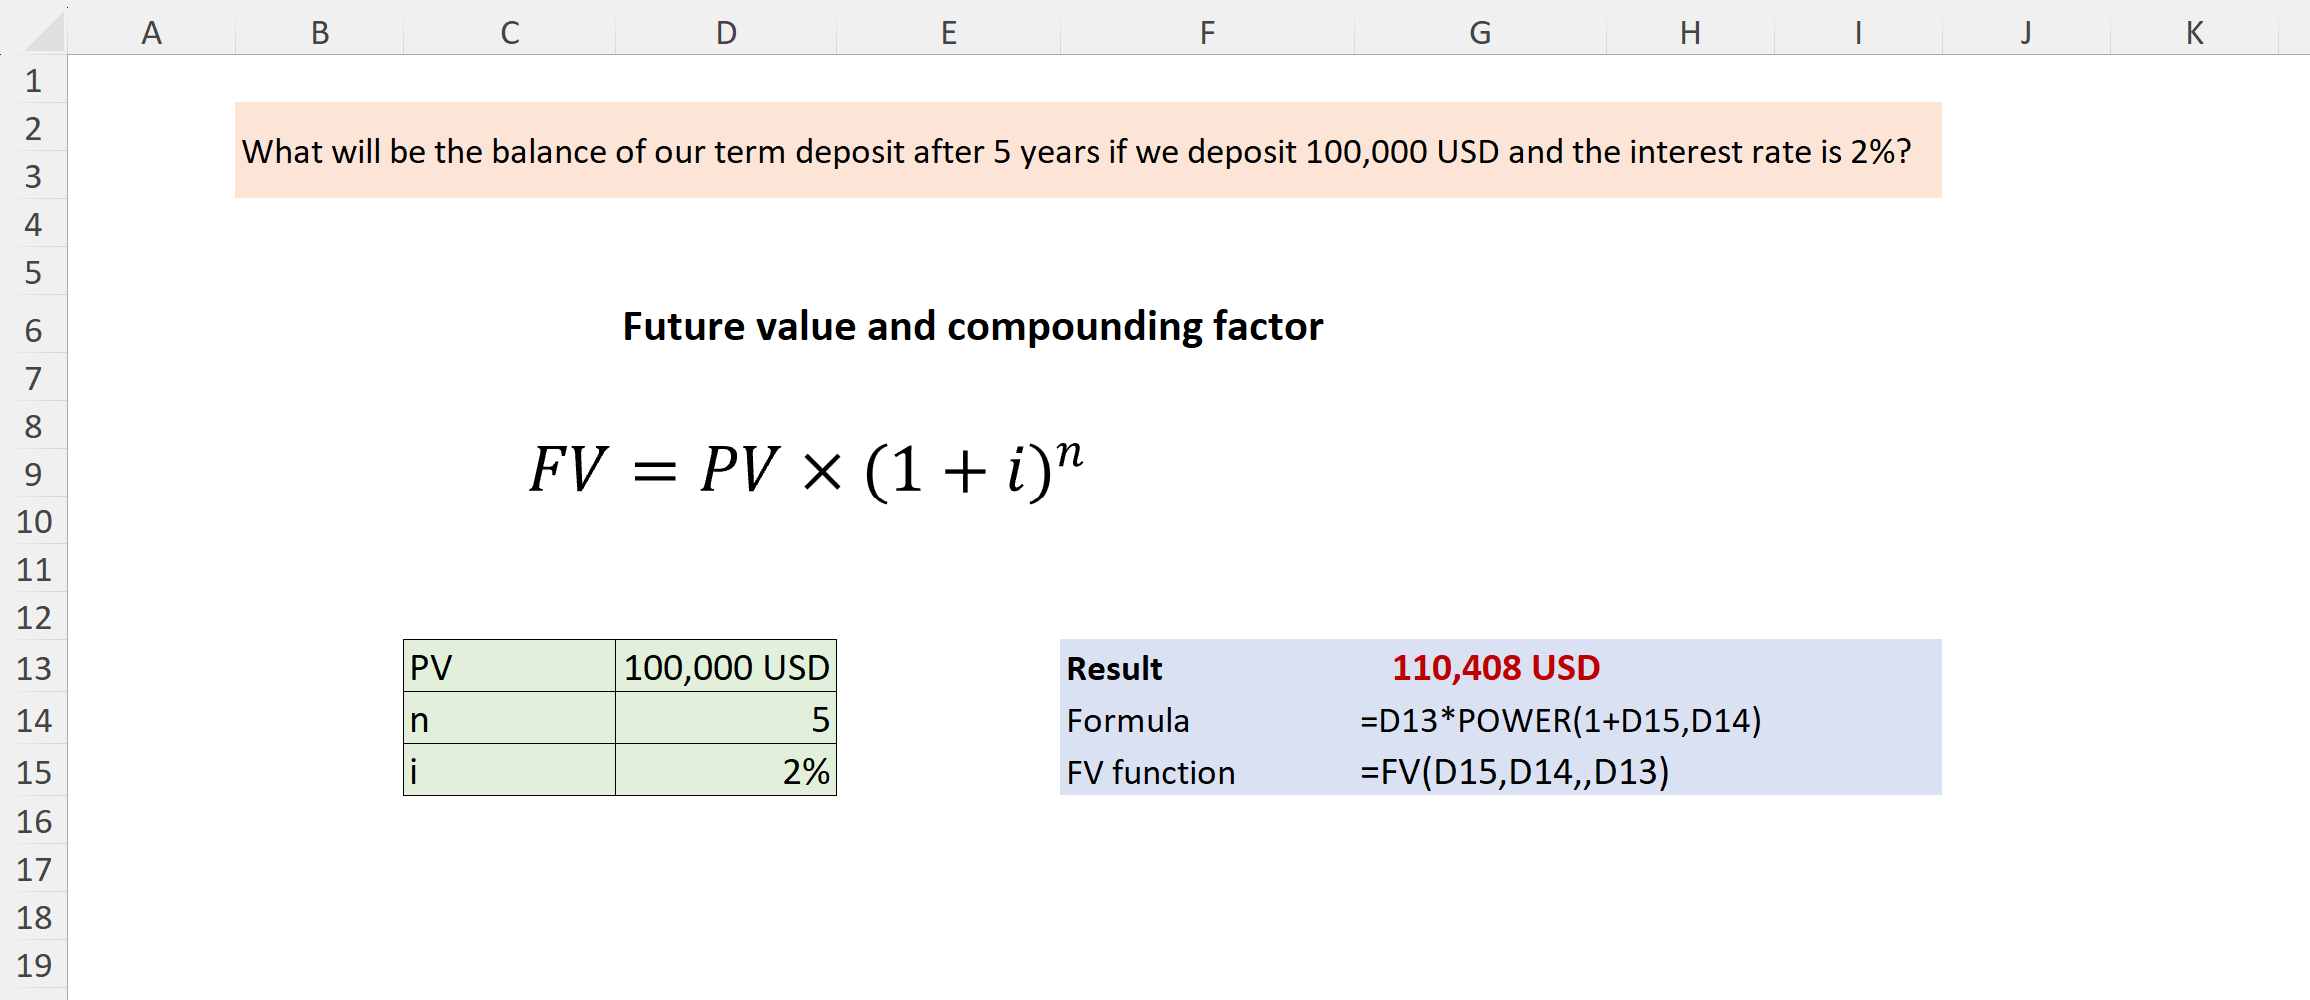
The formula for the FV factor is expressed as: FV Factor = (1 + r)^n
In this equation:
- r represents the interest rate or rate of return per period.
- n represents the number of compounding periods.
By multiplying any present value (PV) by this factor, you arrive at the future value of that investment. The power of this concept is not merely in the calculation itself, but in how it isolates the impact of time and interest rates on wealth accumulation. It transforms abstract financial projections into concrete, comparable figures.
Why the FV Factor Matters in Modern Financial Planning
The real value of the FV factor extends far beyond academic finance textbooks. In 2026, as individuals face complex economic landscapes and varying interest rate environments, understanding this multiplier is essential for several practical applications.
Long-Term Wealth Accumulation
For investors, the FV factor is a visualization tool. If you are debating between two investment vehicles—one with a 5% return and one with an 8% return—the FV factor makes the discrepancy in long-term outcomes starkly apparent. Over 20 or 30 years, that small percentage point difference, when applied through the FV factor, reveals a massive gap in terminal wealth. It helps investors resist the temptation to prioritize short-term liquidity over long-term compounding.
Business Capital Budgeting
Companies use the FV factor to evaluate the attractiveness of capital projects. If a business is considering purchasing new equipment, they must determine if the future revenue generated by that equipment—adjusted for the time value of money—exceeds the present cost of the investment. Without the FV factor, a manager might mistakenly view a nominal profit in five years as equal to a profit today, failing to account for the opportunity cost of the capital tied up in the project.
Inflation and Purchasing Power
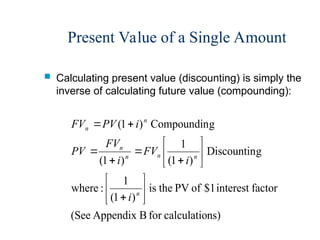
The FV factor is also the inverse of the present value calculation used to account for inflation. While we typically use the FV factor to see how our money grows, we can also use it to see how prices will rise. By applying an expected inflation rate as the "interest rate" in the FV formula, individuals can project the cost of living in the future, providing a clearer picture of how much they truly need to save to maintain their standard of living.
Comparative Analysis: The FV Factor in Different Scenarios
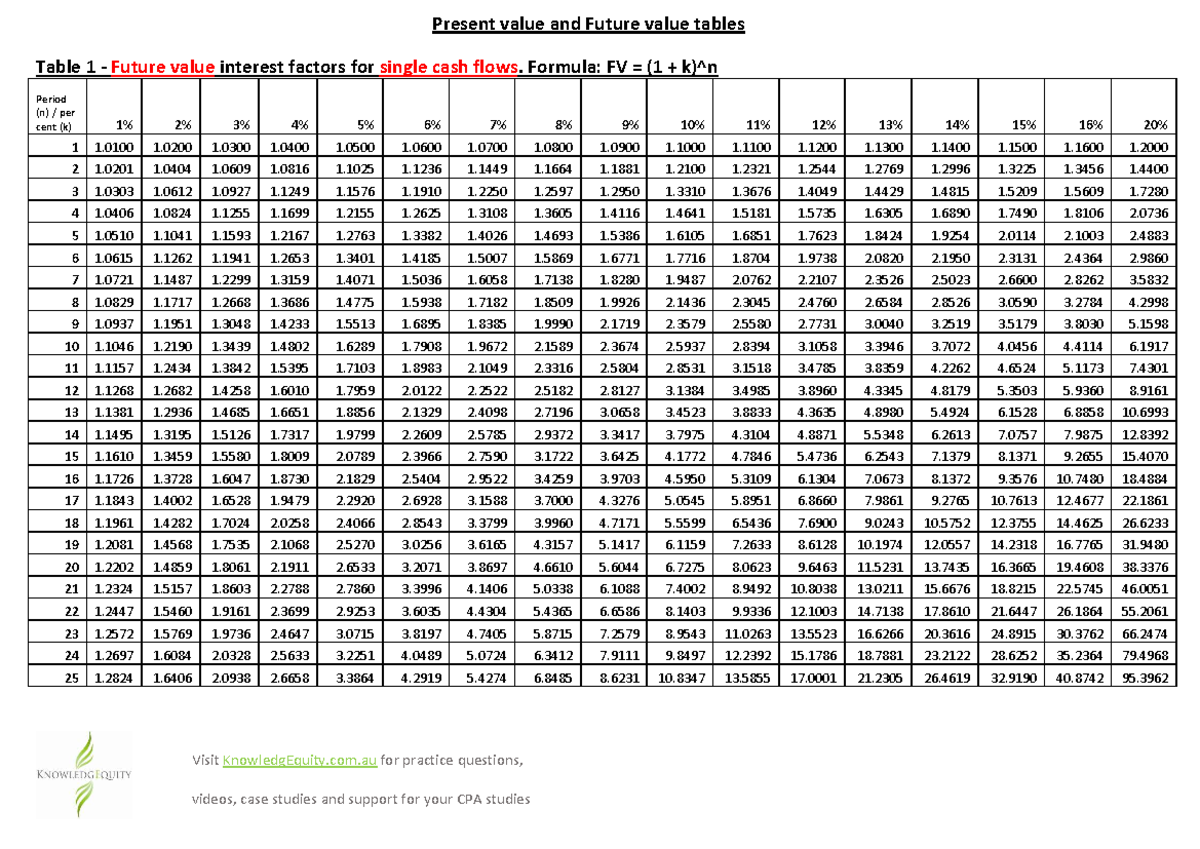
To understand how the FV factor behaves in varying economic conditions, it is helpful to look at how different timeframes and interest rates shift the result. Small changes in input values lead to non-linear changes in output due to the power of exponentiation.
| Scenario | Interest Rate (r) | Periods (n) | FV Factor | Resulting Growth on $10,000 |
|---|---|---|---|---|
| Conservative Savings | 3% | 10 years | 1.3439 | $13,439 |
| Moderate Investment | 6% | 10 years | 1.7908 | $17,908 |
| Aggressive Growth | 9% | 10 years | 2.3674 | $23,674 |
| Long-term Compounding | 6% | 30 years | 5.7435 | $57,435 |
The table above illustrates the "real value" of patience and interest rates. Note how the FV factor jumps significantly when the timeframe increases from 10 to 30 years. This demonstrates that the duration of the investment is often just as critical as the rate of return itself.
Limitations and Common Misconceptions
While the FV factor is a vital tool, it is not a crystal ball. Its accuracy is entirely dependent on the precision of the inputs provided.
The Assumption of Static Rates
One of the most common mistakes in using the FV factor is assuming that the interest rate will remain constant over the entire duration. In reality, economic conditions change. A fixed-rate bond may provide a predictable FV factor, but investments in equities or variable-rate accounts involve market volatility. If you rely on a static FV factor for a volatile investment, you may be left with a significant shortfall.
Tax Implications
The standard FV factor calculation typically ignores taxes. In a real-world scenario, the interest or capital gains earned are often subject to taxation. When calculating the real value of an investment, you must often use an "after-tax rate of return" to ensure that your future value projections reflect what will actually end up in your pocket.
Opportunity Cost Overlooks
Users often focus only on the growth of the money they have, failing to factor in what they could have done with that money otherwise. The FV factor helps identify the future worth of an asset, but it does not tell you if that asset is the best possible use of those funds compared to other opportunities.
How to Apply the FV Factor in Personal Finance
If you want to integrate the FV factor into your own decision-making process, follow these steps to ensure accuracy and relevance:
- Define Your Goal: Determine the specific dollar amount you are evaluating. This is your Present Value (PV).
- Estimate a Realistic Rate: Be conservative. Using an overly optimistic interest rate will inflate your expected future value and lead to poor planning. Base your rate on historical performance of similar asset classes, adjusted for current 2026 economic conditions.
- Determine the Timeline: Be clear about when you need the money. If you have multiple goals (e.g., house down payment in 5 years, retirement in 30), calculate each one separately.
- Perform the Calculation: Use the formula (1 + r)^n. If calculating for multiple years with varying rates, you must perform the calculation sequentially (Year 1 result becomes Year 2 principal).
- Review the Output: Look at the resulting figure. Does it meet your requirement? If not, you must adjust either your present contribution (PV), your timeline (n), or seek a different investment strategy that offers a higher rate (r).
Frequently Asked Questions
Is the FV factor the same as compound interest?
The FV factor is the mathematical coefficient used to calculate the effects of compound interest. While compound interest is the phenomenon of growth, the FV factor is the specific number you multiply by your principal to determine that growth.
How does inflation affect the value of my FV calculation?
Inflation acts as a negative interest rate. If you want to know the "real" purchasing power of your money in the future, you should subtract the expected inflation rate from your nominal rate of return before applying the FV factor.
Does the FV factor apply to debt?
Yes. Lenders use the FV factor to calculate how much you will owe in the future on an unpaid balance. It is effectively the same math used in reverse, helping you understand how interest charges accumulate on credit cards or loans over time.
Can I use the FV factor for non-monetary assets?
While the FV factor is designed for currency, it can be used for any asset that appreciates at a predictable rate, such as commodities or certain real estate assets. However, because these assets are less predictable than bank interest, the factor serves only as an estimate.
Why is the FV factor higher for longer time periods?
The FV factor increases exponentially because of the compounding effect. Each year, your interest earns interest, and that new interest earns even more interest the following year. The longer the duration, the more pronounced this "snowball effect" becomes.
Practical Next Steps for Your Portfolio
To make the most of the FV factor, stop viewing it as a theoretical exercise and start using it as a diagnostic tool. Review your current savings and investment accounts. Pick one significant goal—such as a retirement target or a major purchase—and calculate the FV factor for your current contributions over your desired timeline.
If the result is lower than your target, the math will show you exactly which lever you need to pull: increase your current savings (PV), extend your timeline (n), or adjust your asset allocation to seek a higher rate of return (r). By using the FV factor to objectively measure these variables, you move from guesswork to a data-driven strategy for your financial future.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
