
Opening a traditional bank account without any form of identification is virtually impossible in 2026 due to stringent global anti-money laundering regulations. However, you can access "low-KYC" fintech accounts, digital wallets, and decentralized finance platforms that accept alternative digital IDs or offer tiered verification levels, allowing limited financial activity with minimal documentation.
The financial landscape of 2026 has been shaped by two opposing forces: the tightening of international security protocols and the rapid advancement of digital identity frameworks. While the days of walking into a branch and opening an anonymous account are long gone, the definition of "identification" has expanded. Today, the "unbanked" or privacy-conscious individuals have more options than ever, provided they understand the trade-offs between anonymity, security, and account functionality.
The Regulatory Framework: Why ID is Required
To understand how to bypass traditional ID requirements, one must first understand why they exist. Since the early 2020s, the Financial Action Task Force (FATF) and national regulators like FinCEN in the United States and the European Banking Authority (EBA) have doubled down on Know Your Customer (KYC) and Anti-Money Laundering (AML) protocols.
These regulations are designed to prevent terrorism financing, tax evasion, and money laundering. By 2026, these rules have evolved into "Persistent Monitoring," where banks don't just check your ID once; they continuously verify your identity through behavioral patterns and biometric data. For a regulated financial institution, failing to identify a customer can lead to multi-billion dollar fines. Consequently, any service that claims to be a "bank" while requiring zero identification is likely either operating illegally or is not technically a bank.
Alternative Financial Services with Minimal ID
If you do not possess a standard government-issued passport or driver's license, or if you prefer not to share them for privacy reasons, several "near-bank" alternatives provide essential financial services.
1. E-Wallets and "Lite" Neobank Accounts
Many fintech companies offer tiered verification. In a tiered system, you can open an account with just a verified phone number or email address. This is often referred to as a "Level 1" or "Lite" account.
- Capabilities: These accounts usually allow you to receive small transfers, hold a limited balance (often under $1,000 or €1,000), and make online purchases.
- Limitations: You cannot perform large wire transfers, and you often cannot withdraw cash from ATMs without upgrading to a higher verification tier.
- Identification Used: Instead of a passport, these services may use "soft" verification, such as verifying your social media footprint, mobile phone contract history, or email age.
2. Prepaid Debit Cards
Prepaid cards remain one of the most accessible ways to participate in the digital economy without a formal bank account. In 2026, you can still purchase non-reloadable prepaid cards at retail locations in many jurisdictions using cash.
- Anonymous Usage: These cards are not linked to a bank account. You pay for the card and the load value upfront.
- Usage Constraints: They are primarily for one-time or short-term use. Because of the "Travel Rule" updates in 2025, reloadable cards now almost universally require some form of ID verification to prevent them from being used for large-scale money laundering.
3. Digital Identity Wallets
By 2026, many countries have moved toward Digital ID Wallets (such as the EU's Digital Identity Wallet or various U.S. state-level mobile IDs). While these are forms of identification, they allow for "selective disclosure."
When opening an online account, you don't send a photo of your ID; instead, your digital wallet sends a cryptographically signed "token" that proves you are a real person of a certain age or residency without revealing your full name or address to the bank's human employees. This provides a "no-ID" experience from a privacy perspective while still satisfying the bank's legal requirements.
Decentralized Finance (DeFi): The Non-Custodial Path
For those seeking a total departure from traditional banking identification, Decentralized Finance (DeFi) is the primary solution. In DeFi, you do not open an account with a company; you interact with smart contracts on a blockchain using a non-custodial wallet.
How DeFi Replaces Banking
- No Application Process: There is no "sign-up" button that requires an ID. You simply generate a private key and a public address.
- Global Accessibility: As long as you have an internet connection, you can access lending, borrowing, and interest-bearing "savings" protocols.
- Stablecoins: By using stablecoins (cryptocurrencies pegged to the USD or Euro), you can avoid the volatility of Bitcoin while still keeping your funds outside the traditional banking system.
The Major Caveats of DeFi
The "On-Ramp" and "Off-Ramp" problem is the primary hurdle. While the DeFi wallet itself requires no ID, moving "real" money (fiat currency) from a physical job or a cash stash into that wallet almost always requires a regulated exchange, which will ask for ID. To stay completely ID-free, users must rely on peer-to-peer (P2P) exchanges or "Bitcoin ATMs" that allow cash transactions, though these often carry high fees and are increasingly regulated.
Comparison of Low-ID Financial Options in 2026
The following table compares the most common methods for managing money with minimal or alternative identification.
| Feature | E-Wallets (Lite) | Prepaid Cards (Retail) | DeFi Wallets | Digital ID Accounts |
|---|---|---|---|---|
| Verification Level | Low (Phone/Email) | None (at purchase) | None | Medium (Biometric/Token) |
| Spending Limits | Low (Tiered) | Very Low | Unlimited | High |
| ATM Access | Rare | Yes (Limited) | No (Requires Exchange) | Yes |
| Deposit Insurance | No | No | No | Yes (Usually) |
| Privacy Rating | Moderate | High | Very High | Moderate/High |
| Primary Use Case | Small online shopping | Temporary use/Cash conversion | Privacy/Wealth growth | Modern secure banking |
Steps to Open a Low-ID Account
If you need to set up a financial tool immediately with minimal documentation, follow these steps to ensure you choose the most secure and functional option.
Step 1: Determine Your Primary Need
Are you trying to receive a salary, pay a specific bill, or simply hide your spending habits? If you need to receive a salary, a DeFi wallet is likely useless as most employers won't pay into one. In this case, a neobank with tiered verification (starting at the lowest level) is your best bet.
Step 2: Choose a Platform
Research fintechs that explicitly offer "unbanked" or "basic" accounts. In the EU, for example, the "Right to a Basic Bank Account" ensures that residents can get a simplified account even without a permanent address, though some ID is still required. In the US, "Second Chance" banking apps often have lower barriers to entry.
Step 3: Use Alternative Identification
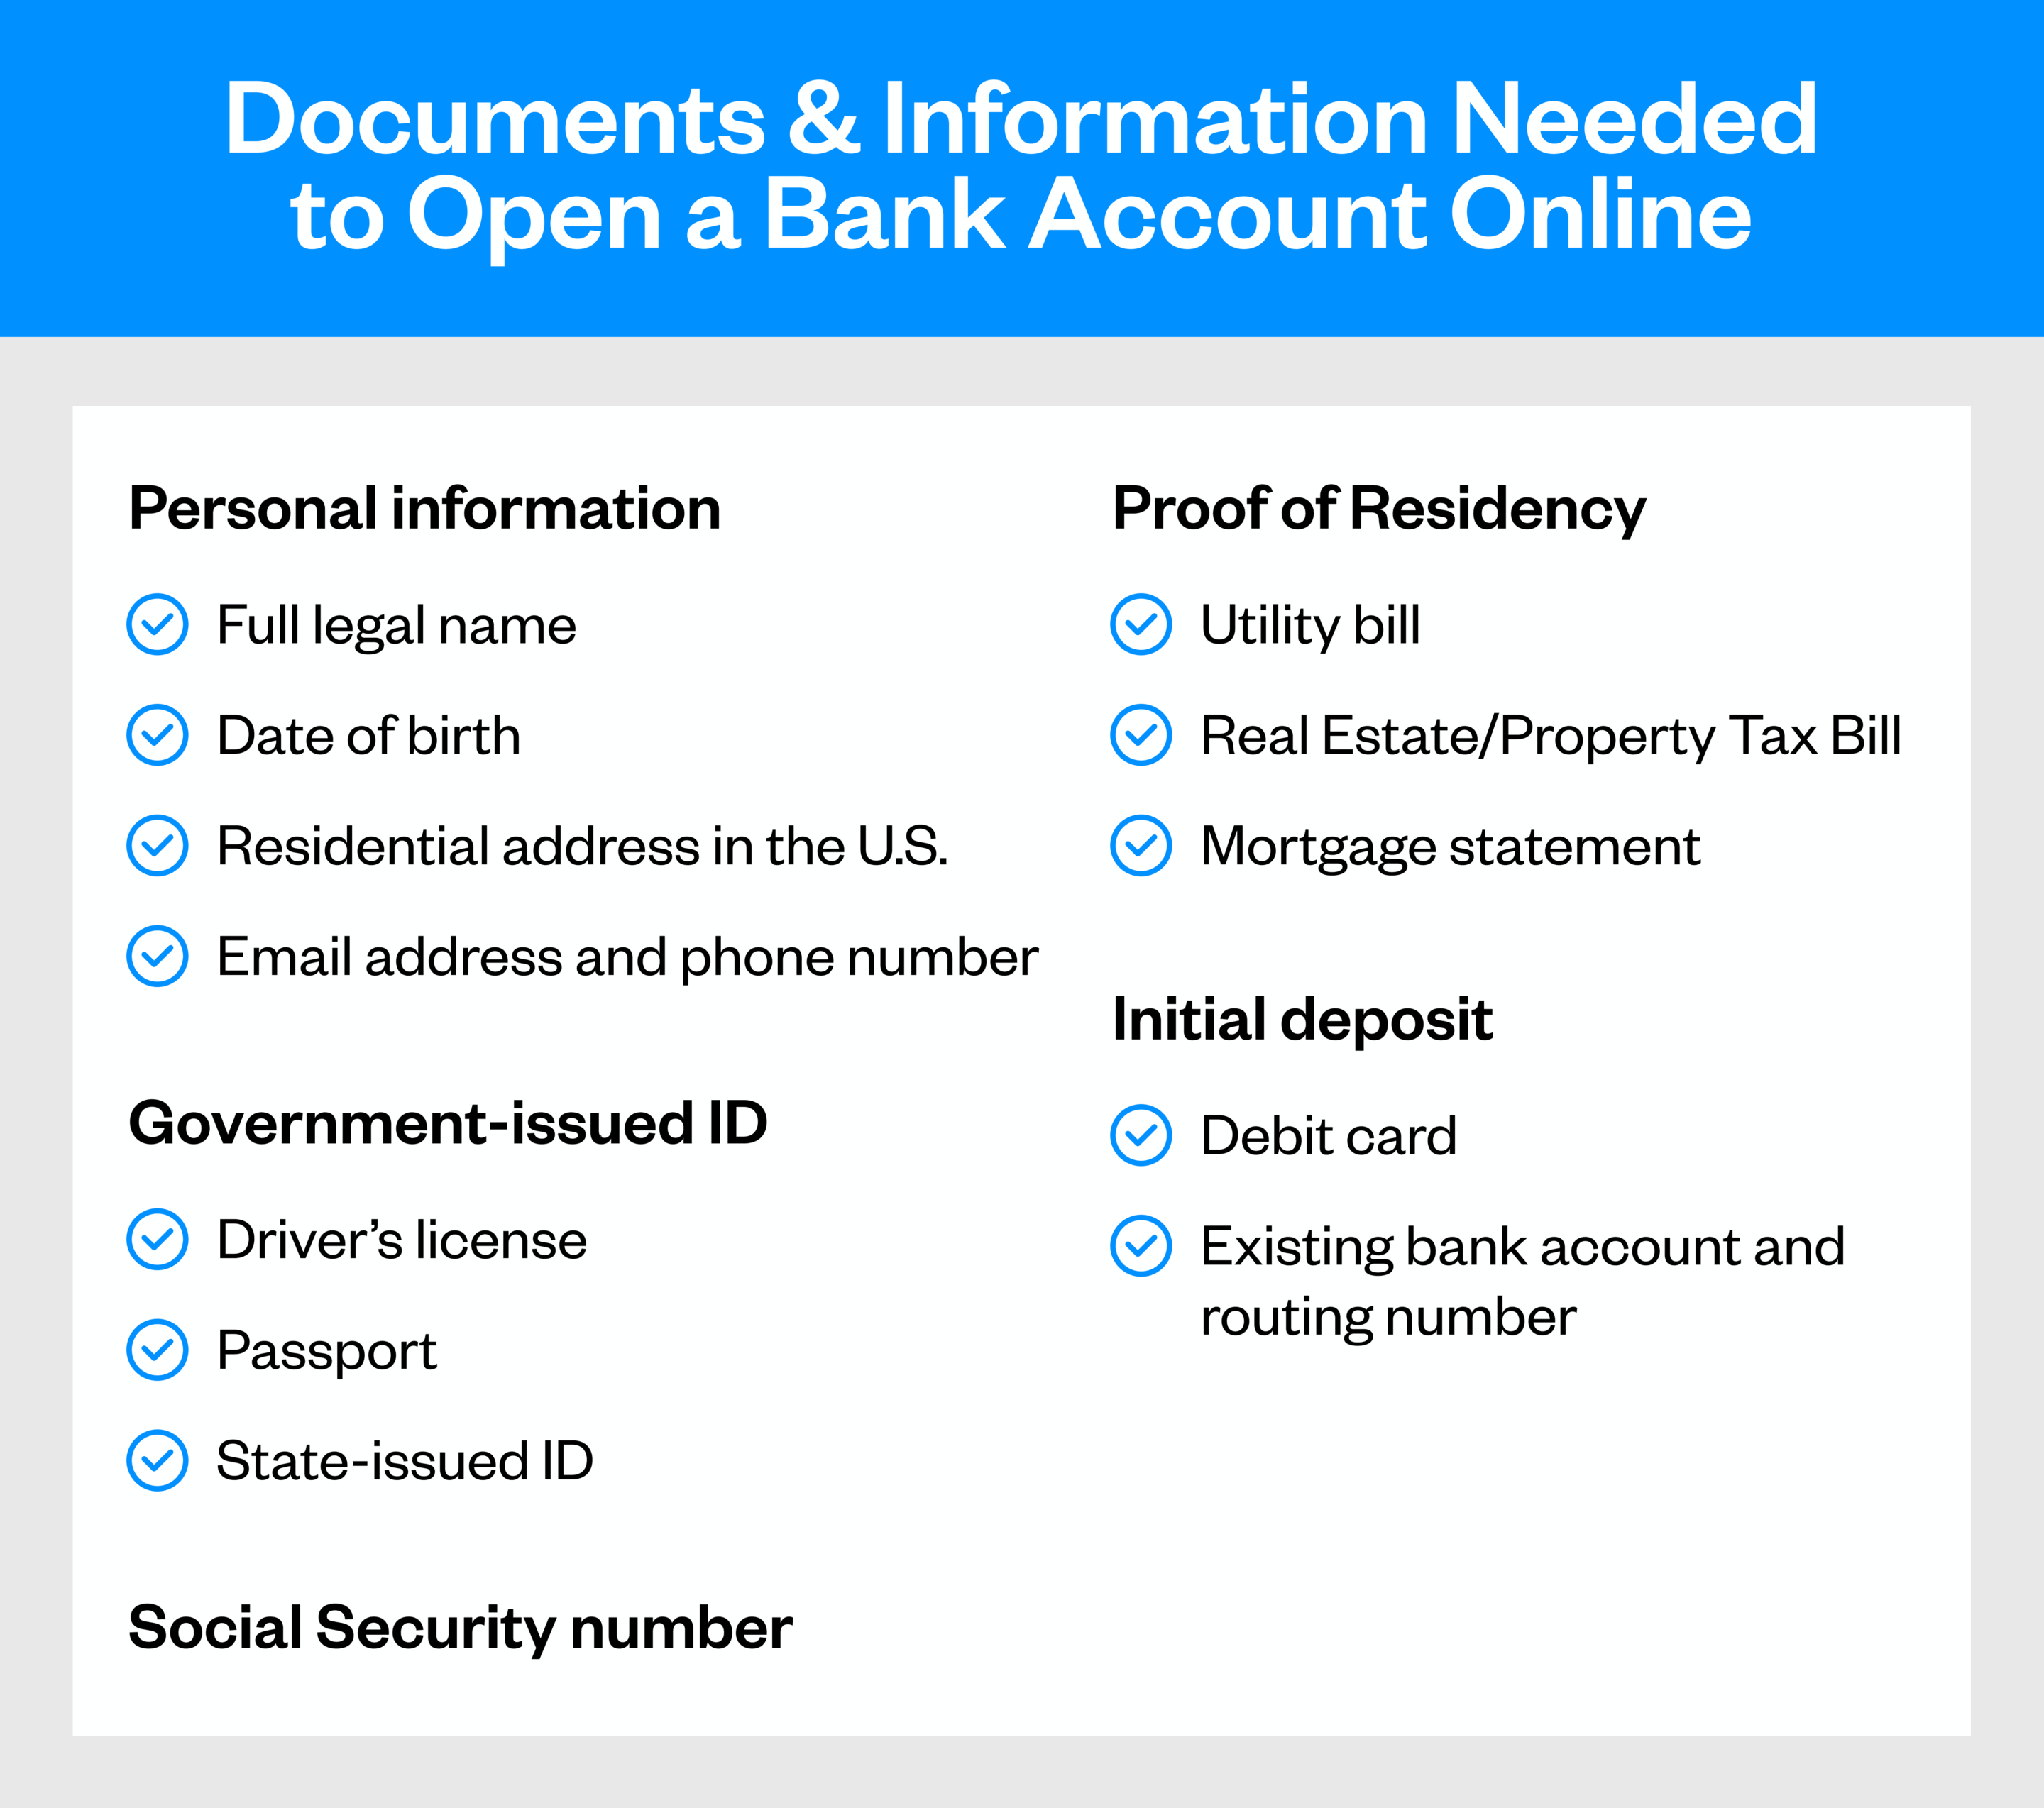
If you lack a passport, check if the platform accepts:
- Voter registration cards.
- Utility bills in your name.
- Student IDs or employee badges.
- Verified digital identity tokens from a third-party provider.
Step 4: Verify the Fee Structure
Accounts that require less identification often "pay" for that risk by charging higher fees. Watch out for monthly maintenance fees, "inactivity" fees, and high conversion rates when moving money between currencies.
The Risks of Banking Without Full Identification
While the appeal of an ID-free account is clear, the risks are significant. Financial institutions treat low-ID accounts as high-risk.
- Sudden Account Freezes: If an automated system flags a transaction as suspicious, a low-ID account is much more likely to be frozen instantly. Without a verified identity on file, "unfreezing" the account can be a bureaucratic nightmare that takes months.
- Lack of Legal Protection: Many non-traditional financial apps are not members of the FDIC (U.S.) or national deposit guarantee schemes. If the company goes bankrupt, your money may be lost forever.
- Target for Scams: Platforms that advertise "no ID needed" are often predatory or outright scams. They may allow you to deposit money but then demand "verification fees" or "taxes" before you can withdraw it.
- Limited Recourse for Fraud: If someone steals the funds from your anonymous prepaid card or DeFi wallet, there is no "fraud department" to call. The anonymity that protects you also protects the thief.
The Future of "Identity-Less" Finance
Looking ahead past 2026, the trend suggests that physical ID cards will become obsolete, replaced by Zero-Knowledge Proofs (ZKPs). This technology allows a person to prove they have the right to a bank account without revealing who they are. While this technology is currently in the pilot phase for major banks, it represents the most likely path for users who want the security of a regulated bank with the privacy of an anonymous account.
For now, the best strategy is a hybrid approach: use a regulated, identified account for your main income and "life" expenses, and use DeFi or prepaid systems for the portions of your financial life where you prefer enhanced privacy.
Frequently Asked Questions
Can I use a fake ID to open an online bank account?
No. By 2026, AI-driven verification systems can detect forged documents and "deepfake" biometric videos with nearly 100% accuracy. Attempting to use a fake ID is a felony in most jurisdictions (financial fraud) and will result in a permanent ban from the banking system and potential criminal prosecution.
Are there any "offshore" banks that don't require ID?
Most offshore jurisdictions have adopted the Common Reporting Standard (CRS) and "Automatic Exchange of Information" (AEOI) protocols. While some "shadow banks" in unregulated territories may offer no-ID accounts, they are extremely risky and often serve as fronts for criminal enterprises. Your funds are never safe in such institutions.
Do Bitcoin ATMs require identification?
In 2026, most Bitcoin ATMs require at least a phone number for small transactions and a government ID scan for larger ones. Some older machines or those in specific jurisdictions may still allow small cash-to-crypto exchanges without a scan, but these are becoming increasingly rare.
Can I open a business bank account without ID?
No. Business accounts require "Ultimate Beneficial Owner" (UBO) verification. Regulators require banks to know exactly which human being owns the company. Even if the business is an LLC or a DAO (Decentralized Autonomous Organization), the individuals controlling the funds must be identified.
What is a "Money Service Business" (MSB) and is it different from a bank?
Yes. Many apps that feel like banks (like certain remittance apps) are actually MSBs. They have different regulatory requirements. While they still require ID for most things, they might offer higher flexibility for small-dollar "guest" transactions compared to a traditional chartered bank.
Practical Recommendation
If you are currently without traditional identification, your first action should be to seek a "Basic Bank Account" or a "Financial Inclusion Account" from a major neobank. These are specifically designed for those with limited documentation and are legally mandated in many regions. If privacy is your main concern, look into non-custodial DeFi wallets and learn how to use Privacy Coins or Mixing Services (where legal), but be prepared for a steep learning curve and the lack of any "undo" button for your transactions.
Image Gallery
Select an image to open it in a new tab.

Lars Thomsen
Global Labor Markets and Economic Strategy Editor
