Understanding Your Ability to Maintain Multiple Life Insurance Policies in New York
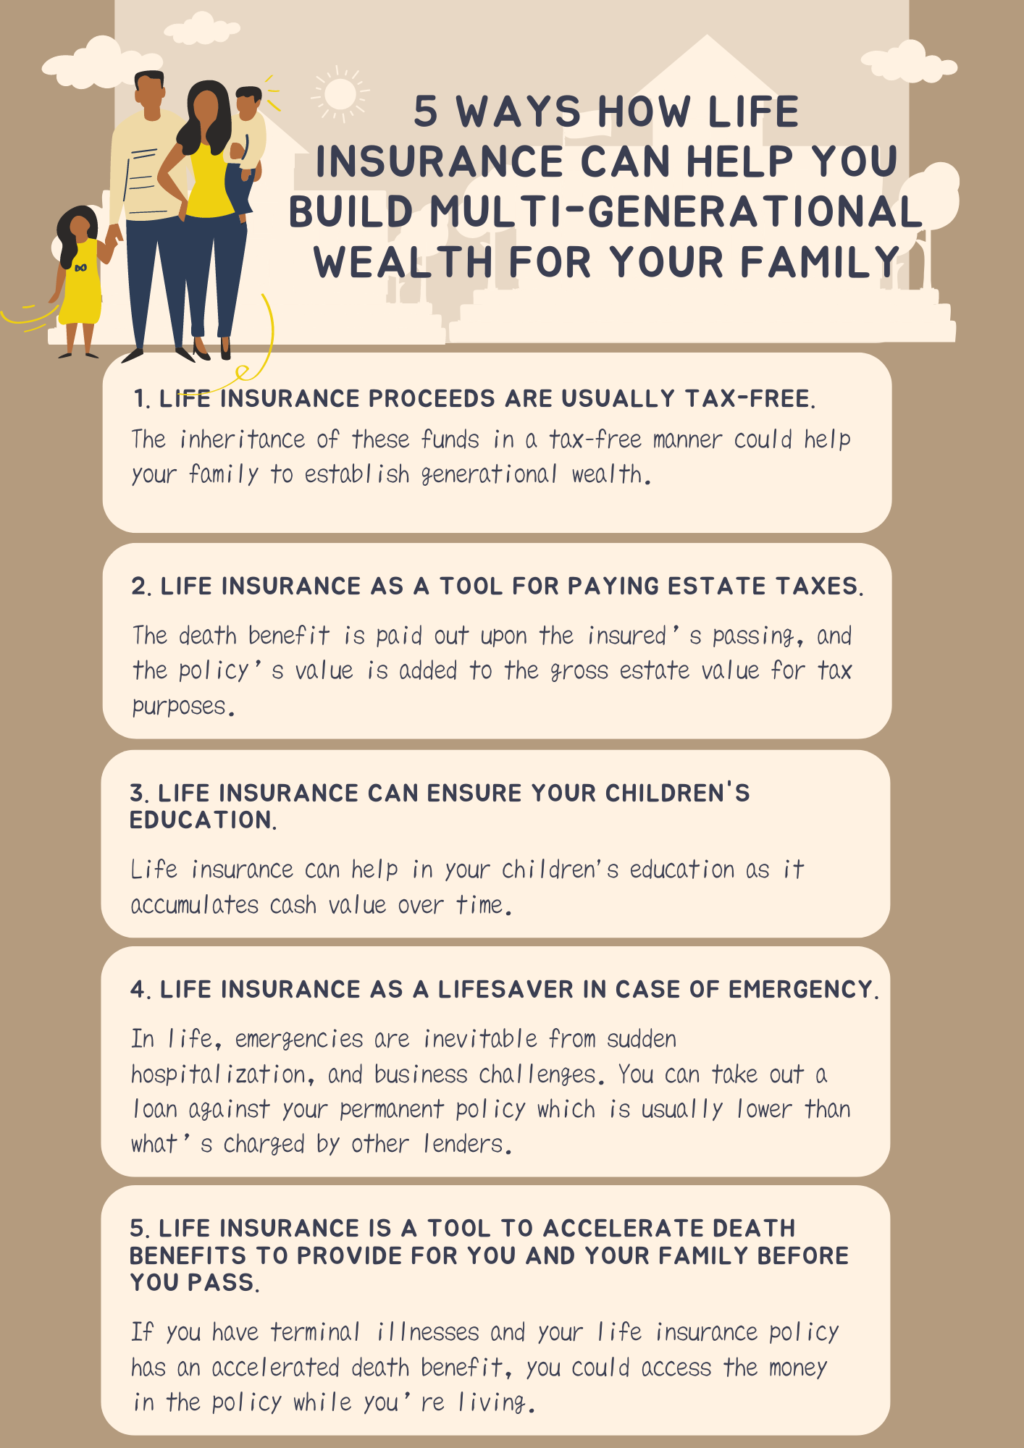
Yes, you can legally own and maintain multiple life insurance policies in New York. State law does not set a limit on the number of individual life insurance contracts an individual may purchase, provided the total coverage amount remains within the bounds of "insurable interest" and does not violate the underwriting guidelines of the specific insurance carriers involved in 2026.
The Legal Framework of Life Insurance in New York
In New York, the regulation of insurance is governed by the New York State Department of Financial Services (DFS). The state’s insurance laws do not contain a prohibition against stacking or holding multiple policies simultaneously. Whether you are looking to supplement an existing employer-provided group life insurance plan with a private term life policy, or you wish to layer different types of permanent coverage, the law permits these arrangements.
However, the primary limiting factor in the eyes of insurers is the concept of insurable interest. An applicant must demonstrate that they have a legitimate financial interest in the preservation of the life insured. In the context of purchasing policies on your own life, this is inherently satisfied because you are the insured. When you apply for a new policy, the insurance carrier will require full disclosure of all existing life insurance coverage. This is not to restrict your right to purchase more, but to assess the risk and ensure that the total amount of insurance is proportional to your financial obligations, income, and estate planning needs.
Why Individuals Acquire Multiple Policies
There are several strategic reasons why someone might opt for multiple policies rather than a single, large-coverage contract.
- Diversification of Coverage: You may have a baseline policy through your employer. If you change jobs, that coverage often terminates. Purchasing an individual policy ensures your family is protected regardless of your employment status.
- Layering for Financial Goals: Some individuals use a "laddering" strategy. For instance, you might purchase a 10-year term policy to cover the remaining balance of a mortgage and a separate 30-year term policy to provide income replacement for your dependents until they reach financial independence.
- Estate Planning Needs: High-net-worth individuals often maintain multiple permanent life insurance policies to cover different tax liabilities or to facilitate the transfer of assets to heirs while minimizing the impact of estate taxes.
- Gradual Coverage Expansion: You may choose to purchase a policy early in life when premiums are lower. As your financial responsibilities grow—such as starting a family or expanding a business—you may add a second policy to increase your total death benefit without canceling the older, more affordable contract.
The Underwriting Process and Disclosure
When you apply for an additional life insurance policy in New York, the insurance carrier will conduct a thorough underwriting review. A critical part of this process is the "Application for Insurance," which explicitly asks, "Do you have any other life insurance currently in force?"
It is imperative that you answer this question with total honesty. Failing to disclose an existing policy is considered a material misrepresentation. In the insurance industry, if an insurer discovers that you omitted existing coverage, they may deny the new application, rescind an existing policy, or, in extreme cases, refuse to pay out a death benefit to your beneficiaries if the fraud is discovered during the contestability period.
Underwriters use this information to determine your total "line of insurance." They want to see that your total death benefit is reasonable relative to your annual income. For example, if you earn $100,000 per year, an insurance company might be hesitant to issue a new policy if it pushes your total coverage to $20 million, as this could suggest a moral hazard or an unreasonable financial motive.
Comparison: Single Policy vs. Multiple Policies
Choosing between consolidating into one policy or maintaining multiple contracts involves weighing convenience against flexibility.
| Feature | Single Large Policy | Multiple Smaller Policies |
|---|---|---|
| Administration | Simplified; one premium payment. | Requires managing different due dates. |
| Flexibility | All-or-nothing coverage. | Allows dropping specific coverage as needs decrease. |
| Underwriting | One medical exam. | Each policy may require individual underwriting. |
| Employer Dependency | Independent of employment. | Can mix employer-paid and private plans. |
| Cost | Often cheaper due to volume bands. | May be higher due to individual policy fees. |
Practical Steps to Acquiring Additional Coverage
If you have decided that adding a new policy is the right financial move, follow these structured steps to ensure the process goes smoothly:
- Conduct a Needs Analysis: Evaluate your current financial obligations. Include debts, future education costs for children, and the amount of income your beneficiaries would need to maintain their standard of living.
- Verify Existing Benefits: Request a summary of benefits from your employer’s HR department to see exactly what is covered and whether that coverage is portable.
- Consult with a Licensed Producer: Work with an insurance producer licensed in New York. They can help you navigate the nuances of the state’s insurance code and ensure you are not over-insuring yourself, which can lead to unnecessary premium costs.
- Complete the Application Honestly: As noted, disclose all existing policies. Be prepared to provide details regarding the company, the policy number, the type of insurance, and the face amount of each policy.
- Review the Medical Requirements: Depending on the face amount of the new policy, you may need to undergo a paramedical exam. Having a clear record of your health status helps expedite this process.
Common Pitfalls to Avoid
While having multiple policies is beneficial for many, it does come with potential challenges that you should monitor.
Overpaying through Policy Fees: Every individual life insurance policy usually carries a "policy fee" or "administrative fee" baked into the premium. If you have four small policies, you are paying that fee four times. Consolidation is sometimes more cost-effective if your needs have stabilized.
Managing Beneficiary Designations: One of the most common mistakes is forgetting to update beneficiary information across all policies. If you undergo a life event, such as a divorce or the birth of a child, you must ensure that your designations are consistent with your current wishes across every individual contract.
Policy Lapse: If you are paying premiums for multiple policies, the likelihood of missing a payment—leading to an accidental lapse—increases. Consider setting up automatic bank drafts for all policies to maintain coverage integrity.
Navigating Employer-Provided vs. Individual Policies
It is a common misconception that having a large life insurance policy through work negates the need for a private one. Most group life insurance policies provided by employers are tied to your employment. If you leave your job, you may lose that coverage entirely or be forced to convert it into an individual policy at a significantly higher rate than a market-priced term policy.
In New York, the most robust financial strategy often involves keeping a base of private, individual term insurance that you own and control, while utilizing your employer’s group life insurance as a secondary, supplemental layer of protection. This hybrid approach provides stability, as your private policy will remain in effect regardless of changes in your career or employment status.
Professional Guidance and Regulatory Protection
The New York State DFS provides substantial protections for policyholders. If you ever feel that an insurance carrier is unfairly denying you coverage or misrepresenting your ability to hold multiple policies, you have the right to contact the department’s consumer services division. They provide resources to help residents understand their rights under New York insurance law.
Furthermore, if you are considering replacing an existing policy rather than adding to it, be aware of "replacement regulations." New York has specific rules requiring producers to provide you with a "Disclosure Statement" that compares the benefits and costs of your current policy against the new one. This is designed to prevent "churning"—a practice where an agent encourages you to replace a policy solely to generate a new commission, which often disadvantages the consumer.
Recommended Next Actions
Before applying for a new policy, gather the declarations pages of all current life insurance policies you hold. Create a simple spreadsheet documenting the coverage amount, premium cost, and beneficiary for each. Once you have this clear view of your current position, contact a qualified, independent insurance broker who can help you determine if an additional policy aligns with your long-term financial goals and risk management strategy. If your primary intent is to secure a specific amount of future protection, focus on identifying a term length that aligns with your biggest financial milestones, such as the final payment date of your mortgage or your children’s graduation from college.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
