Why Full Coverage Auto Insurance in Queens NY Is Rarely Worth It

For many drivers in Queens, New York, purchasing full coverage auto insurance results in paying hundreds of dollars each month for protection that mathematically exceeds the total market value of their vehicle, a financial mismatch driven by hyper-local risk indexing, dense traffic patterns, and the steep depreciation of aging commuter cars.
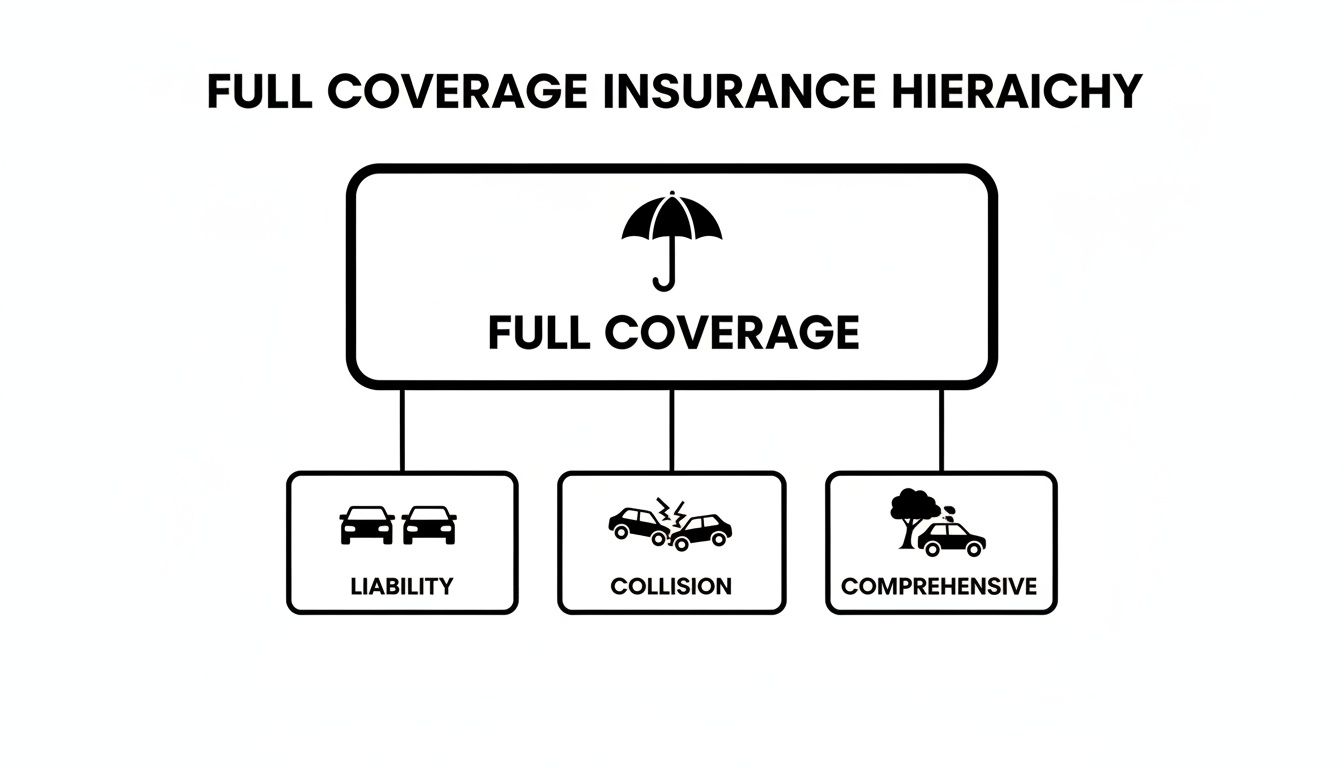
Navigating the landscape of New York auto insurance requires a careful balancing act between legal mandates, personal financial exposure, and the day-to-day realities of driving in one of the most densely populated urban areas in the United States. While the phrase "full coverage" implies absolute protection from financial loss on the road, it is not a specific policy type sold by insurers. Instead, it is a colloquial term that describes a combination of mandatory state-minimum liability insurance paired with physical damage coverages: comprehensive and collision.
For motorists operating vehicles throughout Astoria, Flushing, Jamaica, and the surrounding neighborhoods of Queens, evaluating whether these optional physical damage protections are actually worth the investment is a crucial financial decision. In many cases, the high premiums demanded by insurance carriers in this specific borough outpace the financial benefits these policies provide, making full coverage a questionable choice for a vast segment of the local driving population.
Understanding the Components of "Full Coverage" in New York
To determine why comprehensive and collision policies often fail to deliver value in Queens, it is necessary to examine what the term actually encompasses under New York State insurance law.
In New York, every registered vehicle must carry minimum liability insurance. This statutory requirement includes:
- Bodily Injury Liability: Coverage for injuries or death caused to other people in an accident you cause, set at mandatory minimum limits of $25,000 for injury to one person and $50,000 for two or more people, escalating to $50,000 and $100,000 respectively in the event of death.
- Property Damage Liability: Coverage for damage you cause to someone else’s property or vehicle, with a state minimum of $10,000 per accident.
- Personal Injury Protection (PIP): New York is a no-fault state, meaning your own insurance pays for your medical expenses and lost wages up to $50,000 regardless of who caused the crash.
- Uninsured Motorist Coverage (UM): Protection against drivers who carry no insurance at all, matching your bodily injury limits.
When people refer to "full coverage," they are adding Collision coverage (which pays to repair or replace your vehicle if you hit another car or object, such as a guardrail or pothole) and Comprehensive coverage (which pays for theft, vandalism, fire, or damage from falling objects like tree branches during a severe storm).
While liability and PIP protect you from third-party lawsuits and basic medical costs, collision and comprehensive protect your own asset. However, in a borough like Queens, the pricing mechanism for these two physical damage components makes them disproportionately expensive relative to the cars they protect.
The Queens Factor: Why Premiums Spike in the Borough
Insurance pricing is fundamentally a game of statistical risk assessment. Actuaries analyze historical claims data, traffic density, accident frequency, theft rates, and uninsured motorist percentages to price policies by ZIP code. Queens consistently ranks among the more expensive areas in New York State for car insurance, driven by distinct urban pressures.
The borough's infrastructure creates a high-frequency environment for minor fender-benders and parking lot scrapes. Crowded thoroughfares like Queens Boulevard, the Long Island Expressway, the Grand Central Parkway, and narrow residential streets in neighborhoods like Jackson Heights or Ridgewood see constant congestion. While these collisions rarely result in catastrophic high-speed damage, they generate a high volume of costly claims for insurers repairing bumpers, quarter panels, and side-view mirrors.
Furthermore, repair costs in the New York metropolitan area are among the highest in the nation. Local body shops face elevated commercial rents, high labor rates, and supply chain delays, all of which inflate the cost of parts and professional labor. Modern vehicles equipped with advanced driver-assistance systems (ADAS)—such as bumper-mounted radar sensors, calibration cameras, and aluminum body panels—cost exponentially more to fix after a minor collision.
Insurers pass these projected repair expenses directly to policyholders through increased comprehensive and collision premiums. Consequently, a driver living in Queens absorbs a localized geographic penalty that artificially inflates the cost of physical damage coverage far beyond what drivers in suburban or rural counties experience.
The Mathematics of Diminishing Returns: The 10% Rule
The single most important financial calculation when deciding whether to carry full coverage is comparing the cost of the annual premium against the actual cash value (ACV) of the vehicle. A widely accepted guideline in personal finance is the 10% rule: if your annual cost for comprehensive and collision coverage exceeds 10% of your car's total market value, maintaining that coverage is generally a bad financial bet.
Consider a practical example typical of many Queens commuters. Imagine a driver owns a 2014 sedan with an estimated market value of $6,000. Because the car is fully paid off, there is no lienholder requiring physical damage protection.
When quoting a policy in a Queens ZIP code, the insurer might price comprehensive and collision coverage at $1,400 annually, layered on top of the mandatory liability and PIP baseline.
- Vehicle Market Value: $6,000
- Annual Cost of Comprehensive & Collision: $1,400
- Deductible: $500
Under this scenario, the owner is paying nearly 23% of the car's total value every single year just for the privilege of having physical damage insurance. If the driver goes three years without an accident, they will have paid $4,200 in premiums—more than half the car's worth—while still remaining subject to a $500 out-of-pocket deductible if a claim is filed.
Even worse, if the car is completely totaled in an accident, the insurance payout is not the original purchase price or the cost of a brand-new replacement; it is the actual cash value of the vehicle at the exact moment of the loss, minus the deductible. For a depreciating asset, that payout would be around $5,500 ($6,000 ACV minus $500 deductible) after years of heavy premium outlays.
| Vehicle Value Tier | Est. Annual Comp/Collision Cost in Queens | Exceeds 10% Rule? | Full Coverage Recommendation |
|---|---|---|---|
| Under $4,000 | $1,200 – $1,600 | Yes (30%+) | Drop immediately (rely on liability only) |
| $4,000 – $8,000 | $1,300 – $1,800 | Yes (15% - 25%) | Strongly reconsider; drop if self-insuring is viable |
| $8,000 – $15,000 | $1,500 – $2,200 | Borderline | Evaluate personal savings and risk tolerance |
| $15,000+ / Leased / Financed | $1,800 – $3,000+ | Varies | Required by lender; value often justifies cost |
When Full Coverage Is Legally and Practically Necessary
Despite the high cost in Queens, dropping physical damage coverage is not an option for every driver. There are distinct legal, financial, and practical scenarios where maintaining comprehensive and collision insurance is mandatory or logically sound.
1. Auto Loans and Leases
If you financed your vehicle through a bank, credit union, or dealership, or if you are currently leasing the car, your financing agreement will explicitly contractually obligate you to maintain full coverage. Lenders and lessors have a vested financial interest in protecting their collateral until the loan is completely satisfied. If you drop collision or comprehensive coverage while holding a loan, the lender has the right to purchase "force-placed insurance" on your behalf—which is typically far more expensive and provides fewer protections than a policy you shop for independently.
2. High-Value or Brand-New Vehicles
For newer cars, electric vehicles, or luxury models with market values exceeding $20,000 to $30,000, the mathematics of the 10% rule often tilt in favor of full coverage. If a major accident results in $12,000 worth of frame and sensor repairs on a late-model crossover, paying out-of-pocket would cause catastrophic personal financial distress. In these instances, the high cost of Queens insurance premiums is offset by the immense financial exposure of replacing or repairing an expensive modern asset.
3. Personal Financial Vulnerability
Insurance is ultimately a tool for transferring risk that you cannot afford to absorb yourself. If you do not have an emergency savings fund capable of replacing your vehicle tomorrow in the event it is totaled or stolen, carrying full coverage acts as a vital safety net. Paying a high monthly premium is a predictable, budgetable expense; suddenly needing $10,000 to buy a replacement commuter car after a hit-and-run on the Van Wyck Expressway is a financial shock that many households cannot absorb.
Evaluating Risk vs. Reward: The Hidden Costs of Filing Claims
Many drivers assume that paying for full coverage means they can freely file claims whenever minor damage occurs. However, in the high-rate environment of New York State, filing minor collision or comprehensive claims often triggers severe financial repercussions down the line.
When you file a claim for a minor parking lot dent or a cracked windshield, insurers frequently impose a surcharge upon policy renewal, or they may strip away your "accident forgiveness" status. In New York, insurance carriers review your driving and claims history over a multi-year lookback period. A single at-fault collision claim can cause your annual premiums to skyrocket by 20% to 50% for three consecutive years.
When factoring in the cost of your deductible ($500 or $1,000) plus the cumulative multi-year rate hikes resulting from an at-fault claim, minor repairs often cost significantly more through your insurance company than paying an independent auto body shop directly out of pocket. Comprehensive claims—such as vandalism, theft of vehicle parts, or windshield damage from highway debris—are sometimes treated more leniently by insurers, but multiple claims of any kind signal higher risk to underwriters and lead to non-renewal warnings.
Actionable Steps to Optimize Your Queens Auto Insurance Policy
If you live in Queens and suspect you are overpaying for unnecessary physical damage coverage, you can take a systematic approach to right-size your policy without leaving yourself legally or financially exposed.
- Determine Your Car’s True Market Value: Check valuation platforms like Kelley Blue Book (KBB) or Edmunds to find the current private party and trade-in value of your specific vehicle year, make, model, and mileage in the New York market.
- Calculate Your Physical Damage Cost: Review your current declarations page. Separate the cost of collision and comprehensive coverage from your liability, PIP, and uninsured motorist premiums.
- Apply the 10% Threshold: If your annual physical damage premium exceeds 10% of the car's current market value, and you own the vehicle outright, evaluate whether you can comfortably self-insure the loss of the car.
- Adjust Deductibles as a Compromise: If you decide to keep full coverage because your car's value sits in a borderline tier, raise your deductible from $500 to $1,000 or $2,000. Higher deductibles substantially lower your monthly or semi-annual premium while still protecting you against catastrophic total losses.
- Shop Your Policy Annually: Loyalty rarely pays in the New York insurance market. Rates fluctuate as regional risk models are updated by state regulators. Compare quotes from multiple independent brokers across different carriers every year to ensure you are capturing competitive rates tailored to your exact Queens neighborhood.
Disclaimer: Insurance regulations, liability limits, and premium calculations vary based on individual driver history, vehicle specifications, and underwriting guidelines. This article provides general financial analysis and should not be construed as formal legal or licensed insurance advice. Consult a licensed New York insurance broker to evaluate your specific coverage needs.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
