Understanding Household Costs: Average Electric Bills and Life Insurance Premiums in 2026

In 2026, the average monthly electric bill in the United States is approximately $165, though this varies significantly by state and seasonal usage. Meanwhile, a standard 20-year term life insurance policy for a healthy 30-year-old costs roughly $30 to $45 per month. Both expenses are foundational to a stable household budget and require careful evaluation of regional rates, individual usage, and personal risk profiles.
The Landscape of Electricity Costs in 2026
Energy costs remain a primary concern for homeowners and renters alike. As we navigate 2026, the average electric bill is influenced by a combination of grid modernization efforts, the transition to renewable energy sources, and the increasing electrification of homes, including the widespread adoption of electric vehicle (EV) charging stations.
National Averages and Regional Disparity
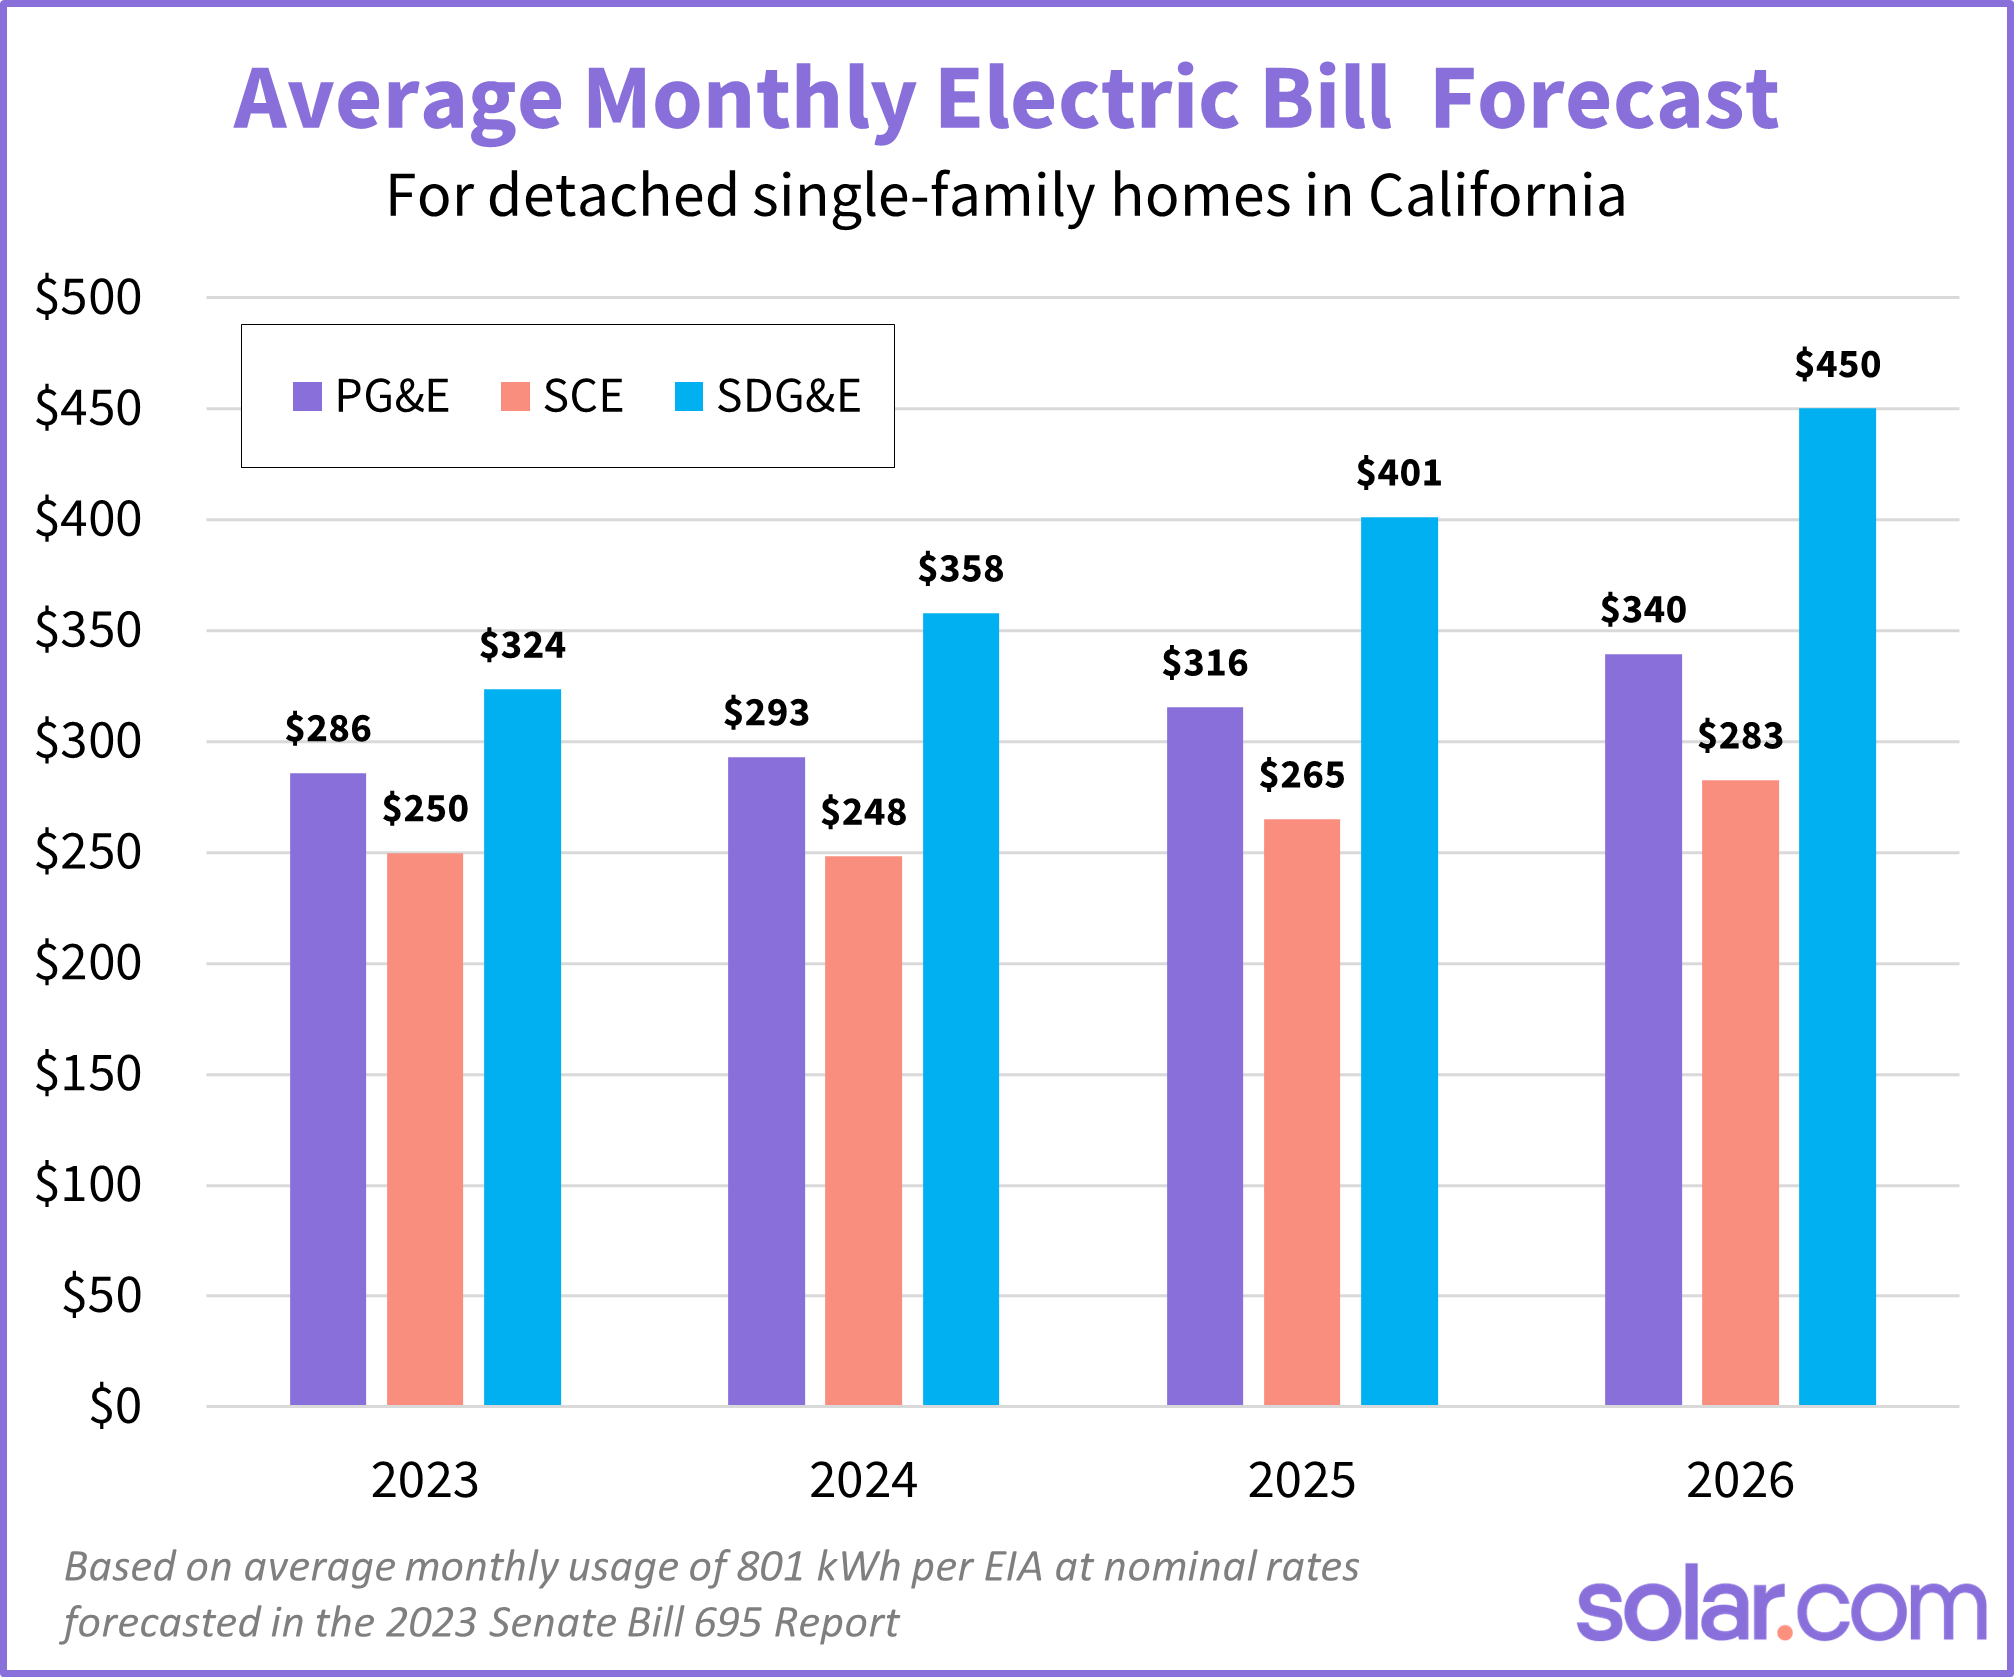
While the national average hovers around $165 per month, the "sticker price" of electricity is rarely uniform across the country. Electricity is priced per kilowatt-hour (kWh), and the rate you pay depends heavily on your local utility provider and state regulations.
In states like Hawaii or California, where energy production costs are higher and environmental regulations are more stringent, monthly bills often exceed $250. Conversely, residents in states with abundant hydroelectric power or lower cost of living, such as Washington or Utah, may see averages closer to $110.
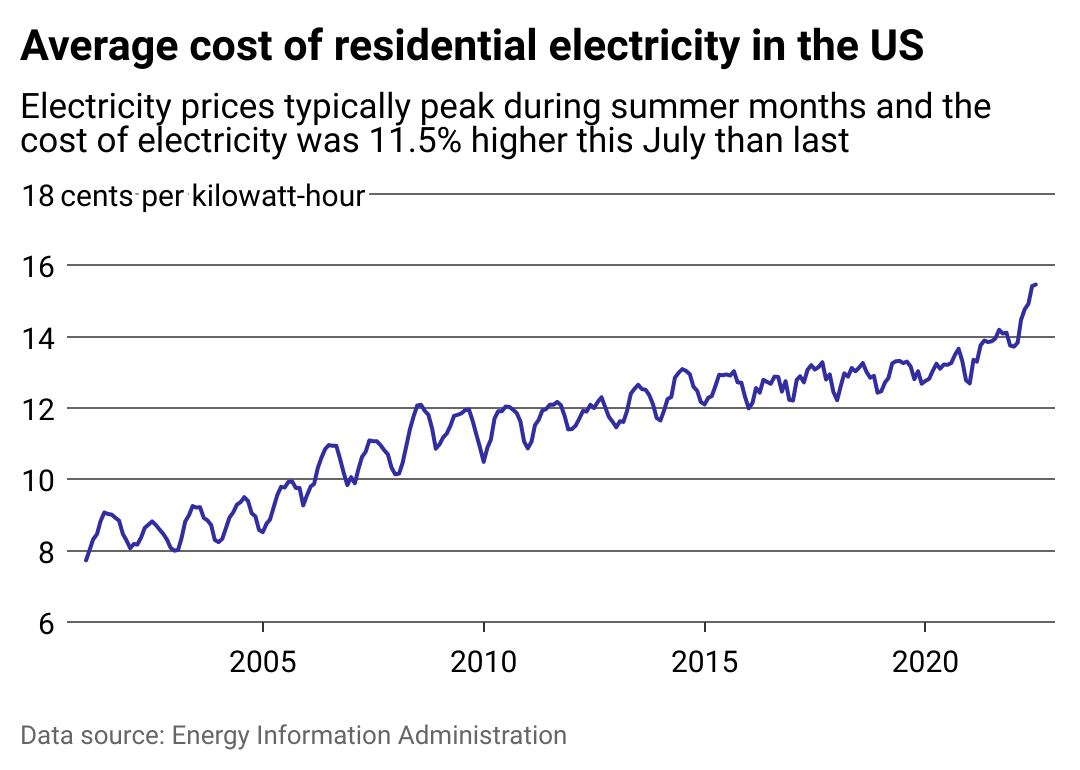
The average household consumption in 2026 remains near 900 kWh per month. However, the price per kWh has seen a steady increase over the last five years due to infrastructure updates. According to the U.S. Energy Information Administration (EIA), these updates are necessary to support a "smarter" grid capable of handling bidirectional energy flow from residential solar panels.
Factors Influencing Your Electric Bill
Several variables dictate whether your bill falls above or below the national median:
- Home Size and Age: Larger homes naturally require more energy for heating and cooling. Older homes, often lacking modern insulation or double-pane windows, suffer from "thermal leakage," forcing HVAC systems to work harder.
- Climate and Seasonality: Residents in the "Sun Belt" experience peak bills during the summer months due to air conditioning, while those in northern climates see spikes in the winter, especially if they utilize electric heat pumps.
- Appliance Efficiency: The transition to Energy Star-rated appliances has mitigated some cost increases. In 2026, smart home ecosystems that automatically dim lights or adjust thermostats during peak pricing hours have become essential tools for cost management.
- Electric Vehicles (EVs): Level 2 home charging stations can add 200–400 kWh to a monthly bill, depending on driving habits. Many utilities now offer "time-of-use" (TOU) rates, where electricity is cheaper overnight, specifically to accommodate EV owners.
Determining Life Insurance Costs in 2026
Life insurance is a critical component of financial security, providing a death benefit to beneficiaries in exchange for regular premium payments. Unlike a utility bill, which fluctuates based on consumption, life insurance premiums are generally "locked in" at the time of purchase based on the applicant's risk profile.
Term vs. Permanent Life Insurance
The type of policy you select is the most significant factor in determining your premium.
- Term Life Insurance: This is the most affordable option for most families. It provides coverage for a specific period (e.g., 10, 20, or 30 years). In 2026, a 20-year term policy with a $500,000 death benefit for a healthy 35-year-old averages between $35 and $55 per month.
- Whole Life Insurance: As a form of permanent life insurance, whole life covers you for your entire life and includes a cash value component. Because of these features, premiums are significantly higher—often 10 to 15 times more expensive than term insurance for the same death benefit. A $500,000 whole life policy could easily cost $500 to $700 per month.
The Role of Underwriting and Personal Risk
Insurance companies use a process called underwriting to determine your premium. In 2026, underwriting has become more sophisticated, often incorporating data from wearable fitness devices for those who opt into "wellness-based" pricing models.
- Age and Gender: Generally, the younger you are, the lower your premium. Statistically, women have longer life expectancies than men, which often results in slightly lower premiums for female applicants.
- Health Status: Chronic conditions such as diabetes, heart disease, or high blood pressure will increase premiums. Tobacco use remains the single largest controllable factor; smokers can expect to pay 200% to 300% more than non-smokers.
- Occupation and Hobbies: If your job involves high-risk activities (e.g., structural steelwork) or if you participate in extreme sports like skydiving, insurers may apply a "flat extra" fee to your premium.
The National Association of Insurance Commissioners (NAIC) provides resources for consumers to verify the licensing of insurance companies, which is a vital step before committing to a long-term policy.
Comparative Cost Analysis: Utilities vs. Insurance
To better understand how these costs fit into a monthly budget, the following table illustrates estimated expenses based on different demographics and living situations in 2026.
| Demographic Profile | Est. Electric Bill (Monthly) | 20-Year Term Life ($500k) | Total Monthly Allocation |
|---|---|---|---|
| Single Renter (Apt), age 25 | $85 | $22 | $107 |
| Young Family (Small Home), age 32 | $160 | $40 | $200 |
| Established Family (Large Home), age 45 | $240 | $85 | $325 |
| Retiree (Condo), age 65 | $120 | $210 (10-yr term) | $330 |
| High-Usage Household (EV + Large Home) | $310 | $60 (age 35) | $370 |
Note: Figures are estimates for 2026 based on national averages and standard healthy-tier underwriting.
Strategies for Managing and Reducing Costs
Managing household expenses requires a dual approach: reducing consumption for variable costs (utilities) and optimizing policy selection for fixed costs (insurance).
Optimizing Electricity Consumption
To lower your electric bill, focus on both behavior and technology. In 2026, many utilities offer "Demand Response" programs. By allowing the utility to slightly adjust your smart thermostat during periods of extreme grid stress, you can earn monthly credits on your bill.
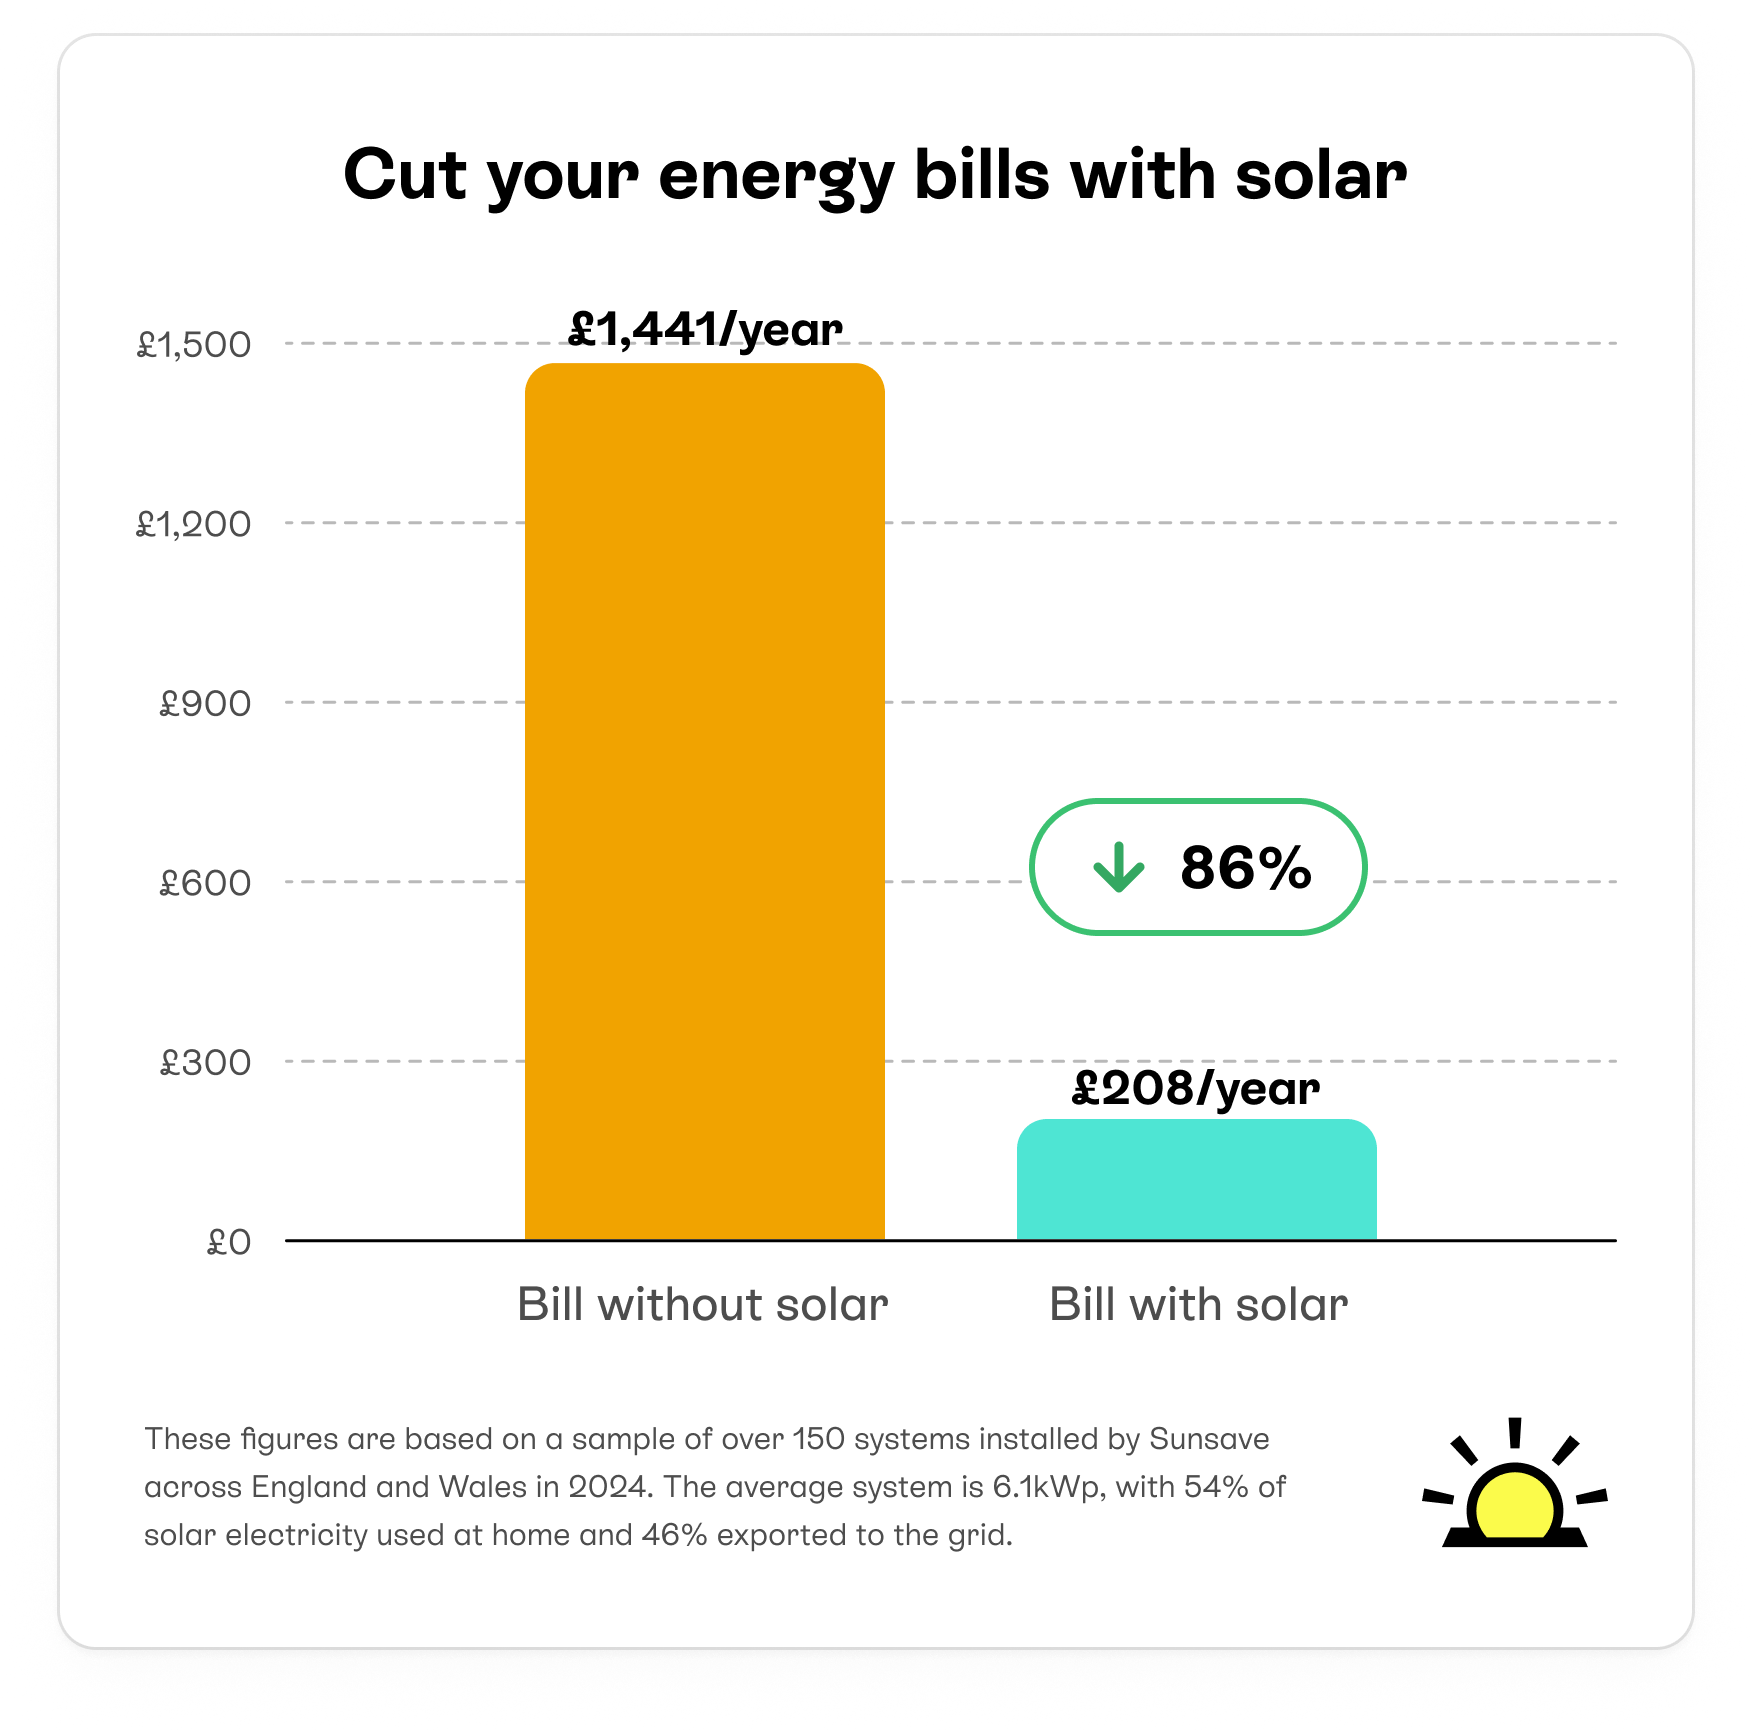
Additionally, performing a DIY home energy audit can reveal simple fixes. Sealing gaps around doors and windows with weatherstripping can reduce heating and cooling costs by up to 15%. For those in high-rate states, residential solar storage systems have become more financially viable due to federal tax credits, allowing homeowners to store energy during the day and use it during expensive peak evening hours.
Securing the Best Life Insurance Rates
The most effective way to save on life insurance is to buy it as early as possible. Since premiums are based on your age at the time of application, "locking in" a rate in your 20s or 30s can save tens of thousands of dollars over the life of the policy.
Furthermore, consider the "laddering" strategy. Instead of one large $1 million policy, you might buy one $500,000 30-year policy to cover a mortgage and a $500,000 20-year policy to cover children’s education. This ensures you are not over-insured (and over-paying) in your later years when your financial obligations decrease.
Frequently Asked Questions
Why is my electric bill so much higher than the average?
Your bill may exceed the average due to "phantom loads"—electronics that consume power even when turned off—or inefficient HVAC systems. In 2026, the average cost per kWh is approximately 18-20 cents; if your local rate is higher, or if you are charging an EV daily, your bill will naturally sit above the national mean.
Does life insurance get more expensive as I get older?
Yes, premiums increase with age because the statistical risk of death rises. For example, a policy that costs $30 a month at age 30 might cost $90 a month if purchased for the first time at age 50. This is why financial advisors typically recommend securing coverage while you are young and healthy.
Can I lower my life insurance premium after the policy has started?
You cannot typically lower the premium on an existing term policy. However, if you have significantly improved your health (e.g., lost a substantial amount of weight or quit smoking for over two years), you can ask your insurer for a "re-rating" or apply for a new policy at a lower rate and then cancel the old one.
Are electric bills expected to keep rising through 2030?
Market analysts suggest that while the cost of renewable energy production is falling, the cost of distributing that energy (grid maintenance) is rising. Therefore, consumers should expect modest annual increases of 2% to 4% in their total bill through the end of the decade.
What is the difference between a "Death Benefit" and "Cash Value"?
The death benefit is the amount paid to your beneficiaries when you pass away. The cash value is a tax-deferred savings component found only in permanent policies (like whole life). It grows over time and can be borrowed against, but it is one of the primary reasons whole life insurance is more expensive than term life.
Practical Recommendations
For the best financial outcome in 2026, start by analyzing your last 12 months of electric bills to identify seasonal peaks. Contact your utility provider to see if you qualify for a "budget billing" plan, which levels out your payments across the year to avoid summer or winter spikes.
Regarding life insurance, perform a "needs analysis" before shopping. Calculate your total debt (mortgage, car loans, credit cards) and add the equivalent of 10 times your annual income. Once you have this number, compare quotes from at least three different highly-rated carriers. Prioritize term insurance unless you have a specific need for the permanent coverage and estate planning features of a whole life policy. Taking these steps today ensures that your 2026 budget remains resilient against both predictable and unpredictable expenses.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
