
It is technically never too late to buy whole life insurance as long as you meet a carrier’s age and health requirements, which typically extend to age 85. However, it becomes financially impractical for many after age 70 due to high premiums and diminishing returns on cash value accumulation.
Whole life insurance is a form of permanent life insurance that provides a guaranteed death benefit, fixed premiums, and a cash value component that grows over time. Because the policy is designed to cover the insured for their entire life, the insurance company assumes a 100% chance of eventual payout. As you age, the statistical proximity to that payout increases, which creates a sharp rise in the cost of coverage. In 2026, while modern underwriting has become more efficient, the fundamental math of mortality remains the primary factor in determining whether buying a policy late in life is a sound financial move.
Understanding the Maximum Entry Ages for Whole Life Insurance
Most major life insurance carriers set a hard "maximum issue age" for their whole life products. For the majority of top-tier mutual insurers and commercial carriers, this limit is usually 85 years old. Some niche providers may offer coverage up to age 90, but these policies are rare and often carry significant restrictions or prohibitively high costs.
The reason for these age caps is rooted in actuarial science. Life insurance is a risk-sharing pool. By age 85, the statistical life expectancy for a male in the United States is approximately 5 to 7 additional years, and for a female, approximately 7 to 9 years. For an insurer to issue a policy that might only collect five years of premiums before paying out a $100,000 death benefit, the annual premium would have to be extraordinarily high—often nearing the value of the death benefit itself within a short period.
If you are seeking coverage in your late 70s or early 80s, you will likely encounter "Simplified Issue" or "Guaranteed Issue" products rather than traditional fully underwritten whole life. Traditional policies require a medical exam and a deep dive into your medical history, which many seniors may not pass with the "Preferred" or "Standard" ratings necessary to make the premiums affordable.
The Impact of Health and Underwriting in Later Life
As we move through 2026, the life insurance industry has increasingly shifted toward accelerated underwriting. This process uses big data, prescription drug histories, and motor vehicle records to assess risk without always requiring a physical medical exam. However, for older applicants—specifically those over age 60—carriers still frequently request a "paramedical" exam.
The Role of Underwriting Classes
Your health determines your "rating," which dictates your premium. In your 40s, you might easily qualify for "Preferred Plus" rates. By your 70s, even if you are in relatively good health for your age, you might be rated as "Standard" or "Table Rated" (a higher-risk category). Common age-related conditions that complicate whole life applications include:
- Cardiovascular Issues: History of stroke, heart attack, or high blood pressure managed by multiple medications.
- Cognitive Health: Early-stage dementia or Alzheimer’s diagnoses are almost always an automatic decline for traditional whole life.
- Diabetes: Type 2 diabetes is manageable for underwriting, but the age of onset and the presence of complications (like neuropathy) heavily influence the price.
Guaranteed Issue: The Last Resort
If you have significant health issues and are over age 50, you may find that traditional whole life is unavailable. In this case, "Guaranteed Issue" life insurance becomes the only option. These policies do not require a medical exam or health questions. However, they typically have low coverage limits (usually $5,000 to $25,000) and feature a graded death benefit. This means that if you pass away from natural causes within the first two or three years of the policy, your beneficiaries only receive a refund of your premiums plus a small amount of interest, rather than the full face value.

Cost Analysis: The Financial Turning Point
The primary reason people ask if it is "too late" is the cost. Life insurance premiums are calculated based on the net single premium required to fund the death benefit, spread out over your remaining years.
Consider the difference in annual premiums for a $250,000 whole life policy (estimated for 2026):
- Applicant Age 35: ~$3,500 per year.
- Applicant Age 55: ~$8,200 per year.
- Applicant Age 75: ~$22,000 per year.
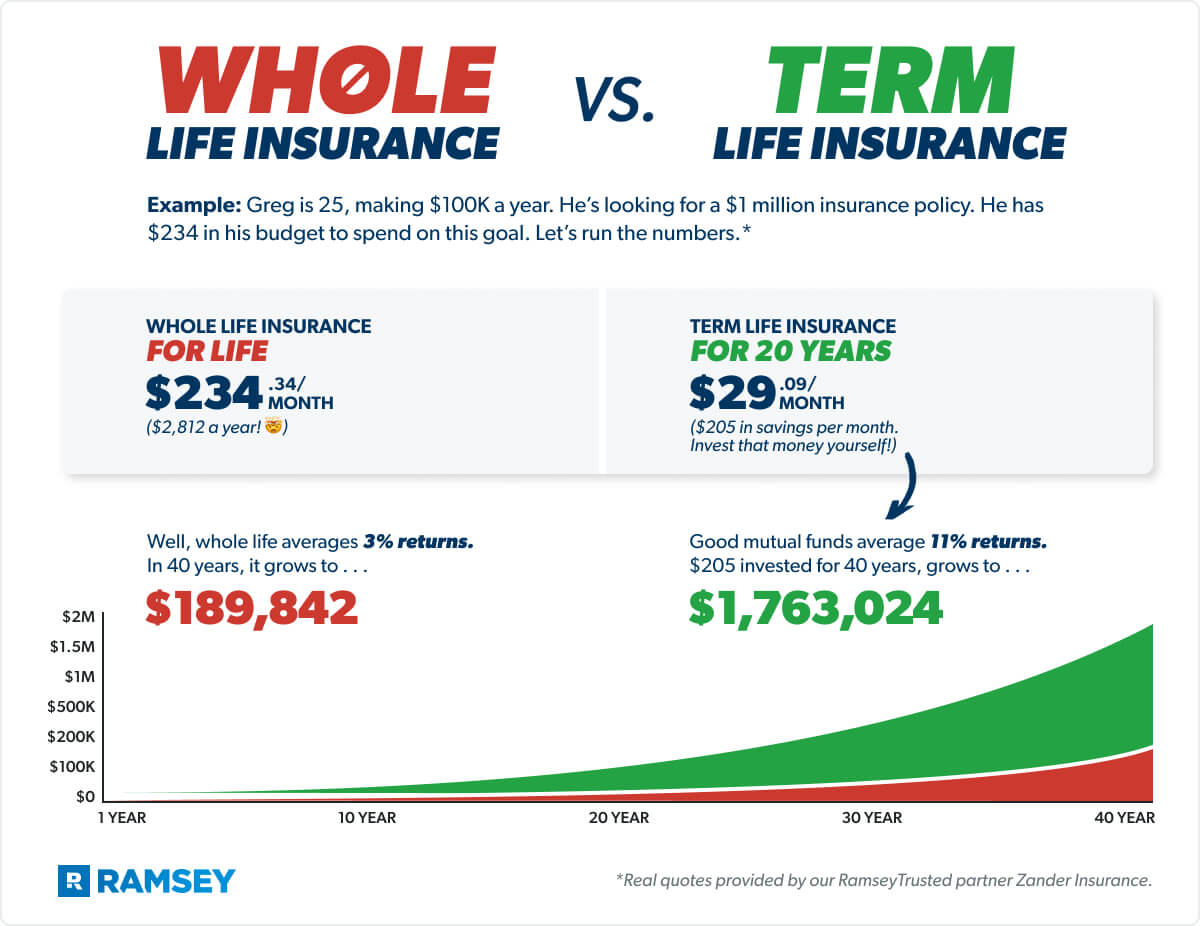
At age 75, the applicant is paying nearly 9% of the death benefit every year in premiums. If they live for 11 years, they will have paid more into the policy than the death benefit is worth. This "break-even point" is the most critical metric for anyone buying insurance late in life. If your goal is to provide a windfall for heirs, the math often suggests that investing those premium dollars into a brokerage account or a high-yield savings vehicle might yield a better result, provided you have a reasonable life expectancy.
Why People Buy Whole Life Insurance After Age 60
Despite the high costs, there are several specific financial strategies where buying whole life insurance late in life is a deliberate and effective choice.
1. Estate Tax Liquidity
For high-net-worth individuals, the federal estate tax (and various state inheritance taxes) can be a significant burden. In 2026, the estate tax exemption levels remain a focal point of tax planning. If an estate is comprised of illiquid assets—such as real estate, a family business, or art—the heirs might be forced to sell those assets to pay the tax bill. A whole life policy provides immediate cash (liquidity) to pay taxes, ensuring the estate remains intact for the heirs.
2. Equalizing Inheritances
If a parent intends to leave a family business to one child who works in the company, but wants to leave an equal value to another child who does not, they may use a whole life policy. The death benefit acts as the "equalizer," providing the second child with a cash inheritance equivalent to the value of the business.
3. Final Expense Coverage
Often called "Burial Insurance," these are small whole life policies designed specifically for seniors. The goal is not wealth transfer, but simply ensuring that funeral costs, which can exceed $12,000 in 2026, do not become a burden on children or a surviving spouse.
4. Pension Maximization
Retirees with a "Single Life" pension option often receive a higher monthly payout than those with a "Joint and Survivor" option. A retiree might choose the higher Single Life payout and use a portion of that extra income to fund a whole life policy. This ensures that if they die first, the surviving spouse receives a tax-free death benefit to replace the lost pension income.
Alternatives to Traditional Whole Life Insurance
If you find that whole life is too expensive or you cannot qualify, several other insurance structures may meet your needs more efficiently.
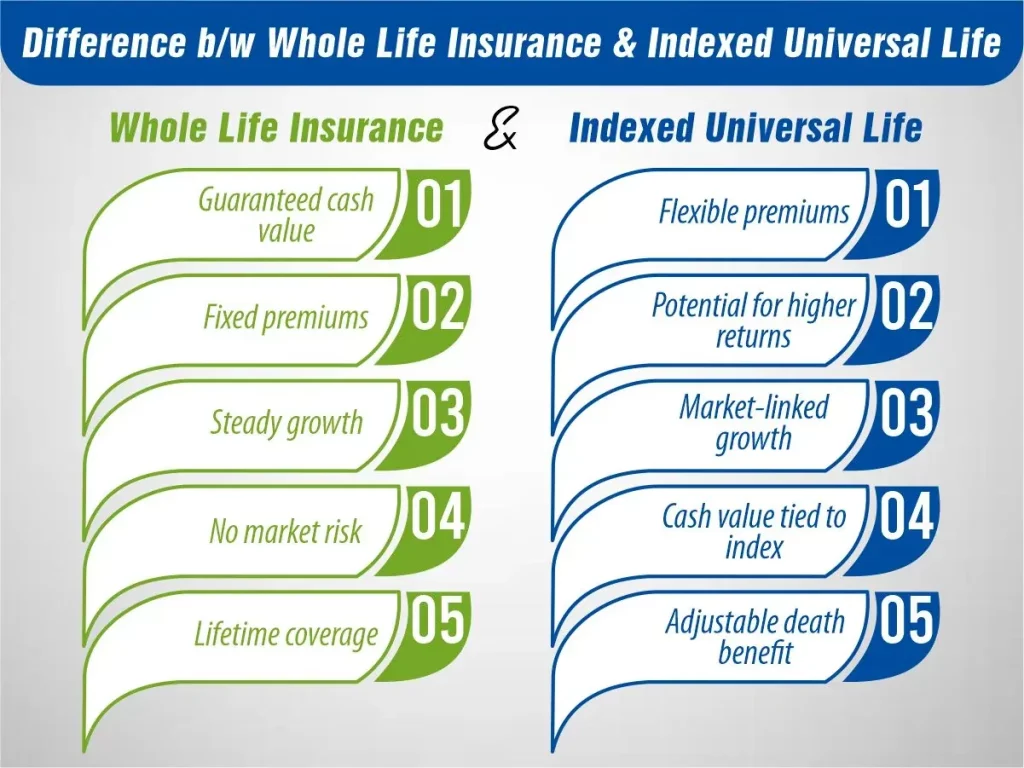
| Feature | Whole Life Insurance | Guaranteed Universal Life (GUL) | Final Expense Insurance |
|---|---|---|---|
| Max Issue Age | Typically 85 | Typically 80 | Typically 85 |
| Cash Value | Yes, guaranteed growth | Little to none | Minimal |
| Premiums | Fixed and very high | Fixed and moderate | Fixed and moderate |
| Death Benefit | Guaranteed for life | Guaranteed to a specific age (e.g., 105) | Guaranteed for life |
| Best For | Estate planning/Cash value | Lifetime protection at lower cost | Small funeral costs |
Guaranteed Universal Life (GUL)
GUL is often referred to as a "Term to age 100" or "Term to age 121" policy. It functions like whole life in that the premium is fixed and the coverage won't expire as long as you pay, but it strips away the cash value accumulation component. This makes GUL significantly cheaper than whole life—often 30% to 50% less expensive—while still providing a guaranteed death benefit for seniors.
Term Life Insurance
While term insurance is usually associated with younger families, many seniors buy 10-year term policies to cover a specific debt, such as a remaining mortgage or a business loan. If you are 65 and only need coverage until your mortgage is paid off at 75, term insurance is a fraction of the cost of whole life.
Key Considerations Before Applying in 2026
If you are considering a whole life purchase in the current year, evaluate these three factors to ensure you aren't making a costly mistake.
1. The Opportunity Cost of Premiums Calculate what would happen if you invested the premium amount instead of paying the insurance company. If you are 70 years old and the premium is $15,000 a year for a $150,000 policy, you must ask: "If I live to 85, would my $15,000 annual investment have grown to more than $150,000 in a diversified portfolio?" In many cases, the answer is yes, especially when considering that life insurance dividends (if the policy is participating) may not exceed the internal costs of the policy for the first decade.
2. The Purpose of the Death Benefit Is the insurance for a "must-pay" obligation (like estate taxes or a debt) or a "want-to-provide" gift? If it is a gift, you should weigh the tax-free nature of the death benefit against the flexibility of having that cash available for your own long-term care needs or emergencies while you are still alive.
3. Long-Term Care Riders One of the most valuable developments in 2026 life insurance products is the "hybrid" rider. Many whole life policies now allow you to access a portion of the death benefit while you are still alive to pay for long-term care or chronic illness expenses. For a senior, this turns the policy into a living benefit, which may justify the higher premium even if the death benefit math is marginal.
Frequently Asked Questions
Can I get whole life insurance at age 80?
Yes, you can still obtain whole life insurance at age 80, but your options will be limited. Most carriers that offer coverage at this age will limit the "face amount" (death benefit) and will require a thorough medical review. You may also be restricted to "Final Expense" policies which have lower maximum coverage limits.
Does the cash value grow if I buy a policy late in life?
The cash value does grow, but it grows slowly in the early years. Whole life policies have "front-loaded" costs, meaning a large portion of your early premiums goes toward commissions and the cost of insurance. If you buy a policy at age 75, it may take 12 to 15 years before the cash value equals the total premiums you have paid. If you do not expect to live past 90, the cash value component may never become a meaningful asset for you.
Is a medical exam always required for seniors?
Not necessarily. Many "Simplified Issue" policies for seniors rely on health questionnaires and database checks rather than blood draws or physical exams. However, if you are looking for a large policy (over $100,000), a medical exam is standard practice to ensure you do not have an undisclosed terminal illness or high-risk condition.
What is the average cost of burial insurance for a 70-year-old?
In 2026, a $10,000 burial insurance policy for a healthy 70-year-old typically costs between $60 and $90 per month, depending on gender and tobacco use. Prices increase significantly if you have history of heart disease, diabetes, or respiratory issues.
Can I cancel my whole life policy if I can no longer afford the premiums?
Yes, you can surrender the policy. If the policy has accumulated cash value, you will receive the "Cash Surrender Value" minus any outstanding loans or fees. Alternatively, you may be able to use the existing cash value to convert the policy into a "Reduced Paid-Up" policy, which provides a smaller death benefit but requires no further premium payments.
Practical Recommendation
If you are over the age of 65 and considering whole life insurance, your first step should be a needs-based analysis. Determine the exact dollar amount needed for your specific goal (e.g., $15,000 for a funeral or $500,000 for estate taxes).
If your goal is simply to leave money to heirs and you are in good health, compare the whole life quote against a Guaranteed Universal Life (GUL) policy. For most seniors, the GUL provides the same lifetime guarantee at a much lower price point because it doesn't force you to pay for a cash value component that you likely won't live long enough to utilize.
Finally, always work with an independent broker who has access to multiple carriers. Insurance pricing for seniors varies wildly between companies; one carrier might "table rate" you for a common condition like sleep apnea, while another might offer "Standard" rates, saving you thousands of dollars in annual premiums.
Image Gallery
Select an image to open it in a new tab.




Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
