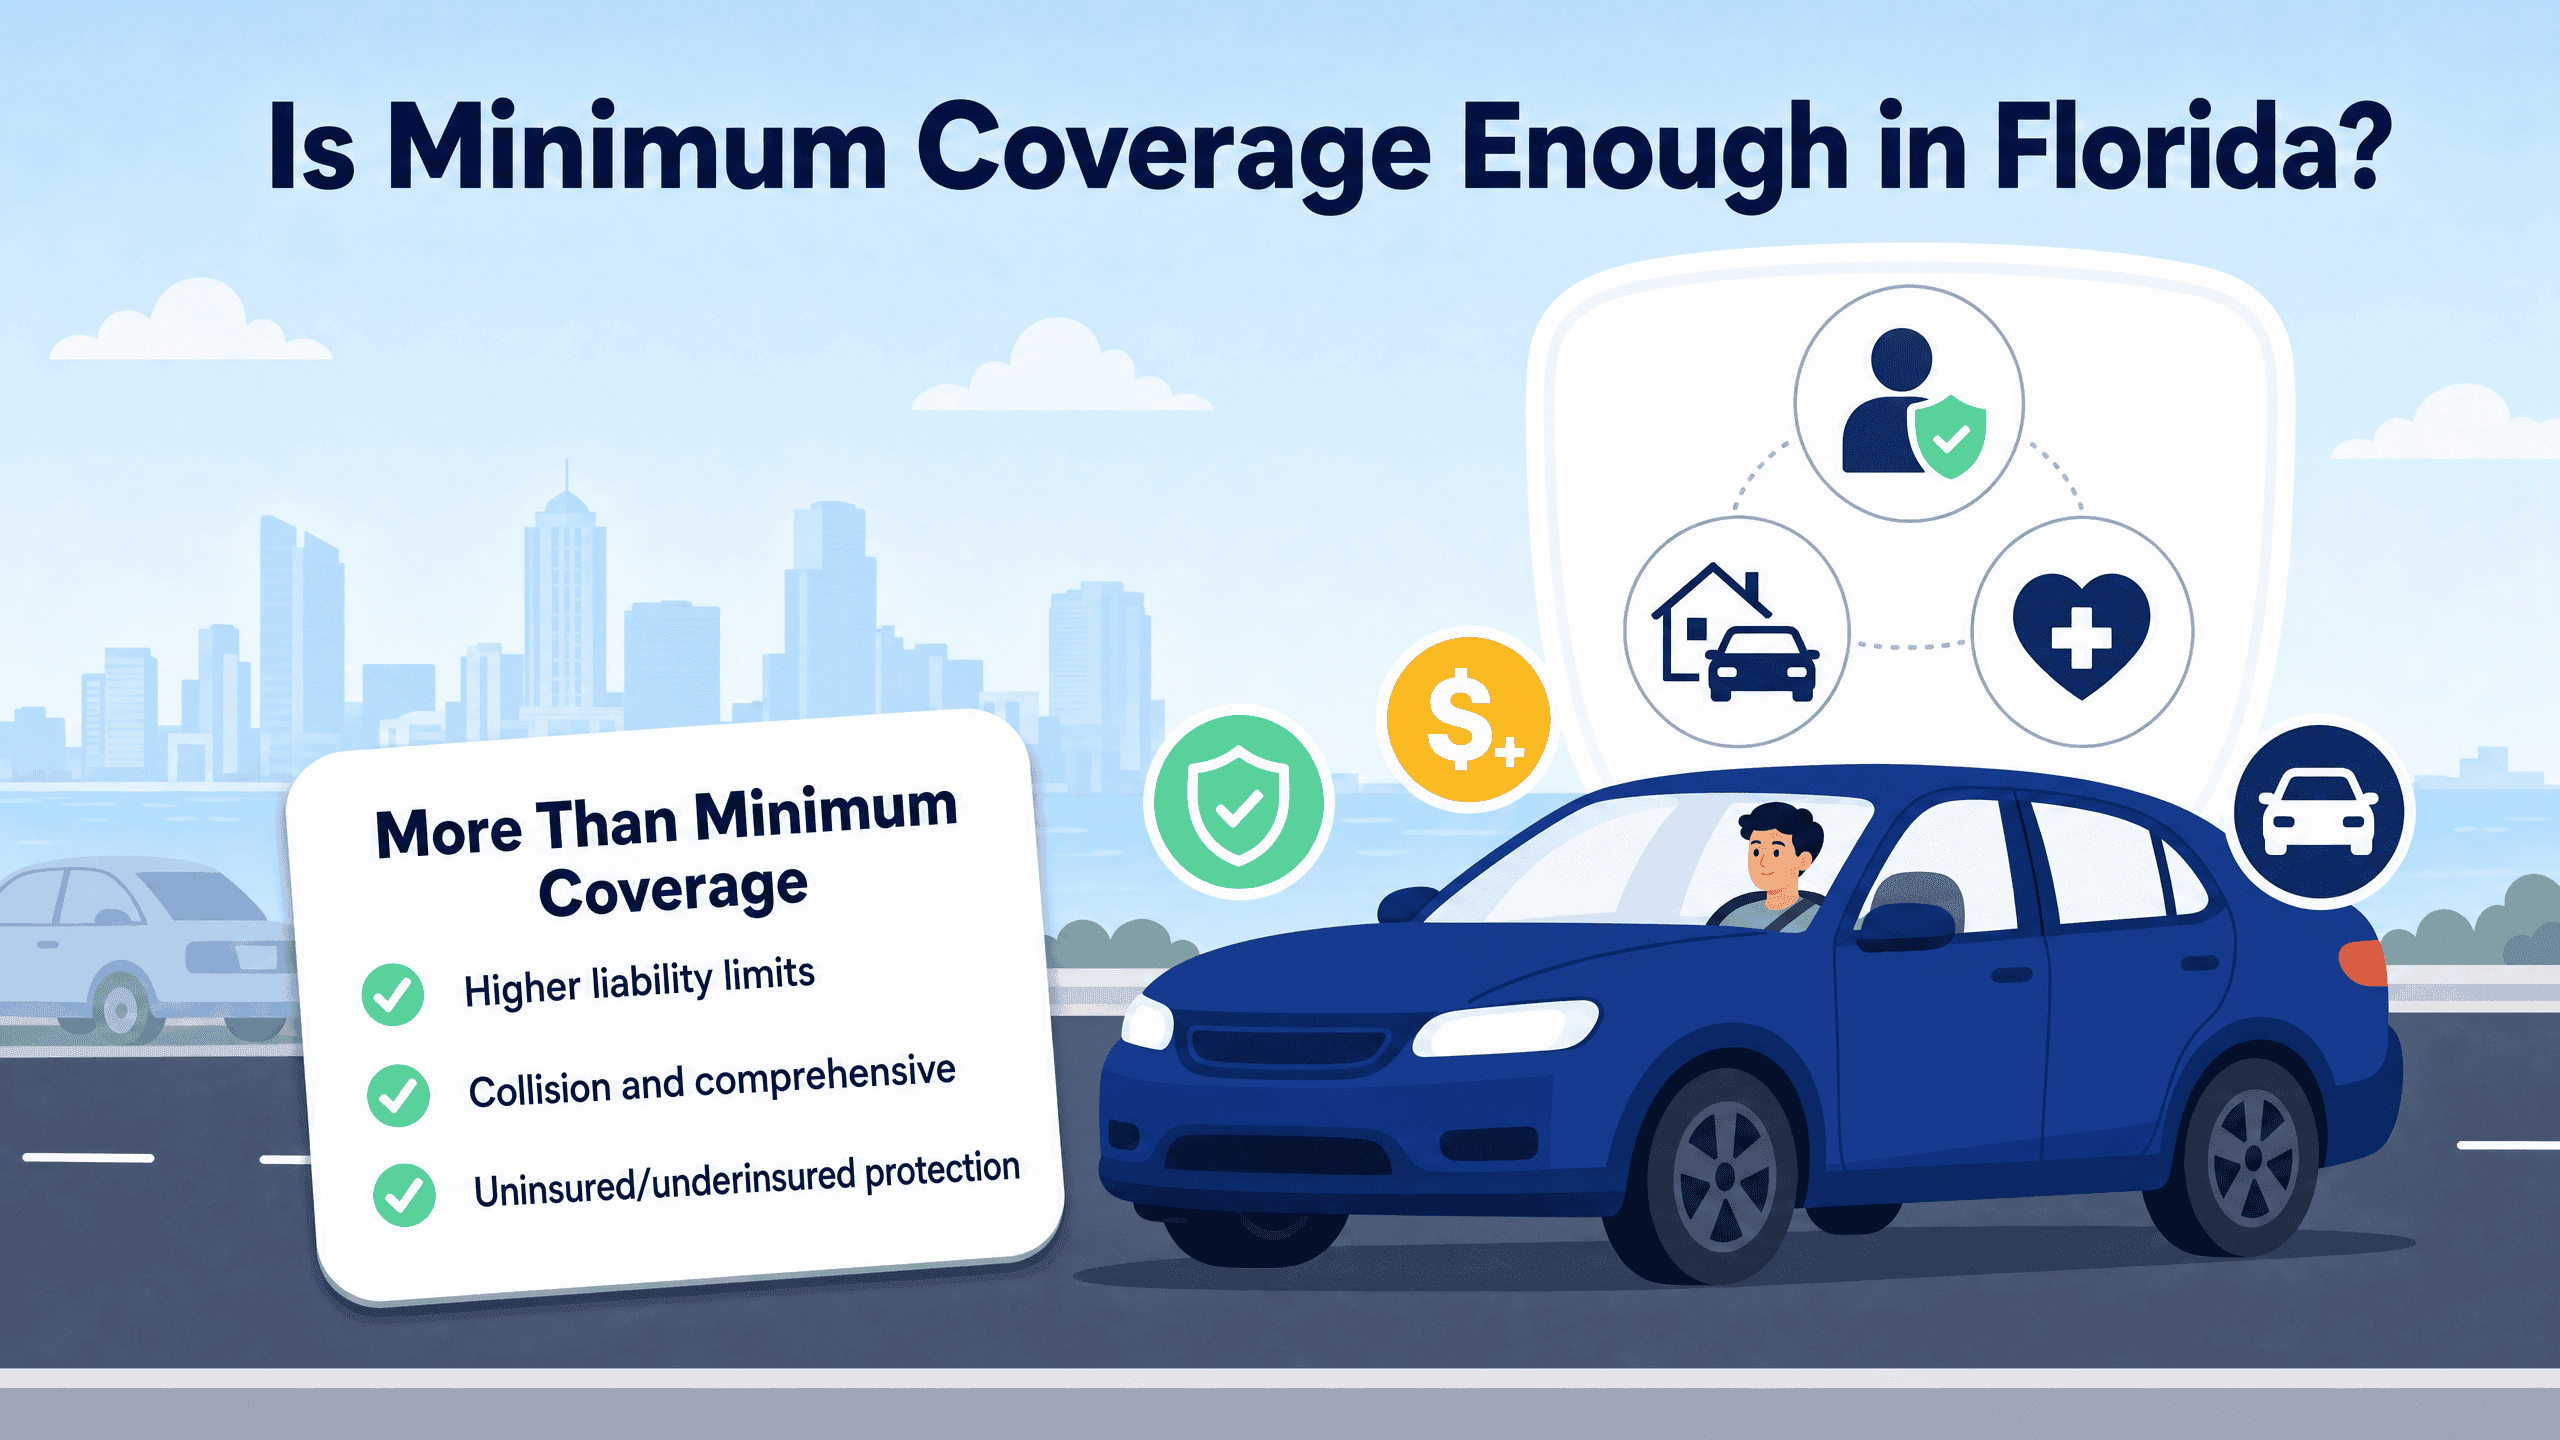
In Louisiana, carrying the minimum auto insurance coverage means you have met the basic legal requirement to operate a vehicle, specifically the 15/30/25 liability limits. While this protects you from state penalties and "No Pay, No Play" consequences, it offers no protection for your own vehicle and often leaves your personal assets vulnerable to lawsuits if damages exceed these low thresholds.
Every driver in the Pelican State is required by law to maintain a certain level of financial responsibility. As we navigate the economic landscape of 2026, understanding the nuances of these requirements is more critical than ever. Louisiana consistently ranks as one of the most expensive states for auto insurance, driven by a combination of high litigation rates, frequent severe weather events, and a significant population of uninsured motorists.
Choosing the minimum coverage is a decision many residents make to manage monthly costs, but the "savings" on premiums can lead to catastrophic financial losses after a single accident. This guide breaks down exactly what those numbers mean, the legal ramifications of your choice, and how Louisiana’s unique statutes affect your ability to recover damages.
Breaking Down the 15/30/25 Liability Limits
Louisiana law requires all drivers to carry liability insurance. This type of insurance does not pay for your repairs or your medical bills; rather, it pays for the injuries and property damage you cause to others in an at-fault accident. The state-mandated minimums are expressed as 15/30/25.
$15,000 for Bodily Injury per Person
This is the maximum amount your insurance provider will pay for medical expenses, lost wages, and pain and suffering for a single person injured in an accident where you are at fault. In 2026, with the rising costs of emergency room visits and specialized medical care, $15,000 can be exhausted within hours of a serious collision. If the injured party’s bills exceed this amount, they may pursue your personal assets—such as your savings or future wages—to cover the difference.
$30,000 for Bodily Injury per Accident
This is the total cap your insurance will pay for all injuries sustained by all people involved in a single accident. If you collide with a vehicle containing four passengers and all are injured, that $30,000 must be split among them. Once the $30,000 is spent, your insurance company has fulfilled its contractual obligation, leaving you personally liable for any remaining medical claims from any of the victims.
$25,000 for Property Damage per Accident
This limit covers the damage you cause to someone else’s property. Usually, this is their vehicle, but it also applies to structures like fences, utility poles, or buildings. Given that the average price of a new vehicle in 2026 often exceeds $50,000, a $25,000 limit is frequently insufficient. If you total a modern SUV or a luxury sedan, you could easily owe an additional $20,000 to $30,000 out of pocket.
The Louisiana "No Pay, No Play" Statute
One of the most significant aspects of Louisiana insurance law is the "No Pay, No Play" rule (La. R.S. 32:866). This law is designed to penalize uninsured motorists by limiting their ability to collect damages, even when an accident is not their fault.
Under this statute, if you are driving without the minimum 15/30/25 coverage and someone else hits you, you are barred from collecting the first $15,000 of bodily injury damages and the first $25,000 of property damage.
For example, if an insured driver rear-ends your uninsured vehicle and causes $20,000 in damage to your car, you would only be eligible to collect $0, because the first $25,000 is waived under the law. Similarly, if you suffer $15,000 in medical bills, you would receive nothing from the at-fault party's insurance. There are very few exceptions to this rule, such as accidents involving out-of-state drivers or drivers who are intoxicated.
Carrying the minimum coverage ensures you "play" by the rules, preserving your right to seek full compensation if another driver causes you harm.

What Minimum Coverage Does Not Include
A common misconception among drivers is that "minimum coverage" provides a safety net for their own needs. In reality, the state-mandated minimum is strictly liability-only. It leaves several critical gaps:
- Collision Coverage: This pays for damage to your own vehicle if you hit another car or an object. Without it, if you cause an accident, you are responsible for 100% of your vehicle's repair or replacement costs.
- Comprehensive Coverage: This covers non-collision events such as theft, vandalism, fire, or damage from Louisiana’s frequent floods and hurricanes.
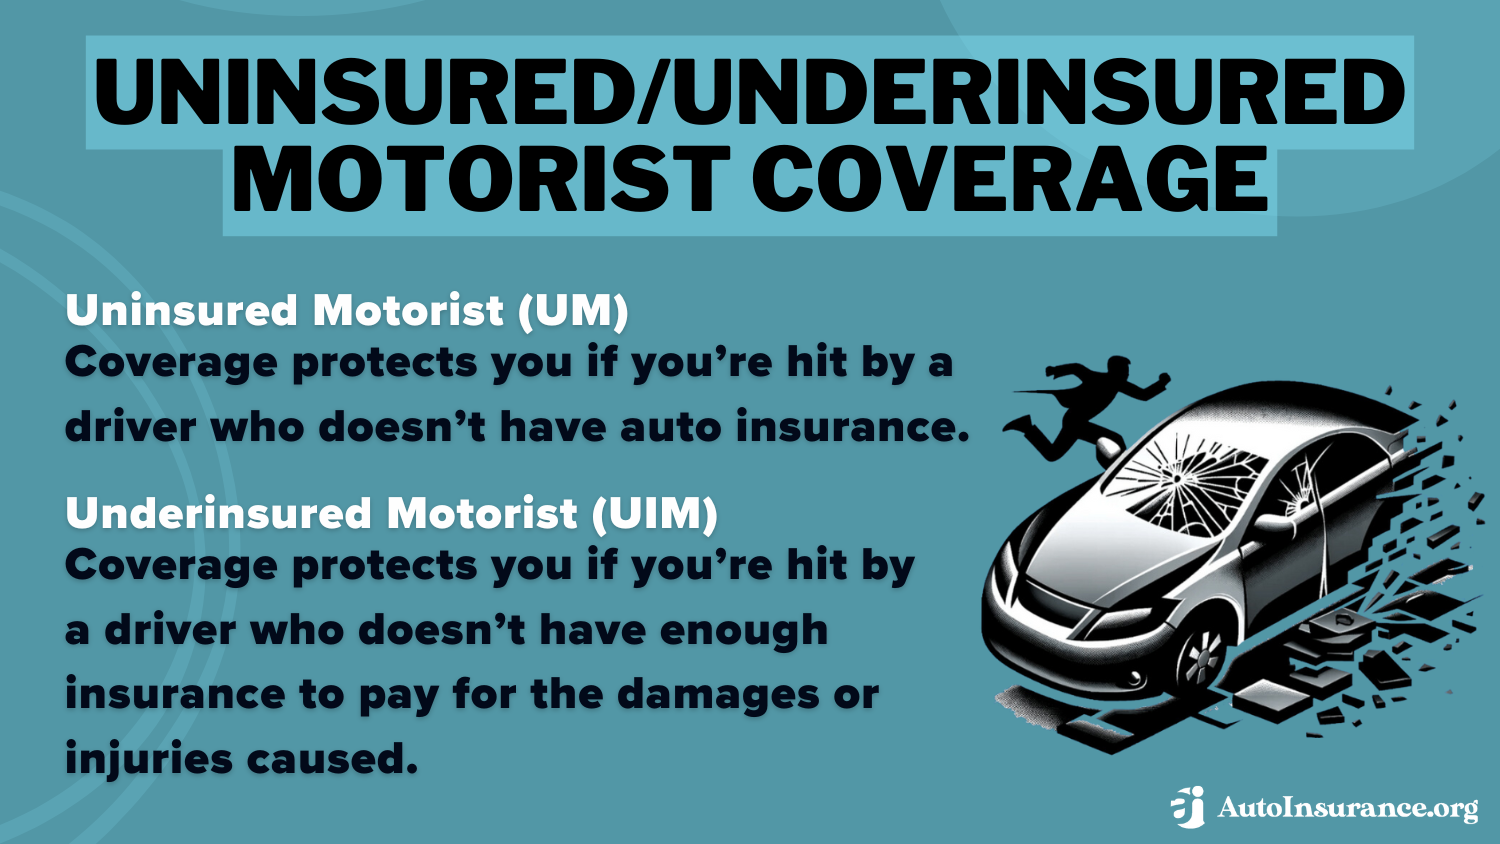
- Uninsured/Underinsured Motorist (UM/UIM): Louisiana has one of the highest rates of uninsured drivers in the country. UM/UIM coverage protects you if you are hit by someone who either has no insurance or whose limits (like the 15/30/25 minimum) are too low to cover your injuries.
- Medical Payments (MedPay): This covers medical or funeral expenses for you and your passengers, regardless of who was at fault.
In Louisiana, insurance companies are required to offer you UM/UIM coverage. If you decide you only want the minimum liability, you must specifically reject UM coverage in writing on a form provided by the Louisiana Department of Insurance.
Minimum vs. Recommended Coverage Comparison
To help visualize the difference between bare-minimum legal compliance and financial security, consider the following comparison based on 2026 market conditions.
| Coverage Type | Louisiana Minimum (15/30/25) | Recommended Standard | Why it Matters |
|---|---|---|---|
| Bodily Injury (Person) | $15,000 | $100,000 | Covers modern surgical and ER costs. |
| Bodily Injury (Accident) | $30,000 | $300,000 | Protects you when multiple people are hurt. |
| Property Damage | $25,000 | $100,000 | Covers the cost of totaling a new vehicle. |
| UM/UIM | Not Required | Matches Liability Limits | Essential in LA due to high uninsured rates. |
| Collision/Comp | Not Included | Actual Cash Value | Protects your own vehicle investment. |
| Deductible | N/A | $500 - $1,000 | Out-of-pocket cost before insurance kicks in. |
The Financial Risk of Minimum Limits in 2026
Carrying the minimum coverage in 2026 is a high-stakes gamble. The primary risk is asset seizure. If you are at fault in an accident that causes $100,000 in medical trauma (a common figure for a multi-day hospital stay) and you only have $15,000 in coverage, the victim's legal counsel will look for the remaining $85,000 elsewhere.
Louisiana allows for the garnishment of wages and the seizure of non-exempt property to satisfy legal judgments. If you own a home with equity or have a significant savings account, these are at risk. Even if you have few assets now, a judgment can follow you for years, affecting your ability to buy a home or secure credit in the future.
Furthermore, if you are financing or leasing a vehicle, your lender will not allow you to carry only the state minimum. Lenders require "full coverage," which includes collision and comprehensive insurance with specific maximum deductibles (usually $500 or $1,000) to protect their collateral.
Why Louisiana Insurance Rates are High
Even at the minimum level, Louisiana drivers often pay more than those in other states. Several factors contribute to this:
- Legal Environment: Louisiana has historically had a high volume of bodily injury claims and lawsuits, which increases the cost of doing business for insurers.
- Uninsured Drivers: Because a significant portion of the population drives without insurance, the cost of paying out UM/UIM claims is baked into everyone else's premiums.
- Environmental Factors: Louisiana's vulnerability to tropical storms and flooding makes "Comprehensive" coverage expensive, but even "Liability-only" rates are affected by the overall risk profile of the state's geography.
- The "Jury Trial" Threshold: Louisiana has a unique threshold for jury trials in civil cases. If a claim is below a certain dollar amount, it is often decided by a judge rather than a jury, which some insurers argue impacts settlement behaviors.
Penalties for Driving Without Minimum Coverage
The consequences of failing to maintain the 15/30/25 minimums go beyond the "No Pay, No Play" restrictions. The Louisiana Department of Public Safety (DPS) and the Office of Motor Vehicles (OMV) enforce strict penalties:
- Fines: Initial fines for lack of insurance can range from $500 to $1,000.
- Registration Suspension: The OMV can suspend your vehicle registration, making it illegal to drive your car.
- Impoundment: If you are pulled over and cannot provide proof of insurance, the officer has the authority to remove the vehicle’s license plate and impound the car immediately. To recover it, you must provide proof of insurance and pay significant reinstatement fees.
- Yellow/Orange Tags: Louisiana uses a "flagging" system. If your insurance cancels and the OMV is notified (which happens electronically in 2026), a flag is placed on your record, preventing you from renewing your license or registration until the matter is resolved and fees are paid.
Expert Practical Guidance
When deciding if the minimum coverage is right for you, perform a "Vulnerability Audit." Ask yourself these three questions:
- What do I own? If you have a home, land, or more than $10,000 in savings, minimum limits are likely too low to protect you.
- How much do I drive? If you have a long commute on high-traffic corridors like I-10 or I-12, your statistical likelihood of an accident is higher, making higher limits a more logical investment.
- Could I afford to replace my car? If your car is damaged in an accident you caused, and you only have minimum liability, you will receive $0 from your insurer. If you can't afford to buy a new car tomorrow, you need collision coverage.
If the cost of higher limits is prohibitive, consider increasing your deductibles on collision and comprehensive coverage rather than lowering your liability limits. Increasing a deductible from $500 to $1,000 can significantly lower your premium while still maintaining the high liability protection that prevents total financial ruin.
Frequently Asked Questions
Does Louisiana's minimum insurance cover me if I drive into another state?
Yes. Most auto insurance policies include an "out-of-state coverage" clause. If you have a Louisiana policy with 15/30/25 limits and you have an accident in a state with higher requirements (such as $25,000/$50,000), your policy will usually automatically adjust to meet that state’s legal minimum for that specific incident.
Can a dealership sell me a car with only minimum coverage?
While a dealership can legally sell you the vehicle, they will not let you drive it off the lot if you are financing it through them or a third-party bank. Lenders require collision and comprehensive insurance to protect their interest in the vehicle. Minimum liability coverage only satisfies the state, not the bank.
If I'm not at fault, does my minimum coverage still matter?
Yes, because of the "No Pay, No Play" law. If you don't have the 15/30/25 minimums, you lose the right to collect the first $15,000 of bodily injury and $25,000 of property damage from the person who hit you. Carrying the minimum preserves your legal rights.
Why is my "minimum" policy so expensive in Louisiana compared to other states?
Louisiana's high rates are due to a combination of high litigation rates, a high percentage of uninsured motorists, and the risk of catastrophic weather events. Insurers spread these costs across all policyholders in the state.
Is the Uninsured Motorist (UM) coverage required in Louisiana?
It is not required, but it is automatically included in your policy quote by law. To remove it and stick to the 15/30/25 minimum, you must sign a specific WAIVER form explicitly rejecting the coverage.
Final Recommendation
While the 15/30/25 minimum coverage fulfills your legal obligation to the state of Louisiana, it is rarely enough to provide true financial security in 2026. For those with any significant assets or those who drive a vehicle with high resale value, we strongly recommend increasing your liability limits to at least 100/300/100 and adding Uninsured Motorist coverage. At a minimum, every driver should ensure they have their insurance identification card accessible at all times to avoid the immediate impoundment penalties enforced by Louisiana law.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
