The world’s richest people are measured by net worth—the sum of their total financial and physical assets minus all outstanding liabilities. Global benchmarks evaluate wealth primarily using publicly traded stock equity, audited private company valuations, real estate holdings, cash reserves, and regulatory disclosures compiled by real-time tracking indexes and institutional financial reporting.
Metrics and Criteria Defining Ultra-High Net Worth
To systematically evaluate global wealth, financial institutions and economic researchers categorize wealth holders based on total net worth and asset liquidity. Net worth represents the monetary value of everything an individual owns, less any liabilities such as debt, loans, and legal claims.
Wealth Stratification Terminology
In economic analysis and private banking, high-net-worth individuals are grouped into established wealth tiers:
- High-Net-Worth Individuals (HNWIs): Individuals possessing liquid investable assets of at least $1 million, excluding primary residences and personal property.
- Very-High-Net-Worth Individuals (VHNWIs): Individuals holding investable assets between $5 million and $30 million.
- Ultra-High-Net-Worth Individuals (UHNWIs): Individuals with a total net worth exceeding $30 million. This cohort represents the primary baseline for elite wealth tracking.
- Centimillionaires: Individuals whose net worth equals or exceeds $100 million.
- Billionaires: Individuals holding a verified net worth of $1 billion ($1,000,000,000) or more.
- Decabillionaires: Individuals with a net worth exceeding $10 billion.
- Centibillionaires: Individuals possessing a total net worth of $100 billion or more.
Balance Sheet Accounting for Elite Wealth
Calculating individual wealth requires a balance sheet assessment similar to corporate accounting. An individual's gross wealth includes:
- Publicly Traded Equity: Shares held directly or beneficially in publicly listed corporations, valued at current mark-to-market prices.
- Private Equity & Enterprise Value: Equity stakes in non-public companies, estimated using cash flow multiples, recent fundraising valuation rounds, or public comparable metrics.
- Real Estate Assets: Holdings in commercial properties, residential estates, agricultural land, and real estate investment trusts (REITs).
- Liquid Reserves & Fixed Income: Cash, bank deposits, short-term money market funds, sovereign bonds, and debt securities.
- Alternative Assets: Tangible luxury assets, including private aircraft, superyachts, art collections, rare collectibles, and intellectual property royalties.
To determine net worth, analysts deduct documented liabilities, such as mortgages, securities-backed loans, corporate debt obligations, and legal commitments.
Methodologies of Primary Wealth Indices
Tracking ultra-high net worth requires continuous monitoring of volatile capital markets, currency conversion rates, and ownership filings. Two dominant financial publishers—Bloomberg and Forbes—maintain the most widely cited real-time benchmarks. Institutional wealth reports, such as the annual studies published by UBS, provide macroeconomic contexts for global wealth distribution.
- Public Filings: SEC Form 4, Schedule 13D, 10-K
- Gross Asset Valuation: Public Stocks + Private Enterprise
- Less Verified Liabilities & Collateral Borrowing
- Net Worth Output (Mark-to-Market Real Time)
Bloomberg Billionaires Index
Introduced in 2012, the Bloomberg Billionaires Index provides a daily mark-to-market ranking of the world's 500 wealthiest people. The system updates every business day after the close of equity markets in New York.
Bloomberg’s methodology relies on direct analysis of stock exchange movement, exchange rates, corporate revenue multiples, cash-flow models, and corporate regulatory reports. When calculating private assets, Bloomberg applies enterprise value-to-EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) or price-to-earnings multiples derived from public peers, often applying an illiquidity discount ranging from 10% to 30% depending on market transparency.
Forbes Real-Time & Annual Billionaires List
Forbes has tracked global wealth since 1987 through its annual world billionaires list and maintains a daily real-time wealth tracker. Forbes relies on a combination of financial documentation, field interviews, regulatory disclosures, exchange rates, and public market data.
Forbes evaluates private enterprises by auditing revenue statements, venture capital financing rounds, independent appraisals, and industry sector benchmarks. Real-time updates reflect changes in underlying public equity valuations throughout the trading day.
Data Verification and Discrepancies
Discrepancies often emerge between different wealth tracking platforms due to variation in estimation methodologies:
- Illiquidity Discounts: Financial platforms apply varying discount rates to non-public corporate equity to account for marketability restrictions.
- Pledged Shares: One methodology may subtract stock shares pledged as collateral for bank loans, while another includes the full share count until liquidation occurs.
- Beneficial Ownership Structures: Assets held within irrevocable trusts, offshore holding entities, or foundation structures are interpreted differently based on beneficial control rights.
- Debt Allocation: Private debt obligations are frequently unlisted, requiring analysts to estimate liabilities through indirect disclosures or accredited reporting.
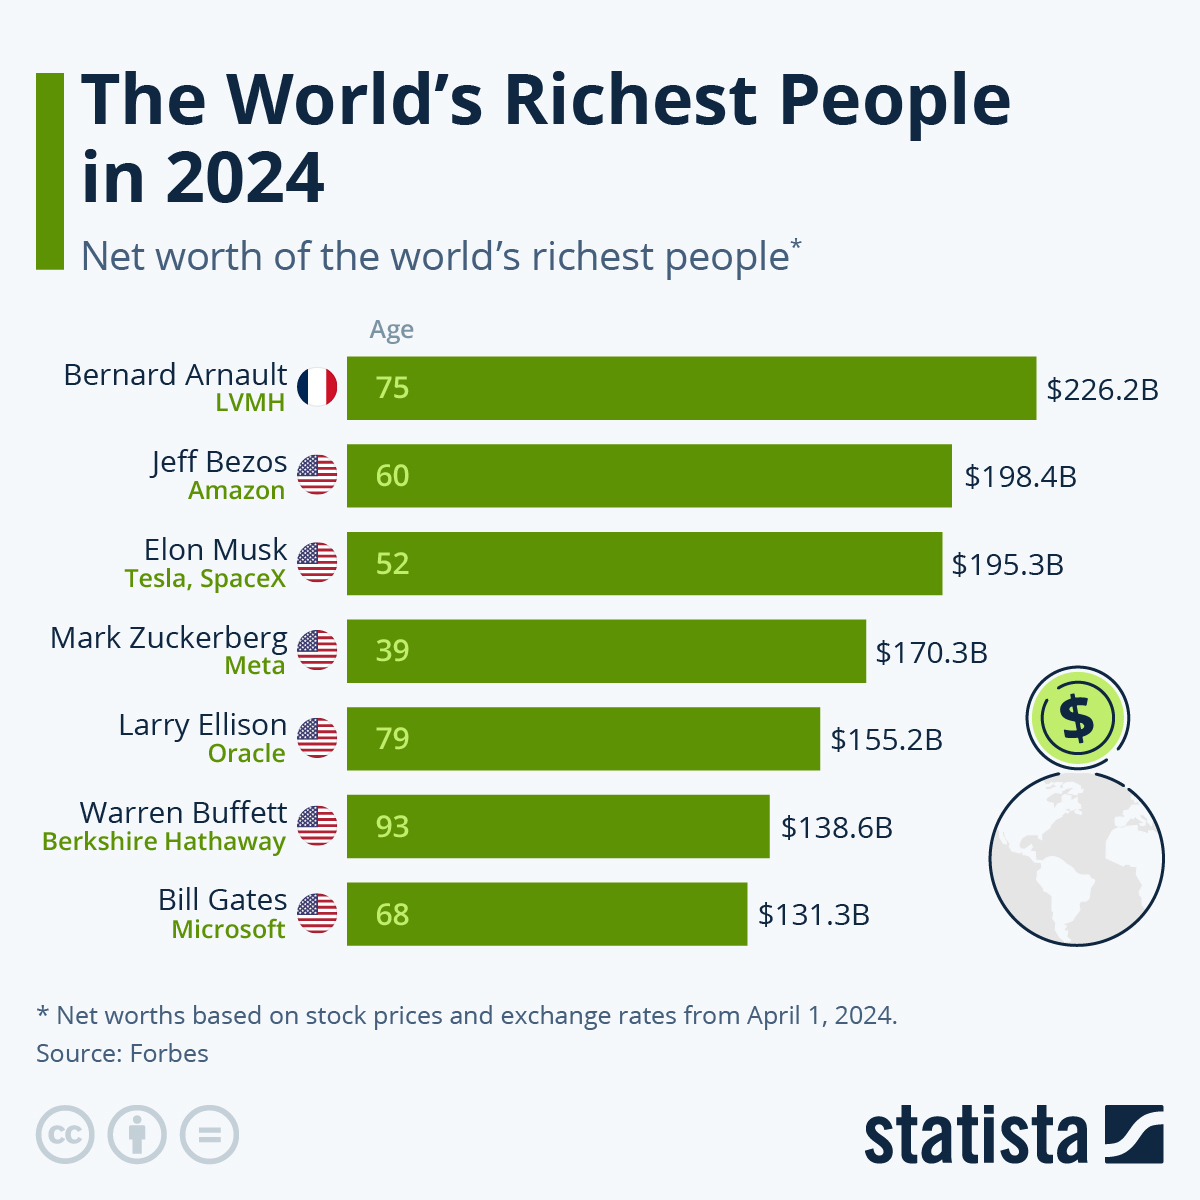
Comparative Matrix: Wealth Tracking Methodologies
The table below contrasts the main frameworks used by major publishers and reporting institutions to evaluate high net worth individuals.
| Metric / Platform | Update Frequency | Primary Valuation Method | Key Data Sources | Main Methodological Limitations |
|---|---|---|---|---|
| Bloomberg Billionaires Index | Daily (End of US Trading Day) | Mark-to-market public equity + Private DCF/Multiple analysis | SEC filings, stock exchanges, news reports, corporate registry data | Applies generalized illiquidity discounts; relies on market estimates for non-public debt. |
| Forbes Real-Time Index | Intraday (Continuous during trading hours) | Live public equity monitoring + Private valuation benchmarks | Financial disclosures, public filings, broker estimates, executive interviews | Real-time volatility causes rapid short-term net worth swings; private valuations update infrequently. |
| UBS Global Wealth Report | Annual / Periodic | National accounts, macroeconomic modeling, distribution estimates | Central bank balance sheets, household surveys, World Bank metrics | Aggregates household-level data; does not provide real-time individual rankings. |
| Wealth-X (Altrata) | Continuous database updates | Dossier-level asset mapping and equity ownership models | Proprietary dossiers, public deeds, corporate registrations, luxury asset registries | Coverage depends on public register availability; restricted in jurisdictions with low transparency. |
Financial Mechanisms Behind Modern Mega-Wealth
The majority of contemporary ultra-high net worth is generated through concentrated equity ownership in hyper-scalable businesses, combined with dynamic financial engineering and asset preservation strategies.
Concentrated Public and Private Equity
Modern centibillionaires rarely achieve their status through accumulated salary or traditional fixed-income yields. Instead, wealth is driven by holding massive, non-diversified equity stakes in foundational companies within technology, industrial manufacturing, retail, and luxury consumer markets.
As public equity values appreciate through network effects and global scaling, an insider's ownership stake expands exponentially without triggering an immediate tax liability, provided the equity remains unliquidated.
Securities-Backed Lending and Cash Flow Mechanisms
Liquidating shares to generate cash creates tax liabilities due to capital gains taxes. To access liquidity without selling equity, ultra-wealthy executives often use securities-backed lending (SBL) or non-purpose lines of credit.
Under this mechanism:
- An individual pledges a portion of their public stock portfolio as collateral to a private bank or investment firm.
- The financial institution grants a revolving credit facility, typically ranging from 20% to 50% of the collateral's value (Loan-to-Value ratio).
- The borrower pays interest on drawn funds at variable rates tied to benchmarks like the Secured Overnight Financing Rate (SOFR).
- Because borrowed funds do not count as realized income under most tax codes, no capital gains tax is triggered at the time of borrowing.
This strategy—often called "Buy, Borrow, Die"—enables wealthy individuals to fund lifestyle expenses, estate developments, and secondary investments while retaining corporate voting control and dividend entitlements.
Family Office Structures and Capital Allocation
Ultra-wealthy individuals manage their holdings through dedicated asset management entities known as single-family offices (SFOs) or multi-family offices (MFOs). A family office acts as a private wealth management organization that handles investment management, legal governance, tax planning, philanthropic activities, and succession planning.
According to global family office studies published by institutional investment managers, typical asset allocations for elite family offices include:
- Direct Private Equity & Venture Capital: Direct stakes in late-stage startups and middle-market operating enterprises.
- Commercial Real Estate: Strategic acquisitions of prime office towers, industrial logistics parks, and luxury residential real estate.
- Hedge Funds and Quantitative Strategies: Allocations to long/short equity, global macro, and arbitrage strategies to hedge against market downturns.
- Direct Debt Instruments: Mezzanine financing, private credit, and distressed debt lending.
Historical Context and Inflation-Adjusted Perspectives
Comparing the net worth of contemporary centibillionaires to historical figures requires accounting for inflation, currency standard shifts, and relative shares of global economic output (Gross Domestic Product).
Notable Historical Figures
Economic historians frequently rank historical figures using peak assets calculated as a percentage of their contemporary national or global GDP:
- Mansa Musa (1280–1337): Ruler of the Mali Empire, whose control over West Africa's gold production and salt trade made him one of the wealthiest rulers in recorded history.
- Jakob Fugger (1459–1525): European merchant banker who controlled copper, silver, and merchant trade monopolies under the Habsburg Dynasty. His net worth was estimated to represent nearly 2% of Europe’s total GDP at its peak.
- John D. Rockefeller (1839–1937): Founder of Standard Oil. At his peak, Rockefeller’s wealth reached approximately $1.4 billion in 1913 dollars, equivalent to roughly 1.5% to 2% of total U.S. GDP at the time. Adjusted for relative economic power, his net worth is estimated between $300 billion and $400 billion in modern terms.
- Andrew Carnegie (1835–1919): Industrialist who sold Carnegie Steel Company to J.P. Morgan’s U.S. Steel syndicate in 1901 for $480 million, a sum that represented a significant fraction of U.S. national economic activity.
- Land & Commodity Monopolies (e.g., Mansa Musa, Fugger)
- Industrial Manufacturing & Energy (e.g., Rockefeller, Carnegie)
- Digital Platforms, Enterprise Tech, & Capital Markets (Modern Era)
Evolution of Wealth Sources
The structural drivers of top-tier wealth have shifted across economic eras:
- Agrarian and Feudal Era: Wealth was tied directly to physical land ownership, natural resource extraction, and sovereign tax rights.
- Industrial Revolution: Wealth concentrated among owners of heavy industry, rail transportation networks, oil extraction infrastructure, and steel manufacturing.
- Digital & Globalization Age: Modern wealth generation is dominated by platform economics, software scale, intellectual property, capital allocation networks, and globalized supply chains.
Regulatory Reporting, Governance, and Philanthropy
The financial activities of ultra-high-net-worth individuals are subject to complex legal regulatory frameworks, tax compliance regimes, and public disclosure requirements.
Verifying Wealth via SEC Regulatory Filings
In the United States, equity holdings of public company founders, directors, and beneficial owners holding more than 5% of a equity class must be reported to the regulatory authorities. Analysts rely on official disclosure documents accessed through the U.S. Securities and Exchange Commission EDGAR System:
- Form 3, 4, and 5: Filed by corporate insiders (officers, directors, and major shareholders) to disclose initial ownership and subsequent equity buys, sales, or option exercises.
- Schedule 13D and 13G: Mandatory filings for investors acquiring more than 5% of a company's voting stock. Schedule 13D signals active intent to influence corporate control, while 13G indicates passive investment intent.
- Form 10-K and 10-Q: Annual and quarterly corporate reports detailing executive compensation, outstanding share classes, beneficial ownership tables, and total share counts.
- Form 13F: Institutional investment managers with at least $100 million in equity assets under management must file quarterly reports disclosing their long equity holdings.
Tax Mechanisms and Estate Planning Structures
To protect capital across generations, wealth managers use legal financial vehicles that optimize tax efficiency:
- Irrevocable Dynasty Trusts: Trusts set up to pass wealth to future generations without incurring successive estate taxes.
- Grantor Retained Annuity Trusts (GRATs): Financial instruments used to transfer appreciated assets to beneficiaries with minimal gift-tax consequences.
- Offshore Jurisdictions: Holding entities established in countries with low or zero corporate tax regimes (such as the Cayman Islands, Bermuda, or Switzerland) to manage global investments.
- Step-Up in Basis: A legal tax provision that resets the cost basis of an inherited asset to its fair market value at the date of the owner's death, eliminating taxable capital gains accrued during the decedent’s lifetime.
Philanthropic Initiatives and Private Foundations
A significant portion of elite wealth is directed into institutional philanthropy. Major mechanisms include:
- Private Non-Operating Foundations: Tax-exempt charitable entities created by individuals or families to fund grant initiatives, medical research, and educational institutions.
- Donor-Advised Funds (DAFs): Charitable vehicles allowing donors to receive an immediate tax deduction while retaining advisory privileges over investment grants over time.
- The Giving Pledge: A non-binding commitment initiated by Warren Buffett and Bill Gates in 2010, inviting billionaires to commit at least half of their wealth to philanthropic endeavors during their lifetimes or in their wills.
Frequently Asked Questions
How is a billionaire's net worth calculated in real time?
Real-time wealth tracking uses software algorithms linked directly to public stock market price feeds. The tracker multiplies an individual's verified share counts in publicly traded companies by the current share price on exchange networks. Private company stakes are adjusted based on market indices, currency rates, or updated fundraising valuations, while non-equity assets and known liabilities remain fixed until new financial filings or audits become available.
Why do Forbes and Bloomberg rankings sometimes differ?
Discrepancies occur because both platforms use proprietary assumptions for non-public data. Differences arise from how each platform values private businesses, applies illiquidity discounts, accounts for stock pledged as collateral for debt, and verifies beneficial ownership within complex trust structures.
Are private company valuations as reliable as public equity figures?
No. Public equity valuations are anchored by live trading liquidity and market clearing prices. Private company valuations rely on private funding rounds, internal DCF models, or executive estimates. These figures can be inflated by preference shares, liquidation guarantees, or outdated financial performance data that do not reflect current market conditions.
How does debt affect the overall net worth calculation?
Net worth is strictly an equity figure: Total Assets minus Total Liabilities. If an individual holds $10 billion in stock but has taken $2 billion in securities-backed bank loans, their net worth is $8 billion. Unsecured debt, corporate guarantees, and pledged asset collateral are all subtracted from gross asset values when verified.
What is the difference between net worth and liquid cash flow?
Net worth reflects the total value of all owned assets minus debts, regardless of whether those assets can be spent immediately. Liquid cash flow refers exclusively to accessible money—such as cash balances, liquid money market funds, or short-term treasuries—that can be spent without liquidating long-term investments or incurring capital gains taxes. Most centibillionaires hold only a small fraction of their net worth in cash.
Best Practices for Evaluating Ultra-High Net Worth Data
When analyzing high-net-worth data for institutional research, academic studies, or financial reporting, apply these analytical principles:
- Cross-Reference Regulatory Filings: Verify public equity share counts using official registry sources, such as SEC EDGAR filings or equivalent international regulatory databases. Do not rely solely on press releases or self-reported estimates.
- Separate Liquid Assets from Illiquid Equity: Distinguish between accessible cash equivalents and paper net worth tied to concentrated, volatile equity holdings that cannot be sold without depressing share prices.
- Account for Pledged Shares and Liabilities: Examine proxy statements (DEF 14A) to identify whether insider stock holdings are pledged as collateral for personal bank loans or credit lines.
- Apply Illiquidity Discounts to Private Assets: When evaluating non-listed entities, apply realistic illiquidity discounts (typically 15% to 30%) to mirror secondary market execution realities.
Image Gallery
Select an image to open it in a new tab.

Declan O'Connor
Higher Education and Campus Culture Reporter
