Countrywide Auto Insurance Coverage Explained: A Complete Guide to Protection and Policy Options
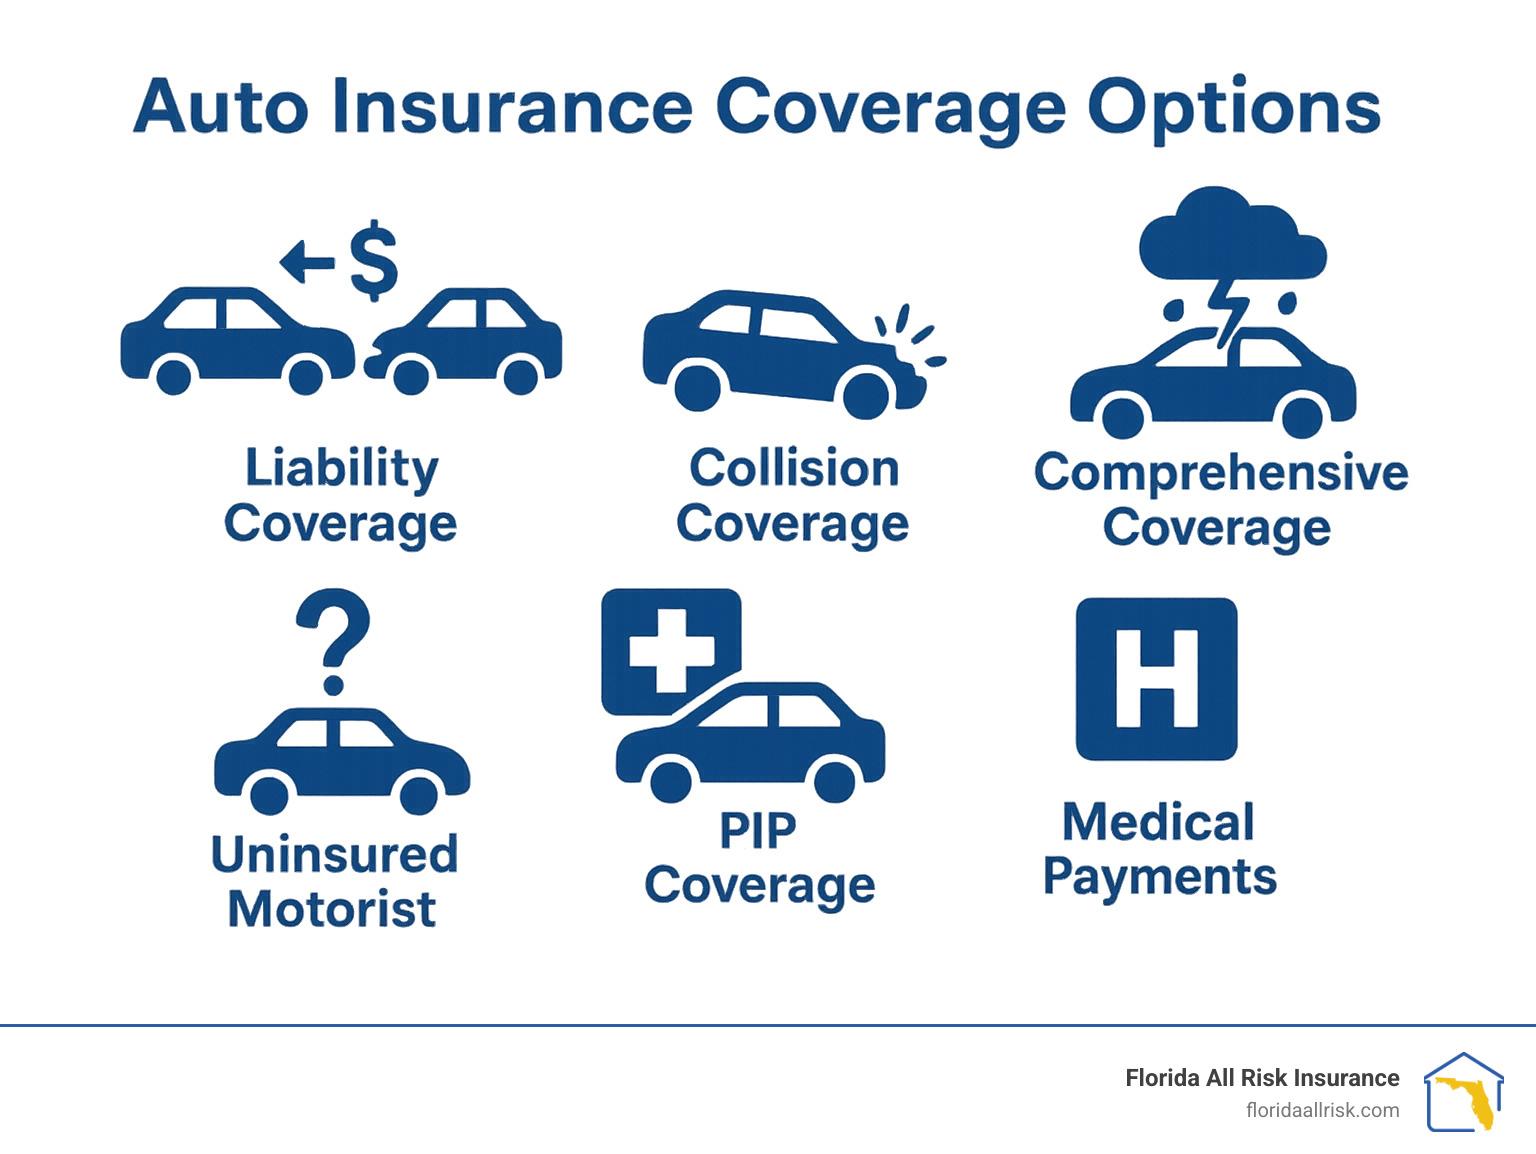
Countrywide auto insurance coverage refers to the suite of financial protections provided by the Countrywide brand—often associated with its legacy under Countrywide Financial and subsequent integration into broader carrier networks—designed to shield drivers from liability, vehicle damage, and medical expenses. In 2026, this coverage encompasses state-mandated minimums and optional high-limit protections essential for navigating modern road risks and rising vehicle repair costs.
Understanding auto insurance requires looking beyond monthly premiums to the specific "layers" of protection that activate during different types of incidents. Whether you are dealing with a legacy policy or a new quote under the Countrywide banner, the structure of your coverage determines your financial resilience following an accident, theft, or environmental damage.
The Evolution and Context of Countrywide Insurance in 2026
To understand Countrywide auto insurance coverage, one must first clarify the entity's position in the current market. Originally a powerhouse in the mortgage and financial services sector, Countrywide’s insurance operations were largely influenced by its acquisition by Bank of America and subsequent restructuring. In 2026, the term "Countrywide" in insurance often refers to policies serviced through specific agency networks or legacy blocks of business that continue to provide standardized national coverage.
For most policyholders, Countrywide coverage is synonymous with comprehensive national protection. This means the policy is designed to meet or exceed the varied legal requirements of different states while providing a consistent claims experience regardless of where the accident occurs. As vehicle technology has advanced—with 2026 models featuring complex autonomous driving aids and expensive sensor arrays—the depth of this coverage has become more critical than ever.
Core Components of Liability Coverage
Liability insurance is the foundation of any countrywide policy. It is designed to protect your assets if you are found legally responsible for an accident that causes injury to others or damage to their property.
Bodily Injury Liability (BI)
Bodily Injury Liability covers the medical bills, rehabilitation costs, and sometimes the lost wages of other people injured in an accident where you are at fault. In 2026, medical inflation has significantly increased the "cost per claim." A standard countrywide policy typically breaks this down into two limits:
- Per Person: The maximum amount paid for a single individual’s injuries.
- Per Accident: The total amount the insurer will pay for all injuries sustained in a single event.
Relying on state minimums is increasingly risky. For example, a state minimum of $25,000 for bodily injury may not even cover a single day of intensive care in 2026. Most experts recommend limits of at least $100,000/$300,000 to protect personal savings from litigation.
Property Damage Liability (PD)
This component pays for damage you cause to someone else’s property. While this usually means another vehicle, it also covers fences, lamp posts, and buildings. With the average cost of a new electric vehicle exceeding $60,000 in 2026, a property damage limit of $25,000 is often insufficient. Countrywide policies allow for higher limits to ensure that a multi-car pileup or a collision with a high-end vehicle does not lead to personal bankruptcy.
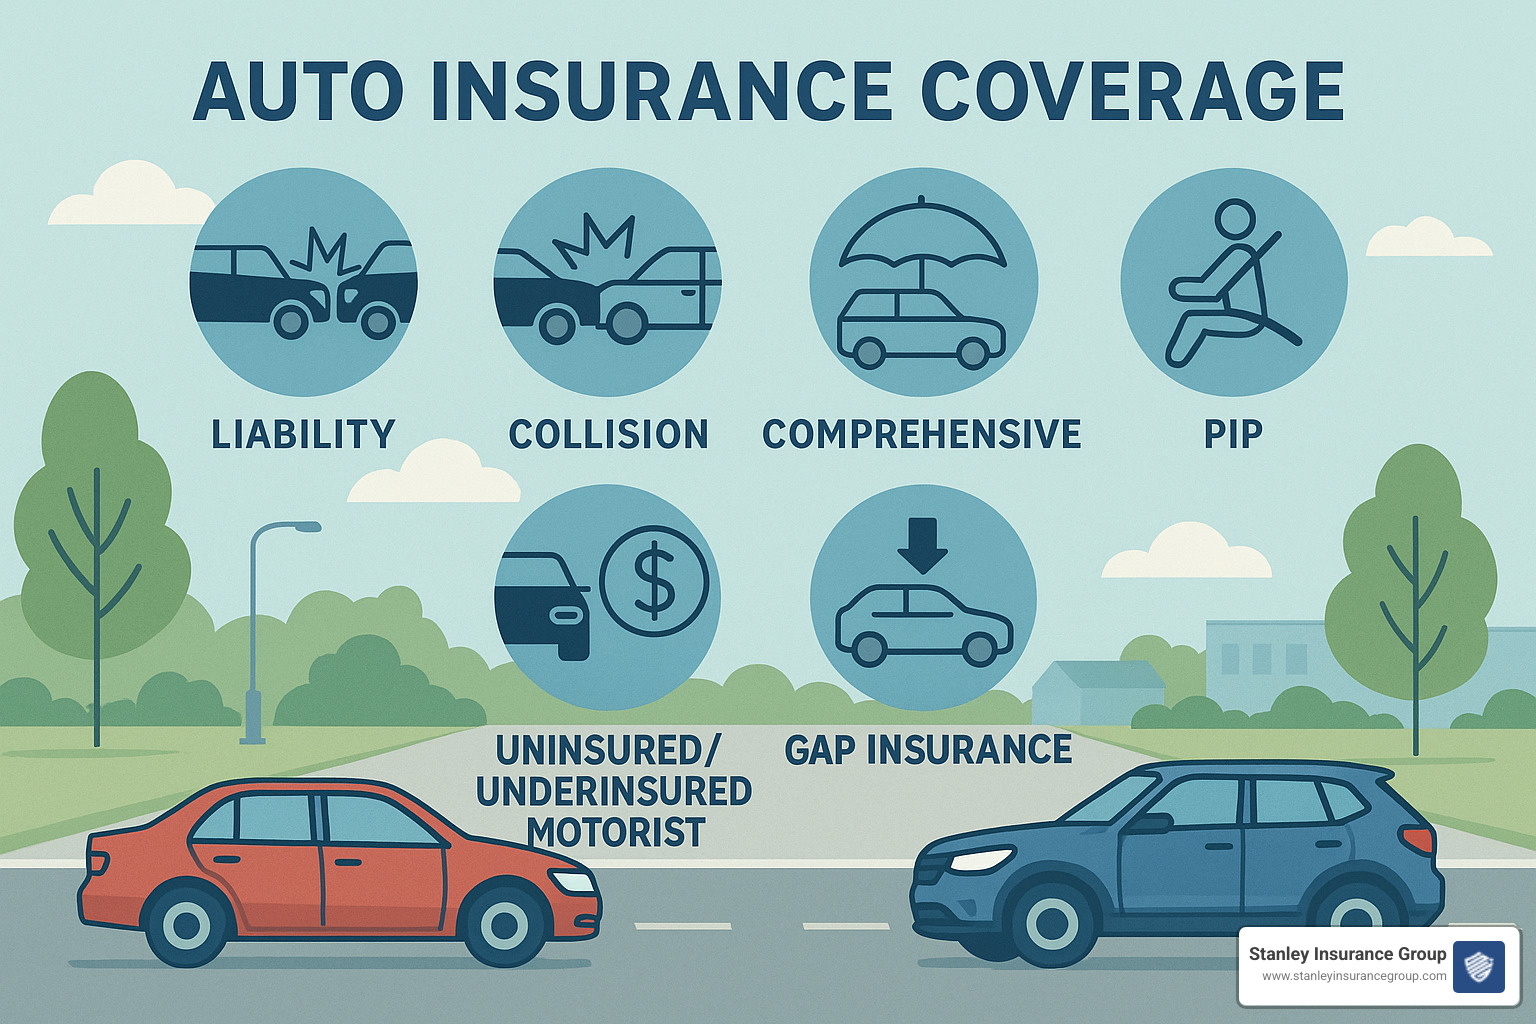
Physical Damage Protections: Collision and Comprehensive
While liability protects others, collision and comprehensive coverages protect your investment. In 2026, as vehicle values remain high due to advanced technology and supply chain stabilization, these coverages are often required by lienholders for financed or leased vehicles.
Collision Coverage
Collision insurance pays for damage to your vehicle resulting from a crash with another car or an object (like a tree or a guardrail), regardless of who is at fault. In the context of countrywide coverage, collision is essential for modern vehicles because even minor "fender benders" now involve recalibrating cameras and replacing LIDAR sensors, costs that can easily reach several thousand dollars.
Comprehensive Coverage
Often called "Other Than Collision," comprehensive coverage protects your vehicle from non-accident-related incidents. This includes:
- Theft and Vandalism: High-tech car theft methods in 2026 have made this coverage a priority for urban drivers.
- Natural Disasters: Protection against floods, hail, and fire.
- Animal Strikes: Coverage for hitting a deer or other wildlife.
- Glass Breakage: Many countrywide policies offer a specific glass deductible or "full glass" coverage, recognizing that modern windshields are integral to a vehicle’s safety systems.
Medical Payments and Personal Injury Protection (PIP)
The "who pays first" question for medical bills is answered by these two types of coverage, which vary significantly depending on whether you live in a "no-fault" or "tort" state.
Personal Injury Protection (PIP)
Required in no-fault states, PIP is a robust form of coverage that pays for medical expenses, lost wages, and even funeral costs for you and your passengers, regardless of fault. In 2026, PIP remains a cornerstone of countrywide insurance strategies because it provides immediate liquidity for medical needs without waiting for a lengthy fault determination process.
Medical Payments (MedPay)
MedPay is a more limited version of PIP, usually available in states that do not follow no-fault laws. It specifically covers medical and funeral expenses for you and your passengers. Unlike PIP, it typically does not cover lost wages or childcare expenses necessitated by an injury.
Uninsured and Underinsured Motorist Coverage (UM/UIM)
Despite legal requirements, a significant percentage of drivers in 2026 operate vehicles without insurance or with limits too low to cover serious accidents. Uninsured Motorist (UM) coverage protects you if you are hit by a driver who has no insurance or by a hit-and-run driver.
Underinsured Motorist (UIM) coverage kicks in when the at-fault driver has insurance, but their limits are exhausted before your bills are fully paid. For instance, if an at-fault driver has a $25,000 limit but your medical bills are $75,000, your UIM coverage would bridge the $50,000 gap. In a countrywide policy, this is often considered the most "undervalued" protection by consumers until they actually need it.
2026 Coverage Comparison Table
The following table outlines the differences between basic, standard, and premium countrywide auto insurance configurations based on 2026 market standards.
| Coverage Type | Basic (State Minimum) | Standard (Recommended) | Premium (Asset Protection) |
|---|---|---|---|
| Bodily Injury | $25k / $50k | $100k / $300k | $250k / $500k |
| Property Damage | $10k - $25k | $50k - $100k | $100k+ |
| Collision/Comp | Usually Excluded | Included ($500 Ded.) | Included ($250 Ded. or lower) |
| UM/UIM | Often Excluded/Minimum | Matches Liability | Matches Liability |
| Roadside/Rental | Not Included | Included (Standard) | Included (High Daily Limit) |
| Gap Insurance | Not Included | Optional Add-on | Included |
Specialized Add-ons and Endorsements
Beyond the standard pillars of insurance, several specialized coverages are frequently integrated into countrywide policies to address specific 2026 automotive trends.
Gap Insurance
As vehicle prices stabilized at a high plateau in 2026, many drivers find themselves "underwater" on their car loans—owing more than the car is worth. If a vehicle is totaled, standard collision coverage only pays the Actual Cash Value (ACV). Gap insurance covers the difference between the ACV and the remaining balance on your loan or lease.
New Car Replacement
For vehicles less than two years old, this endorsement ensures that if your car is totaled, the insurer pays for a brand-new vehicle of the same make and model, rather than just the depreciated value of your old one.
Telematics and Usage-Based Insurance (UBI)
By 2026, most countrywide policies offer a telematics option. By using a smartphone app or a plug-in device to monitor braking, acceleration, and speed, safe drivers can receive significant discounts. This has become a primary way for consumers to offset the generally higher insurance premiums seen in the mid-2020s.
Factors Influencing Countrywide Premiums in 2026
The cost of your coverage is not arbitrary; it is a calculated risk assessment. Several factors are particularly influential in the current year:
- Vehicle Complexity: The cost to repair "smart" components (sensors, cameras, and batteries) has driven up the cost of collision and comprehensive claims.
- Credit-Based Insurance Scores: In most states, your financial history remains a significant predictor of claim frequency, influencing your premium.
- Geographic Density: Drivers in high-traffic urban areas face higher premiums due to the increased statistical likelihood of both minor and major collisions.
- Climate Risks: Regional "countrywide" adjustments now account for the increased frequency of severe weather events, which impact comprehensive coverage rates.
How to Verify and Manage Your Coverage
To ensure your countrywide auto insurance is performing as expected, you must be proactive in reviewing your Declarations Page. This document is the "summary" of your policy and lists exactly which coverages are active, their limits, and your deductibles.
Steps to Optimize Your Policy:
- Annual Review: Contact your agent or use the mobile portal every 12 months. Your life circumstances (moving, marriage, new job) often trigger discount eligibility.
- Deductible Assessment: If you have a healthy emergency fund, raising your deductible from $500 to $1,000 can lower your monthly premium by 15-30%.
- Discount Stacking: Ensure you are receiving credit for safety features (lane-keep assist, anti-theft) and lifestyle factors (good student, military, or multi-policy bundles).
Common Mistakes in Auto Insurance Selection
Many drivers focus exclusively on the monthly "sticker price," which can lead to expensive gaps in protection.
- Underinsuring for Liability: In 2026, a single serious accident can result in a judgment that exceeds $250,000. If your limit is $50,000, you are personally responsible for the remaining $200,000.
- Ignoring UM/UIM: Because this coverage is often optional, drivers drop it to save a few dollars. However, this is the only coverage that protects you from others' negligence.
- Assuming "Full Coverage" is a Legal Term: "Full coverage" is a marketing term, not a legal one. It usually refers to having liability, collision, and comprehensive, but it does not mean you are covered for everything (like wear and tear or mechanical breakdowns).
Frequently Asked Questions
Does countrywide auto insurance cover me if I drive a rental car?
Most standard countrywide policies extend your existing coverages (Liability, Collision, Comprehensive) to a rental vehicle used for personal purposes within the U.S. and Canada. However, the insurer will only pay up to the limits of your own car. If you have a $500 deductible on your personal car, it will apply to the rental as well.
How does the claims process work in 2026?
The process is largely digitized. Most policyholders file claims via a mobile app by uploading photos of the damage. For countrywide carriers, AI-driven photo estimation can often provide a repair quote within hours. Once approved, the payment is sent directly to a "preferred" repair shop or via electronic transfer to the policyholder.
What is the difference between Actual Cash Value and Replacement Cost?
Actual Cash Value (ACV) pays you what the car was worth at the time of the accident, accounting for depreciation. Replacement Cost (rare in auto insurance except as a specific endorsement) pays what it would cost to buy a brand-new version of that car today. Most countrywide policies default to ACV.
Is roadside assistance included in all countrywide policies?
No, roadside assistance is typically an optional endorsement. While it is inexpensive—often costing only a few dollars per month—it must be specifically added to your policy. It covers towing, fuel delivery, lockout services, and battery jumps.
Can I change my coverage limits in the middle of a policy term?
Yes. You do not have to wait for your policy to renew to increase your limits or add new types of coverage. If you purchase a new vehicle or move to a new area, you should update your policy immediately. Your premium will be pro-rated for the remainder of the term.
Practical Recommendation
When managing countrywide auto insurance in 2026, prioritize Liability and UM/UIM limits over low deductibles. While a $1,000 deductible might feel painful during a claim, an insufficient liability limit can be life-altering. Aim for a "100/300/100" policy structure at a minimum. If you own a home or have significant assets, consider an Umbrella Policy, which provides an extra layer of liability protection—typically $1 million or more—that sits on top of your auto and homeowners' insurance.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
