Choosing Between an Annuity and Life Insurance: A Comprehensive 2026 Guide
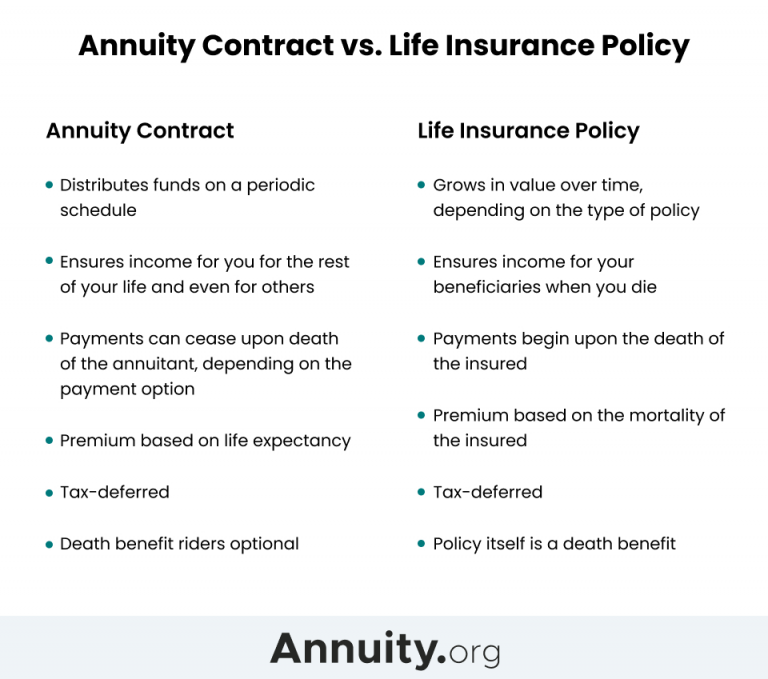
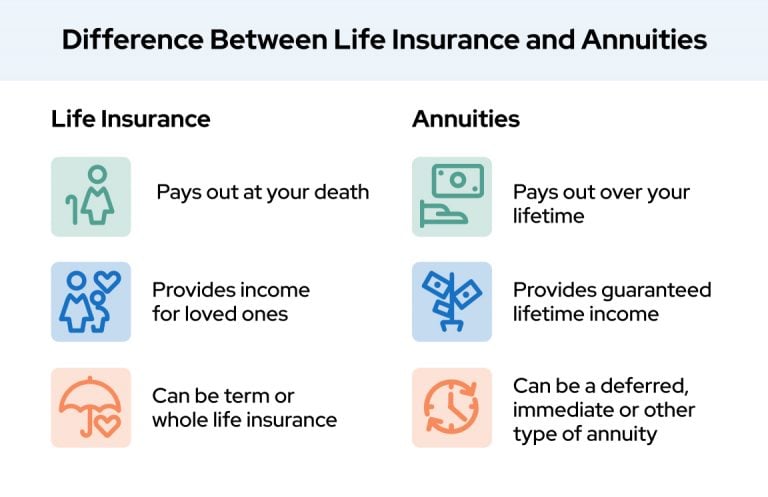
Choosing between an annuity and life insurance depends on whether your primary financial goal is to provide for yourself during retirement or to provide for your beneficiaries after your death. Annuities are designed to mitigate the risk of outliving your assets, while life insurance protects against the financial consequences of premature death.
As we navigate the financial landscape of 2026, many individuals find themselves at a crossroads when planning for the future. The decision is rarely about which product is "better" in a vacuum, but rather which tool effectively addresses the specific risks you face. With the recent shifts in tax laws and the sunsetting of various provisions from previous years, understanding the structural differences between these two vehicles is essential for maintaining long-term solvency and ensuring a legacy for your heirs.
Understanding the Core Purpose: Longevity vs. Mortality
The most fundamental distinction between an annuity and life insurance is the "risk" they are designed to hedge. In the world of actuarial science, these products sit on opposite sides of the same coin.
The Role of Annuities
An annuity is essentially a contract between you and an insurance company where you provide a lump sum or a series of payments in exchange for regular disbursements, beginning either immediately or at some point in the future. In 2026, with medical advancements extending life expectancy, the "longevity risk"—the danger of outliving your money—has become a primary concern for retirees. An annuity transforms your savings into a guaranteed stream of income that can last for the rest of your life, regardless of how long you live or how the stock market performs.
The Role of Life Insurance
Life insurance is designed to provide a financial safety net for those who depend on you. Whether it is term insurance (covering a specific period) or permanent insurance (providing lifelong coverage with a cash value component), the primary objective is the death benefit. This tax-free payout to beneficiaries ensures that debts are paid, mortgages are covered, and your family's standard of living is maintained if you are no longer there to provide an income.
The Nuances of Annuity Structures in 2026
Annuities have evolved significantly over the last decade, moving from simple fixed-income products to complex financial instruments that can offer market participation with downside protection.
Fixed and Variable Annuities
- Fixed Annuities: These provide a guaranteed interest rate on your investment. They are highly predictable and are often used by conservative investors who want a "pension-like" experience.
- Variable Annuities: These allow you to invest your premiums in sub-accounts (similar to mutual funds). While they offer the potential for higher growth, they also carry market risk. In 2026, many variable annuities come with "Living Benefit" riders that guarantee a minimum income regardless of market performance, though these come at an additional cost.
Fixed Indexed Annuities (FIAs)
FIAs have gained significant traction as of 2026. They credit interest based on the performance of a market index (like the S&P 500) but include a "floor" that prevents you from losing money during market downturns. They offer a middle ground between the safety of fixed annuities and the growth potential of variable annuities.
Immediate vs. Deferred
- Single Premium Immediate Annuities (SPIA): You pay a lump sum and start receiving checks almost immediately. This is often the final step in a retirement plan.
- Deferred Annuities: These allow your money to grow tax-deferred for years or decades before you begin taking withdrawals or annuitizing the contract.

Permanent Life Insurance and the Cash Value Component
While term life insurance is straightforward—paying a death benefit if you die during the term—permanent life insurance (Whole Life, Universal Life, and Variable Universal Life) functions as both a protection tool and a specialized savings vehicle.
How Cash Value Works
A portion of your permanent life insurance premium goes into a cash value account. This account grows tax-deferred over time. In 2026, many high-net-worth individuals use the cash value as a "volatility buffer." When the stock market is down, they can take loans or withdrawals from the policy's cash value to fund their lifestyle, allowing their equity investments time to recover.
Accessing Funds
Unlike an annuity, where withdrawals are generally taxed as ordinary income first (Last-In, First-Out or LIFO), life insurance withdrawals are often treated as a return of basis first (First-In, First-Out or FIFO). Furthermore, policy loans are generally not considered taxable income, provided the policy remains in force. This creates a unique liquidity advantage for life insurance over annuities.
Key Differences in Taxation and Withdrawals
The Internal Revenue Code treats these two products differently, and understanding these rules is vital for tax efficiency in 2026.
Tax Treatment of Annuities
Annuities offer tax-deferred growth, meaning you do not pay taxes on earnings until you take money out. However, when you do withdraw, the IRS assumes the first dollars coming out are the earnings (the "gain"), which are taxed at your ordinary income tax rate. If you are under age 59½, you may also face a 10% federal tax penalty on the earnings portion of your withdrawal, similar to an IRA.
Tax Treatment of Life Insurance
Life insurance is perhaps the most tax-advantaged financial product available under the current tax code.
- Death Benefit: Generally received by beneficiaries 100% income tax-free.
- Cash Value Growth: Grows tax-deferred.
- Withdrawals: Tax-free up to the amount of premiums paid (the basis).
- Loans: Can be taken tax-free against the death benefit as collateral.
However, if a life insurance policy is over-funded too quickly, it may be classified as a Modified Endowment Contract (MEC). If a policy becomes a MEC, it loses its favorable FIFO tax treatment and is taxed similarly to an annuity (LIFO), including the 10% pre-59½ penalty.
Comparison of Features: Annuity vs. Life Insurance
| Feature | Annuity | Life Insurance (Permanent) |
|---|---|---|
| Primary Goal | Retirement Income / Longevity Hedge | Legacy / Death Benefit / Protection |
| Growth Potential | Fixed, Indexed, or Market-Linked | Fixed, Indexed, or Market-Linked |
| Tax on Death Benefit | Beneficiaries pay income tax on gains | Usually 100% Income Tax-Free |
| Withdrawal Taxation | LIFO (Gains taxed first) | FIFO (Basis/Premiums taxed last) |
| Medical Underwriting | None (Usually) | Required (Health exam usually needed) |
| Cost Structure | Fees vary by rider and type | Mortality costs + Admin fees |
| Liquidity | Surrender charges apply early on | Cash value takes time to build |
When to Choose an Annuity
An annuity is likely the better choice if your primary concern is income security. If you have a large 401(k) or IRA but are worried that a market crash early in retirement could deplete your savings, an annuity can provide a "floor" for your essential expenses.
In 2026, annuities are particularly useful for:
- Individuals without a traditional company pension.
- Those who have already maximized their contributions to 401(k)s and IRAs and want more tax-deferred growth.
- People in good health who expect to live well into their 90s.
- Investors who want to "de-risk" their portfolio as they move from the accumulation phase to the distribution phase.
When to Choose Life Insurance
Life insurance is the priority if you have dependents or estate planning needs. Even if you have significant savings, life insurance provides immediate liquidity upon death, which can be used to pay estate taxes, fund a buy-sell agreement for a business, or ensure your spouse can stay in the family home.
Choose life insurance if:
- You have a spouse, children, or disabled family members who depend on your income.
- You want to leave a specific, guaranteed dollar amount to a charity or heir.
- You are looking for a tax-efficient way to transfer wealth (using the tax-free death benefit).
- You need "living benefits" for long-term care (many 2026 policies allow you to access the death benefit early to pay for nursing home costs).
The Hybrid Approach: Why Not Both?
Financial planning is rarely an "either-or" proposition. Many sophisticated plans in 2026 utilize both products to cover different stages of life.
For example, a breadwinner might carry a 30-year term life insurance policy during their working years to protect their family. Simultaneously, they might contribute to a deferred annuity to build a supplemental retirement income stream. As they reach retirement, they might convert some of their assets into an immediate annuity for guaranteed income while maintaining a smaller permanent life insurance policy to cover final expenses or provide a tax-free gift to grandchildren.
Another popular 2026 strategy involves Long-Term Care (LTC) Riders. Both annuities and life insurance policies now frequently offer LTC riders. These allow the policyholder to access the contract value or death benefit to pay for home health care or assisted living, solving a third major risk: the high cost of healthcare in old age.
Costs, Fees, and Surrender Periods
Both products are long-term commitments and come with costs that can erode returns if not understood.
Annuity Costs
Annuities often have "surrender charges," which are penalties for withdrawing more than a certain percentage (usually 10%) of your money during the first 5 to 10 years of the contract. Additionally, variable annuities can have high internal fees, including Mortality and Expense (M&E) risk charges, administrative fees, and investment management fees. According to the Financial Industry Regulatory Authority (FINRA), it is crucial to review the prospectus to understand the total "drag" these fees have on performance.
Life Insurance Costs
Life insurance involves "Cost of Insurance" (COI) charges, which increase as you get older. In the early years of a permanent policy, a large portion of your premium goes toward the commission and the death benefit protection, meaning the cash value builds slowly. If you cancel the policy in the first few years, you may receive very little, if any, money back.
Common Mistakes to Avoid
- Over-funding an Annuity with Qualified Money: Putting an annuity inside an IRA can be redundant because the IRA already provides tax deferral. You should only do this if the specific guarantees of the annuity (like a lifetime income rider) are worth the internal costs.
- Ignoring Inflation: A fixed annuity payment that feels comfortable in 2026 may lose significant purchasing power by 2046. Consider annuities with inflation-protection riders or "cost of living" adjustments.
- Underestimating the Need for Underwriting: You can buy an annuity at almost any age or health status. Life insurance, however, requires you to be "insurable." Waiting until you are older or sick to buy life insurance will make it significantly more expensive or even impossible to obtain.
- Failing to Coordinate with Social Security: Your annuity strategy should be built around your Social Security claiming strategy. For instance, you might use a "period certain" annuity to bridge the gap between age 62 and age 70, allowing you to delay Social Security and maximize your government benefit.
Frequently Asked Questions
Can I trade an annuity for life insurance or vice versa?
Under Section 1035 of the Internal Revenue Code, you can perform a tax-free exchange of one life insurance policy for another, or an annuity for another annuity. You can also exchange a life insurance policy for an annuity. However, you cannot exchange an annuity for a life insurance policy tax-free. If you move funds from an annuity to life insurance, the annuity gains will be taxed as ordinary income.
What happens if the insurance company goes bankrupt?
Insurance companies are regulated at the state level. Each state has a Guaranty Association that provides coverage to policyholders if an insurer becomes insolvent. Limits vary by state but typically provide up to $250,000 or $300,000 in protection for life insurance death benefits and annuity present values. It is wise to check the financial strength ratings from agencies like A.M. Best or S&P Global before purchasing.
Which is better for estate planning?
Life insurance is generally superior for estate planning because the death benefit passes to heirs income tax-free and can be structured (via an Irrevocable Life Insurance Trust) to stay out of your taxable estate. Annuity gains, conversely, are taxed as "Income in Respect of a Decedent" (IRD), meaning your heirs will likely owe income tax on the growth when they receive the proceeds.
Are annuities and life insurance protected from creditors?
In many states, both life insurance cash values and annuity contracts enjoy significant protection from creditors and lawsuits. This makes them attractive for professionals in high-liability fields, such as medicine or law. However, protection levels vary wildly by jurisdiction; for example, Florida offers robust protection, while other states may only protect a small dollar amount.
Can I use an annuity to pay for life insurance?
Yes, a strategy known as "pension maximization" involves taking a single-life annuity (higher payout) and using the extra income to buy a life insurance policy that replaces the income for a surviving spouse. This can sometimes provide a higher total benefit than a joint-and-survivor annuity option, though it requires careful health underwriting.
Final Recommendation
In 2026, the choice between an annuity and life insurance is rarely a binary one. If you have a family to protect, prioritize term life insurance first to cover your working years. Once your protection needs are met, evaluate your retirement income gap. If your projected Social Security and pension income won't cover your fixed expenses, a deferred annuity with an income rider can provide the peace of mind that a market downturn won't derail your retirement.
Before making a final decision, consult with a fiduciary financial advisor who can run a "gap analysis" on your retirement plan. This will show exactly where your vulnerabilities lie—whether it is a lack of legacy for your children or a lack of guaranteed income for your own "golden years."
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
