
Car insurance is a legally binding contract between a vehicle owner and an insurance company that protects against financial loss resulting from accidents, theft, or damage. In exchange for paying a regular premium, the insurer agrees to pay for specific losses as outlined in your policy, ensuring you meet legal requirements and financial obligations.
What is Car Insurance and Why Is It Necessary?
At its core, car insurance is a risk management tool. When you drive, you face the risk of causing damage to others or sustaining damage to your own property. Because the costs associated with medical bills, vehicle repairs, and legal liabilities can easily reach tens of thousands of dollars, most jurisdictions require drivers to carry a minimum level of financial responsibility. Car insurance fulfills this requirement by shifting the potential financial burden from the individual to the insurance provider.
In 2026, car insurance has evolved beyond simple "accident coverage." Modern policies are sophisticated legal instruments that incorporate digital tracking, real-time data analysis, and tiered protection levels. While the primary goal remains financial protection, the specific mechanisms—such as telematics and usage-based models—have become standard components of the industry. Having insurance is not just a legal hurdle; it is a critical safety net that prevents a single moment of negligence or bad luck from leading to personal bankruptcy.
The Legal Framework
Most countries and nearly every state in the U.S. mandate some form of liability insurance. This ensures that if you are at fault in an accident, the victims have a guaranteed source of funds for their recovery. Driving without insurance is typically classified as a serious offense, often resulting in heavy fines, license suspension, and in some cases, vehicle impoundment. Beyond the law, if you are financing or leasing your vehicle, your lender will almost certainly require "full coverage" to protect their investment until the loan is paid in full.
How Car Insurance Works: Premiums, Deductibles, and Limits
To understand car insurance, you must understand the three pillars of a policy: the premium, the deductible, and the coverage limits. These three factors interact to determine both the quality of your protection and the monthly cost of your plan.
The Premium: The Cost of Protection
The premium is the amount of money you pay (usually monthly, biannually, or annually) to keep your insurance policy active. In 2026, insurance companies use complex algorithms to determine your premium. These algorithms analyze your driving history, age, location, vehicle type, and even your credit-based insurance score. Essentially, the premium is the price the insurer charges to take on the risk associated with you as a driver. If you stop paying the premium, the policy lapses, leaving you uninsured and legally vulnerable.
The Deductible: Your Out-of-Pocket Share
The deductible is the specific amount you agree to pay out of your own pocket before the insurance company pays for a claim. For example, if you have a $500 deductible and sustain $2,500 in damages in a covered accident, you pay the first $500, and the insurer pays the remaining $2,000.
There is an inverse relationship between premiums and deductibles:
- Higher Deductibles: Choosing a $1,000 deductible usually results in a lower monthly premium because you are assuming more of the initial financial risk.
- Lower Deductibles: A $250 or $0 deductible results in a higher premium because the insurance company is responsible for almost the entire cost of any claim.
Coverage Limits: The Ceiling of Protection
Every policy has coverage limits, which represent the maximum amount the insurance company will pay for a single accident or claim. If an accident results in $100,000 of damage but your limit is capped at $50,000, you are personally responsible for the remaining $50,000. Understanding these limits is vital because "minimum legal coverage" often provides limits that are far too low to cover the costs of a multi-car pileup or serious medical injuries in 2026.

Core Types of Car Insurance Coverage
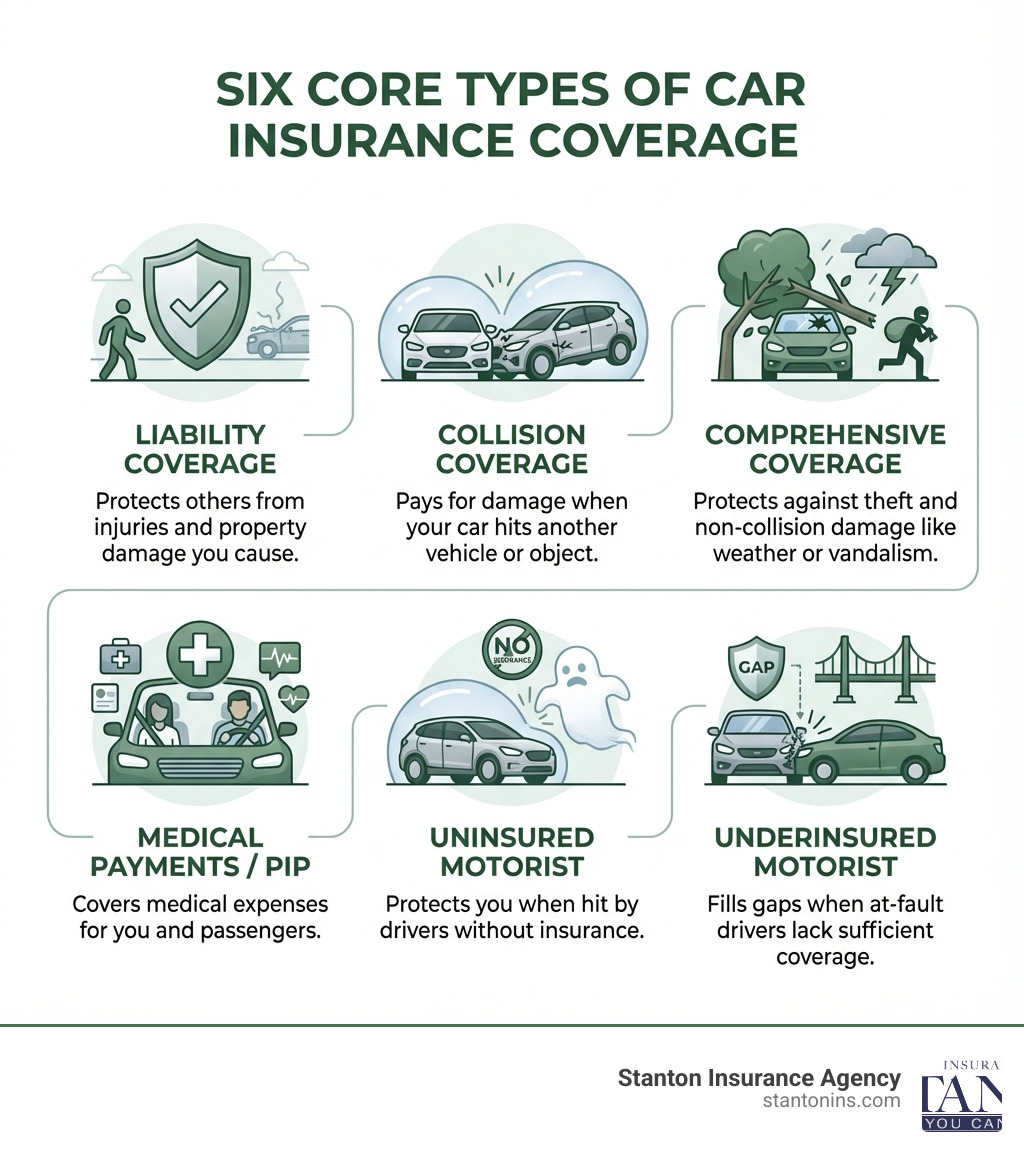
Car insurance is not a single "one-size-fits-all" product. It is a bundle of different types of coverage, each designed to protect against specific risks. A standard policy usually includes several of the following components.
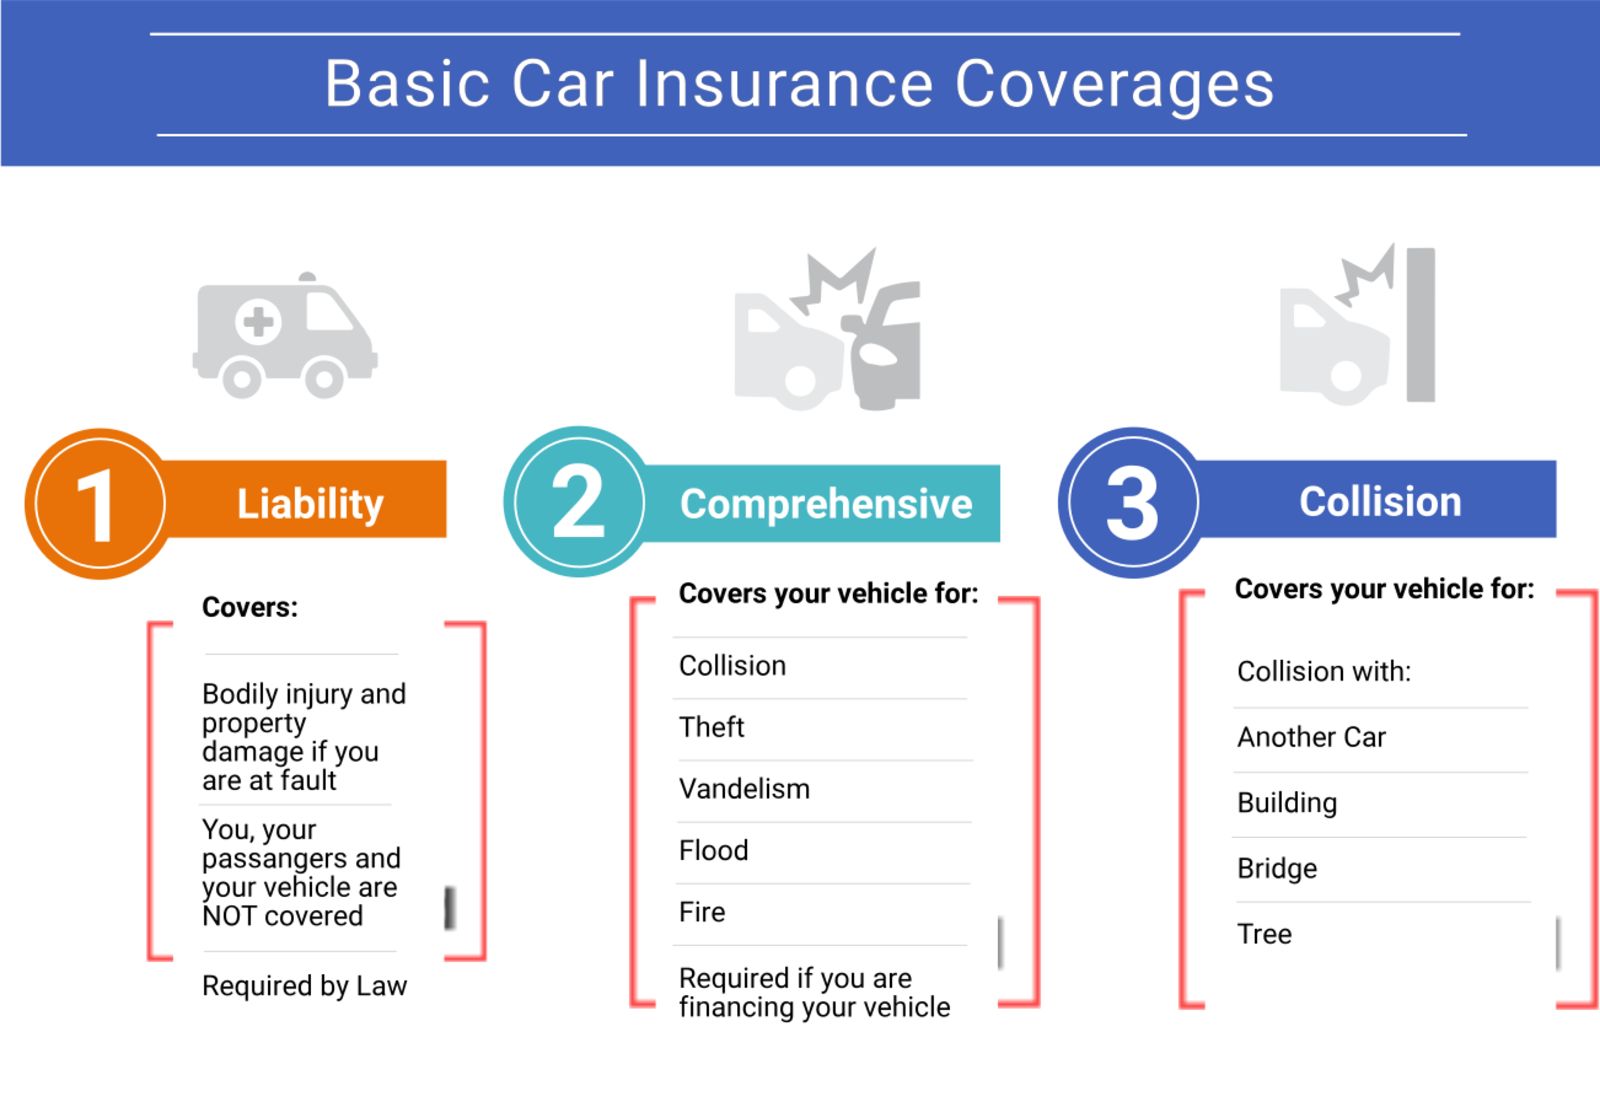
1. Liability Insurance (Mandatory)
Liability insurance is the foundation of most policies. It does not cover your own injuries or vehicle damage; instead, it pays for the injuries and property damage you cause to others. It is typically split into two parts:
- Bodily Injury Liability: Covers medical bills, lost wages, and legal fees for the other party.
- Property Damage Liability: Covers the repair or replacement of the other party’s vehicle or other property (like fences or storefronts).
2. Collision Insurance
Collision insurance covers damage to your own vehicle resulting from a collision with another car or an object (like a tree or a pole), regardless of who is at fault. While not required by law, it is essential for protecting the value of your car. If your car is "totaled"—meaning the repair costs exceed the car's value—collision insurance pays out the current market value of the vehicle, minus your deductible.
3. Comprehensive Insurance
Comprehensive insurance protects your vehicle from "acts of God" and other non-collision events. This includes theft, vandalism, fire, hail, falling objects, and collisions with animals (such as deer). In 2026, with the increasing frequency of extreme weather events, comprehensive coverage has become a priority for vehicle owners in many regions.
4. Personal Injury Protection (PIP) and Medical Payments
These coverages pay for medical expenses for you and your passengers after an accident, regardless of who was at fault. PIP is often more expansive, covering not just medical bills but also lost wages and funeral expenses. In "no-fault" insurance states, PIP is usually a mandatory requirement.
5. Uninsured and Underinsured Motorist Coverage
Despite legal requirements, a significant number of drivers still operate vehicles without insurance or with insufficient limits. This coverage protects you if you are hit by a driver who cannot pay for the damages they caused. It also applies to hit-and-run accidents where the other driver cannot be identified.
Comparing Coverage Types at a Glance
The following table provides a quick reference for the most common types of car insurance available in 2026.
| Coverage Type | Is it Mandatory? | What Does it Cover? | Who Does it Protect? |
|---|---|---|---|
| Liability | Yes (Most states/nations) | Damage/injuries you cause to others. | Other drivers and pedestrians. |
| Collision | Only if vehicle is financed | Damage to your car from a crash. | You and your vehicle value. |
| Comprehensive | Only if vehicle is financed | Theft, fire, weather, and animals. | Your vehicle against non-crash risks. |
| PIP / MedPay | Depends on jurisdiction | Medical bills for you/passengers. | You and your passengers. |
| Uninsured Motorist | Often mandatory | Accidents where the at-fault driver lacks insurance. | You and your passengers. |
Factors That Influence Your Insurance Rates in 2026
In 2026, insurance pricing has become more personalized than ever before. While traditional factors still apply, the integration of technology has introduced new variables into the premium equation.
Telematics and Usage-Based Insurance (UBI)
By 2026, most major insurers offer (or require) a telematics program. This involves using a smartphone app or a plug-in device to monitor your driving habits in real-time. Factors tracked include:
- Hard Braking: Frequent sudden stops indicate aggressive driving.
- Speeding: Consistently driving above the limit increases risk profiles.
- Time of Day: Driving late at night is statistically more dangerous.
- Mileage: The less you drive, the lower your statistical chance of an accident.
Drivers who demonstrate safe habits via telematics can often see significant discounts, while high-risk drivers may see their rates increase.
Vehicle Technology and Repair Costs
The complexity of vehicles in 2026 significantly impacts insurance costs. Modern cars are equipped with Advanced Driver Assistance Systems (ADAS), such as lane-keep assist and automated braking. While these systems reduce the frequency of accidents, they increase the cost of repairs. A simple fender-bender that used to cost $500 for a bumper replacement now might cost $3,000 because of the sensors and cameras embedded in the plastic. Consequently, vehicles with high-tech components often carry higher comprehensive and collision premiums.
Demographic and Geographic Data
Your location remains one of the most influential factors. If you live in an area with high crime rates or high traffic density, your risk of theft or collision is higher. Additionally, insurers look at your age and driving experience. Statistically, teen drivers and very elderly drivers are involved in more accidents, leading to higher premiums for these age groups.
The Claims Process: What to Do After an Accident
Understanding how insurance works is most critical when you actually need to use it. The claims process is the sequence of events that occurs from the moment of the accident until the final payment is made.
- Safety and Documentation: Ensure everyone is safe and call emergency services if necessary. Document the scene with photos and exchange information with other drivers.
- Filing the Claim: In 2026, most claims are filed through mobile apps. You will provide photos of the damage, the location, and a description of the event.
- Investigation and Adjusting: The insurance company assigns an "adjuster" to review the case. They will examine the damage, review police reports, and determine who was at fault.
- The Estimate: The insurer provides an estimate of the repair costs. You may be required to take the car to a certified repair shop within the insurer's network.
- Settlement: Once the repairs are completed (or the car is declared a total loss), the insurer issues payment. They will subtract your deductible from the final payout.
It is important to note that filing a claim, especially an at-fault claim, will likely lead to an increase in your premiums during your next renewal period. Many drivers choose to pay for minor "fender benders" out of pocket to avoid these long-term rate hikes.
Common Mistakes to Avoid When Buying Car Insurance
Many consumers focus solely on finding the lowest price, which can lead to significant financial gaps. Avoiding these common pitfalls will ensure you are truly protected.
- Buying Only the Minimum Legal Limits: State minimums are often outdated. For example, a $25,000 property damage limit is insufficient if you hit a modern electric vehicle or cause a multi-car accident.
- Misrepresenting Your Annual Mileage: While it might save you a few dollars on your premium, lying about how much you drive can be considered insurance fraud and may result in a denied claim.
- Ignoring Gaps in Coverage: If you owe more on your car loan than the car is worth, you need Gap Insurance. Standard collision insurance only pays the market value, leaving you responsible for the remainder of the loan if the car is totaled.
- Neglecting to Shop Around Yearly: The insurance market is highly competitive. Rates change frequently based on an insurer's current "appetite" for risk. Comparing quotes annually is the most effective way to manage costs.
Frequently Asked Questions
What is "Full Coverage" car insurance?
"Full coverage" is not a specific type of insurance but a term used to describe a policy that includes Liability, Collision, and Comprehensive insurance. It provides the broadest level of protection, covering damage to others, damage to your own vehicle, and non-collision events like theft or weather damage.
How does a "No-Fault" insurance state work?
In a no-fault state, your own insurance company pays for your medical bills and lost wages (up to a certain limit) regardless of who caused the accident. The goal of this system is to reduce the number of lawsuits and speed up the payment of medical claims. However, you can still be sued for "pain and suffering" if the injuries are severe.
Will my car insurance cover me if I use my car for work or ride-sharing?
Standard personal auto policies typically exclude coverage for commercial use, including ride-sharing (like Uber or Lyft) or delivery services. If you use your vehicle for these purposes, you must add a "ride-share endorsement" or purchase a commercial policy to ensure you are covered while the app is active.
Can my insurance company cancel my policy at any time?
Insurers generally cannot cancel a policy that has been in effect for more than 60 days except for specific reasons, such as non-payment of premiums, discovery of fraud or material misrepresentation, or a substantial increase in the risk insured (like a driver's license suspension). However, they can choose "non-renewal" at the end of your policy term for almost any reason.
Does car insurance cover the contents inside my car?
Generally, no. Car insurance covers the vehicle itself and its factory-installed parts. Personal items stolen from your car, such as a laptop or a phone, are typically covered by your homeowners or renters insurance, not your auto policy.
Final Recommendation
To ensure you are properly protected in 2026, do not settle for the cheapest policy available. Start by assessing the total value of your assets; your liability limits should be high enough to protect your savings and home from a potential lawsuit. If your vehicle is less than ten years old, maintaining collision and comprehensive coverage is highly recommended. Finally, take advantage of telematics programs if you are a safe driver, as this is the most direct way to lower your premiums in the current market. Review your policy every 12 months to ensure your coverage still aligns with your vehicle's value and your lifestyle.
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
