Securing an $8,000 car loan requires analyzing how interest rates, loan terms, and down payments combine to determine your monthly financial obligation. Typically, a loan of this size results in a monthly payment between $150 and $250, depending on your credit profile and whether you choose a 36-month or 48-month repayment schedule, assuming standard lending terms.
When shopping for an affordable vehicle, the purchase price is only the starting point of the financial equation. While an $8,000 auto loan sits on the lower end of the borrowing spectrum—often utilized for dependable used cars, private-party sales, or secondary vehicles—understanding the mechanics of the debt prevents unexpected costs. Borrowers frequently focus entirely on the sticker price, overlooking how loan structures, interest rates, and loan terms affect overall affordability. Evaluating these elements step by step ensures you select a financing structure that fits your monthly budget without accumulating unnecessary interest charges.
The Anatomy of an Auto Loan: Principal, Interest, and Term
Every auto loan consists of three foundational components: the principal, the interest rate (expressed as an Annual Percentage Rate, or APR), and the loan term. Understanding how these factors interact is essential for managing your debt effectively.
The Principal Balance
The principal is the actual amount of money you borrow to purchase the vehicle. In this case, the baseline principal is $8,000. However, the financed amount can fluctuate depending on your transaction details. If you make a down payment or trade in an existing vehicle, the financed principal decreases. Conversely, if you roll dealership fees, documentation charges, state taxes, and registration costs into the loan, your starting principal will increase beyond $8,000. Lenders calculate your monthly obligation based on this final financed total.
Interest Rates and APR
The interest rate represents the cost of borrowing money, while the APR encompasses both the interest rate and any mandatory lender fees, expressed as an annualized percentage. Your APR is determined primarily by your credit score, credit history, debt-to-income ratio, and economic conditions.
- Borrowers with prime credit scores (typically 740 and above) secure the lowest available rates.
- Borrowers with non-prime or subprime credit face higher rates, which significantly increases the total cost of financing.
The Loan Term
The loan term is the designated duration over which you agree to repay the loan, usually measured in months. Common terms for used car loans range from 24 to 60 months. While a longer term reduces your monthly payment, it increases the total interest paid over the life of the loan. Conversely, a shorter term requires a higher monthly payment but saves money on total interest costs.
How Loan Terms and Interest Rates Shape Monthly Payments
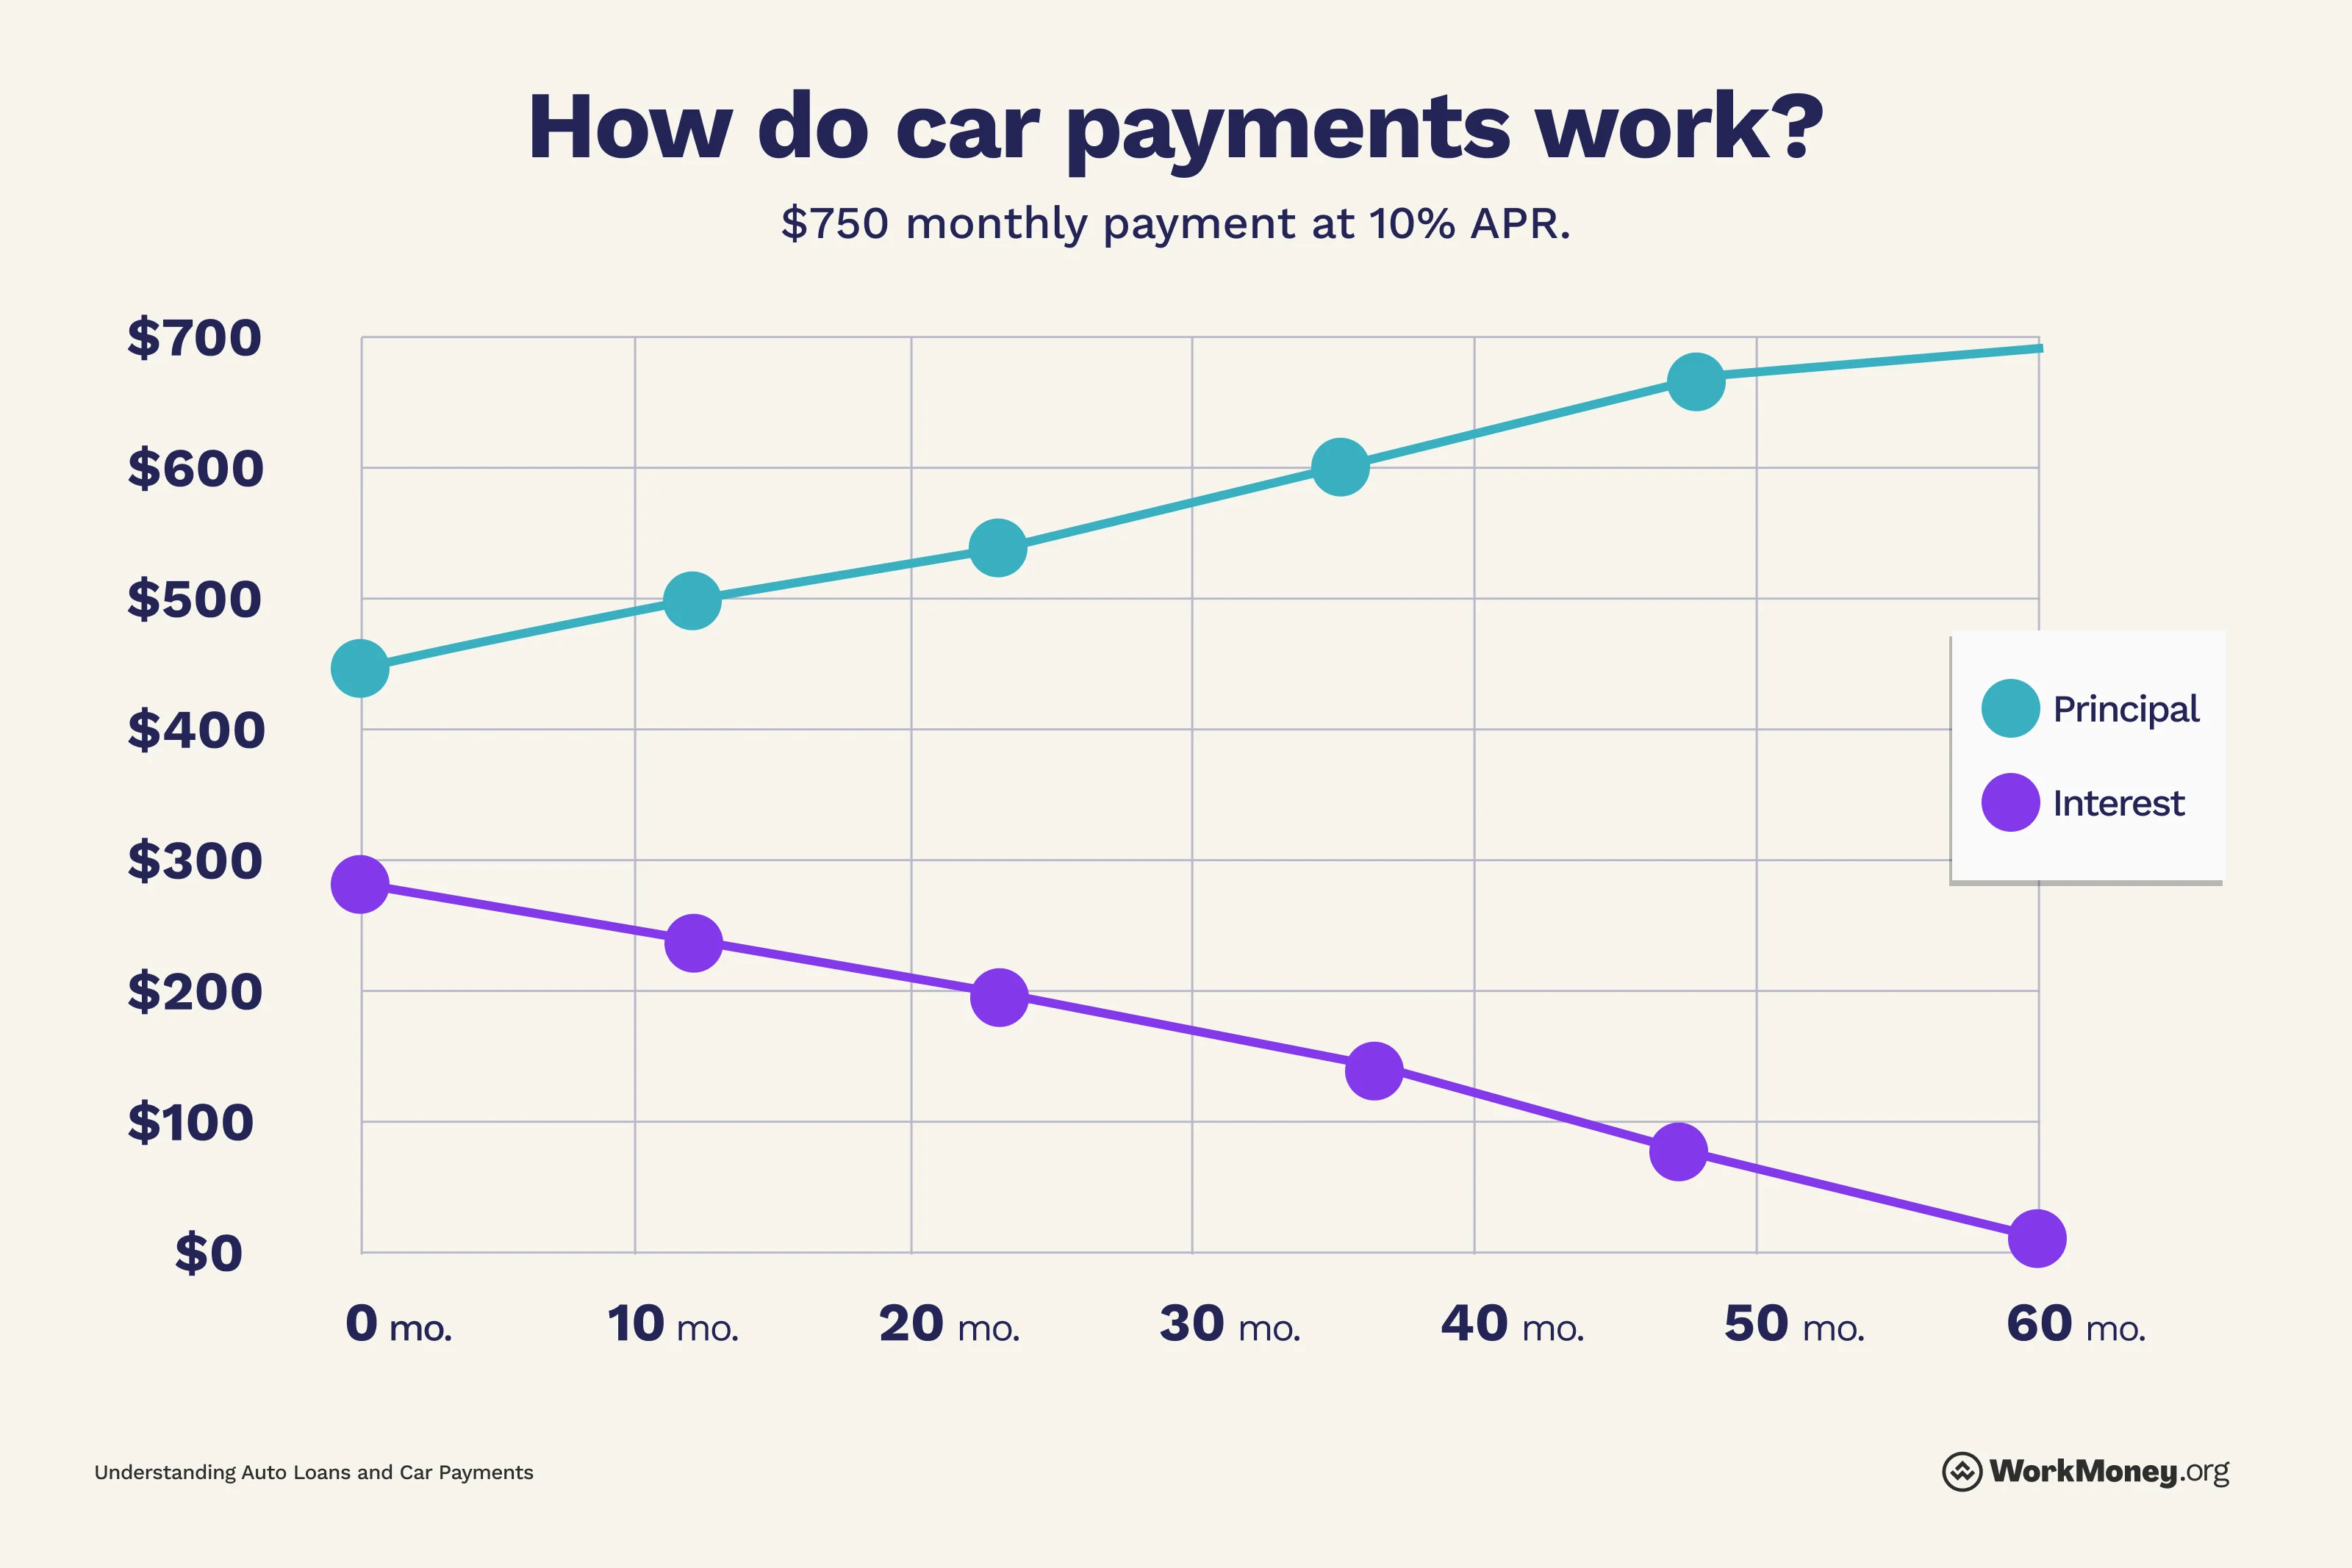
To understand what an $8,000 car loan looks like in practice, consider how mathematical amortization applies across different scenarios. Amortization is the process where each fixed monthly payment is split between paying off the remaining principal and covering the interest accrued that month.
At the beginning of a loan term, a larger portion of your monthly payment goes toward interest. As the principal balance decreases, less interest accrues, and a larger portion of your payment reduces the principal.
Estimated Monthly Payment Scenarios
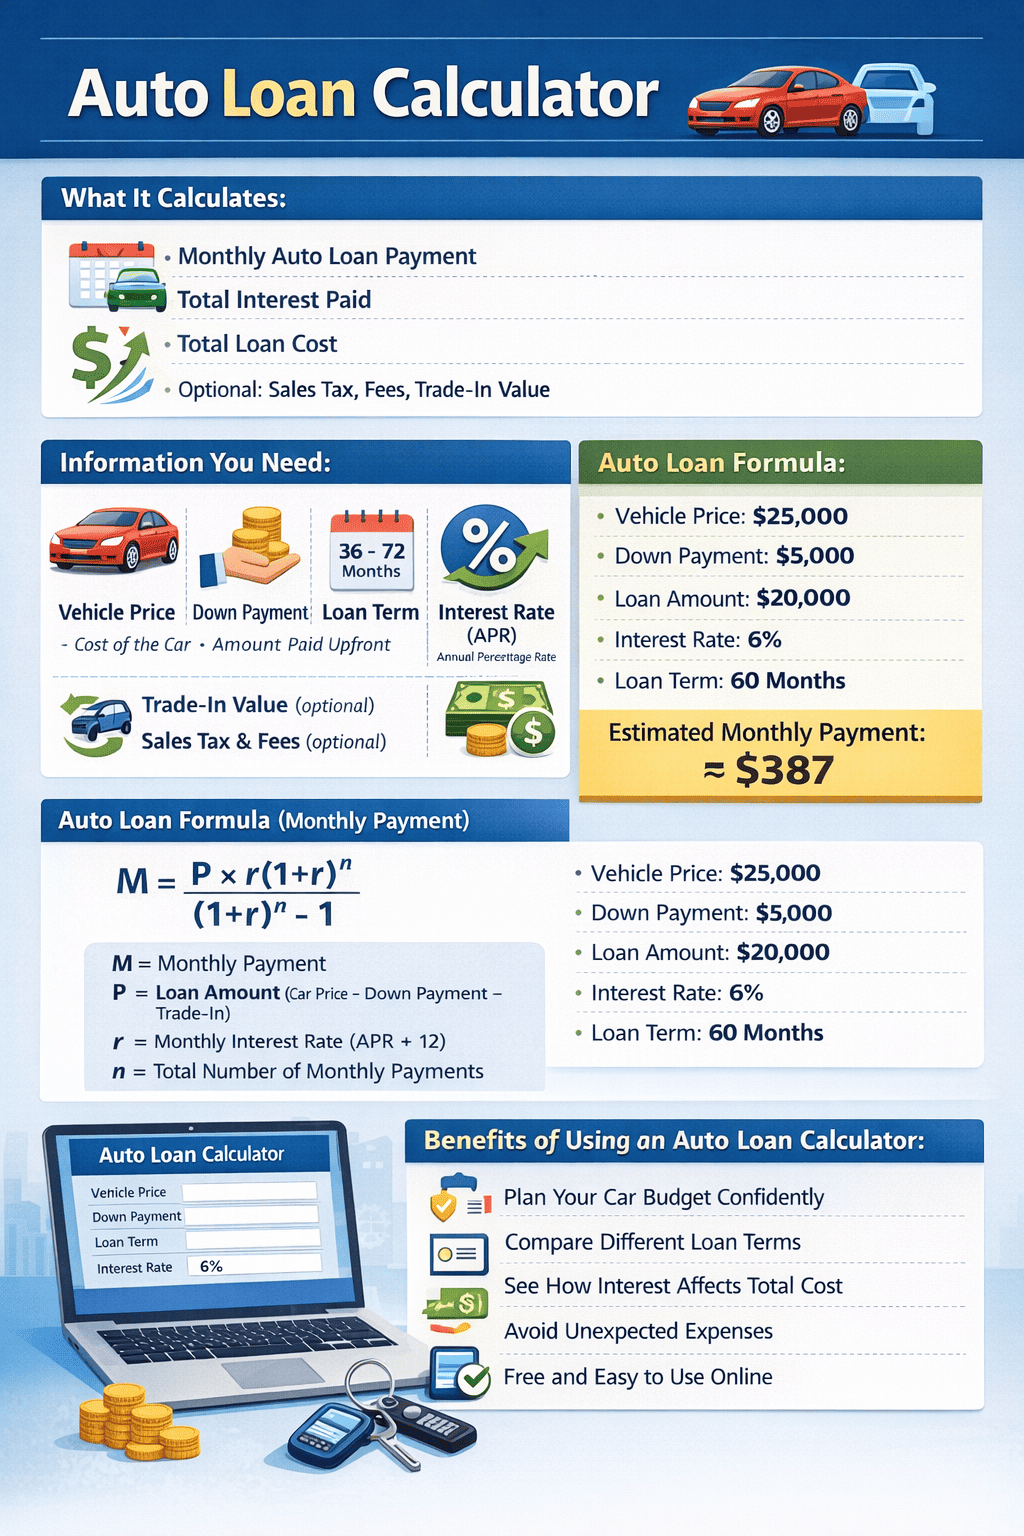
The table below outlines estimated monthly payments and total interest costs for an $8,000 principal balance across various terms and interest rates, assuming no additional fees are rolled into the financing.
| Loan Term (Months) | Interest Rate (APR) | Estimated Monthly Payment | Total Interest Paid | Total Cost of Loan |
|---|---|---|---|---|
| 36 | 5.0% | $239.75 | $631.11 | $8,631.11 |
| 36 | 10.0% | $258.14 | $1,293.07 | $9,293.07 |
| 48 | 6.0% | $187.94 | $1,221.14 | $9,221.14 |
| 48 | 12.0% | $210.67 | $2,512.16 | $10,512.16 |
| 60 | 7.0% | $158.35 | $1,501.19 | $9,501.19 |
| 60 | 14.0% | $186.07 | $3,164.20 | $11,164.20 |
As demonstrated by the figures, stretching an $8,000 loan over 60 months at a double-digit interest rate increases the total cost of the vehicle substantially. Minimizing the loan term and securing a competitive interest rate protects your financial resources.
Additional Costs Beyond the Loan Principal
When calculating the true cost of an $8,000 car loan, you must account for expenses that occur outside the monthly loan statement. Failing to budget for these auxiliary costs can strain your personal finances.
Sales Tax, Title, and Registration Fees
State and local governments levy taxes and fees on vehicle purchases. Depending on your jurisdiction, sales tax can add hundreds of dollars to the transaction. While some buyers pay these fees out of pocket at the time of purchase, others finance them. Financing taxes increases your loan balance, pushing the principal above the vehicle's purchase price.
Comprehensive Auto Insurance
Lenders require borrowers to maintain comprehensive and collision insurance coverage until the loan is paid in full. If you purchase an older, lower-priced vehicle using an $8,000 loan, the cost of mandatory full-coverage insurance can sometimes rival or exceed your monthly loan payment. Request insurance quotes for specific vehicle makes and models before finalizing your loan agreement.
Maintenance and Repairs
An $8,000 vehicle is often out of its factory warranty. Setting aside an emergency repair fund is critical. Unexpected mechanical failures—such as transmission issues, brake replacements, or electrical repairs—must be paid out of pocket while you are simultaneously servicing your monthly car loan.
Comparing Lending Options for Smaller Loan Amounts
Not all lenders actively seek out smaller auto loans. Because processing an $8,000 loan requires the same administrative overhead as a $30,000 loan, some financial institutions set minimum loan amounts, often starting at $5,000 or $10,000. Researching your options ensures you find a lender equipped to handle a modest financing request.
Credit Unions
Credit unions frequently offer favorable terms, lower interest rates, and fewer administrative fees for auto loans compared to major commercial banks. Because credit unions operate as member-owned non-profits, they are often more willing to work with borrowers seeking smaller loan amounts. Joining a local or online credit union prior to shopping can yield better financing terms.
Traditional Banks
Large national banks provide streamlined application processes and digital account management. However, they may impose strict minimum loan limits or higher interest rates for used vehicle purchases under $10,000. Reviewing a bank's lending criteria before submitting a formal application prevents unnecessary hard inquiries on your credit report.
Dealership Financing (Indirect Lenders)
Dealerships partner with a network of financial institutions to offer financing on-site. While convenient, dealership financing sometimes includes dealer markups, where the finance manager adds percentage points to the base interest rate approved by the lender. Always compare outside pre-approvals from a credit union or bank before accepting dealership financing terms.
Steps to Secure and Manage Your Auto Loan
Approaching the borrowing process systematically minimizes stress and prevents unfavorable loan terms. Follow these steps when preparing to finance an $8,000 vehicle:
- Check Your Credit Score: Review your credit report and score to understand what interest rates you qualify for. Correct any reporting errors before applying for financing.
- Obtain Pre-Approval: Secure financing pre-approval from a bank or credit union. This establishes a baseline interest rate and maximum loan amount, giving you leverage during vehicle negotiations.
- Calculate Total Affordability: Factor in your monthly loan payment, insurance premiums, fuel costs, and projected maintenance to ensure the total vehicle budget fits comfortably within your monthly income.
- Review the Loan Agreement: Read the promissory note carefully before signing. Verify the APR, loan term, monthly payment due date, and confirm there are no prepayment penalties if you decide to pay the loan off early.
- Set Up Automated Payments: Enroll in automatic monthly withdrawals to ensure payments are never late, protecting your credit score from delinquency marks.
Common Pitfalls to Avoid
Navigating a car loan requires vigilance against terms and practices that increase your financial burden unnecessarily.
Ignoring Prepayment Penalties
Some subprime lenders include prepayment penalties in their contracts—fees charged if you pay off your loan ahead of schedule. Avoid lenders with these clauses so you retain the freedom to eliminate your debt early without financial penalty.
Rolling Negative Equity
If you are trading in a vehicle that is worth less than what you currently owe on it (negative equity), rolling that leftover balance into your new $8,000 loan creates an upside-down financing situation. This significantly increases your starting principal and raises your risk of default.
Focusing Solely on the Monthly Payment
Predatory lenders often secure business by asking, "What monthly payment can you afford?" They then manipulate the loan term—stretching it out to 72 or 84 months—to hit that target payment while concealing a high interest rate that inflates the total cost of the vehicle. Always evaluate the total purchase price and interest accumulation rather than the monthly payment alone.
Frequently Asked Questions
Can I get an auto loan for only $8,000?
Yes, many credit unions and select banks offer auto loans for $8,000. However, some traditional financial institutions enforce minimum loan amounts of $5,000 or $10,000. Checking a lender's minimum financing thresholds before applying prevents wasted time.
How does my credit score affect an $8,000 car loan?
Your credit score dictates your APR. A higher credit score qualifies you for lower interest rates, reducing your monthly payment and total interest paid. A lower credit score results in higher interest rates, which increases your overall borrowing costs.
Is it better to choose a 36-month or 48-month term for a small loan?
A 36-month term is generally better if your monthly budget allows for it, as it reduces total interest charges and helps you build equity faster. A 48-month term offers a lower monthly payment, but increases the overall cost of the loan.
Can I pay off my $8,000 car loan early?
In most cases, yes. Standard auto loans do not penalize borrowers for making extra principal payments or paying off the balance in full early. Always verify that your specific loan agreement does not contain a prepayment penalty clause.
What documents do I need to apply for an auto loan?
Lenders typically require proof of identity (government-issued ID), proof of income (recent pay stubs or tax returns), proof of residence (utility bill or lease agreement), and details regarding the vehicle you intend to purchase, such as the purchase order or vehicle identification number (VIN).
Next Actions
To move forward effectively, request a copy of your credit report to verify your financial standing, and apply for pre-approval through a local credit union or online bank. Comparing pre-approved offers establishes a competitive baseline, empowering you to secure the most favorable terms for your $8,000 car loan.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
