When you borrow a friend’s vehicle or operate a car you do not own, the primary rule of insurance is that coverage typically follows the vehicle rather than the driver. In most standard insurance scenarios, if you are a permissive user—meaning you have the owner's explicit or implicit permission to drive the car—the owner’s insurance policy acts as the primary source of protection should an accident occur.
The Foundation of "Insurance Follows the Car"
The principle that insurance follows the vehicle is a cornerstone of the automotive insurance industry in the United States and many other jurisdictions. This means that if you are involved in a collision while driving someone else’s car, that owner’s insurance policy is almost always the first line of defense. The owner's liability coverage will generally pay for damages to the other party’s vehicle and their medical bills, up to the limits specified in the owner's policy.
However, this does not mean the driver is entirely removed from the equation. If the owner’s policy limits are insufficient to cover the total damages—often referred to as an "at-fault" excess scenario—your own auto insurance may act as "secondary" or "excess" coverage. Your policy fills the gap, provided your policy terms do not explicitly exclude coverage for non-owned vehicles.
Understanding this dynamic requires a shift in how you view "your" insurance. Most personal auto policies are designed to cover the named insured and members of their household, but they also extend "temporary substitute" or "non-owned" coverage when you operate a vehicle on a sporadic, non-regular basis.
Determining Coverage Priority
In the event of an accident, claims adjusters follow a specific hierarchy to determine which policy pays for what. This order of operations is essential for mitigating personal financial risk:
- The Vehicle Owner’s Liability Coverage: This is the primary policy. It pays for damages you cause to others, including property damage and bodily injury.
- The Vehicle Owner’s Collision Coverage: This pays for the repairs to the car you were driving. Note that the owner will be responsible for the deductible associated with their policy, regardless of who was driving.
- The Driver’s Insurance (Secondary/Excess): If the damage exceeds the owner’s policy limits, your own liability insurance may step in to cover the remaining balance.
- The Driver’s Collision Coverage: If the owner has no collision coverage, or if their coverage is insufficient, your policy might cover the repairs to the vehicle, though this is highly dependent on your specific policy language regarding "non-owned" vehicles.
The Crucial Role of Permissive Use
"Permissive use" is a legal and contractual term that refers to whether the driver had the owner's authorization to operate the vehicle. Insurance companies categorize permissive users into two distinct groups:
- Named Insureds/Household Members: If you live with the vehicle owner and are not listed on their policy, many insurers will deny coverage. Insurance companies require all licensed residents in a household to be disclosed; failing to list a household member is often considered a material misrepresentation.
- Occasional/Permissive Users: If you are a friend, neighbor, or extended family member who does not live in the household, you are generally considered a permissive user. As long as you have the owner’s permission, you are typically covered under the owner’s policy.
Important Exception: If you take a car without permission—even if you are a family member—the owner's insurance may classify this as a non-covered incident. In cases involving theft or unauthorized use, the insurance company may deny the claim entirely, leaving you personally liable for all damages.
Comparing Coverage Scenarios
| Scenario | Primary Payer | Secondary Payer |
|---|---|---|
| Permissive friend driving | Owner's Policy | Driver's Policy (Excess) |
| Non-permissive driver | None (Potential Denial) | Driver's Policy (If applicable) |
| Unlisted household member | Usually Denied | Driver's Policy (Rare) |
| Rental car (personal use) | Rental Co/Owner Policy | Driver's Policy |
When Your Own Insurance Matters
There are instances where the owner’s policy is not enough or is nonexistent. If you drive someone else’s car frequently—such as a vehicle belonging to a significant other or a roommate—your insurance company may view this as "regular use" of a non-owned vehicle.
Standard policies often contain a "regular use exclusion." This clause is designed to prevent consumers from insuring one car while driving another, uninsured car on a daily basis without paying premiums for it. If you drive a specific car owned by someone else multiple times a week, your own insurance company might deny any claim you file because that vehicle was not listed on your policy. If you find yourself in this situation, you must contact your agent to discuss adding yourself as a driver to the owner’s policy.
Financial Implications and Deductibles
While the owner’s insurance may cover the bulk of the liability, the financial impact on the owner can be severe. If you are in an accident while driving their car:
- The Deductible: The owner is responsible for the deductible (the out-of-pocket amount before insurance kicks in). If the owner has a $1,000 deductible, they will have to pay that amount to the repair shop, regardless of who caused the accident.
- Premium Hikes: Most insurance companies utilize "at-fault" accident surcharges. Because the accident is tied to the vehicle's policy, the owner’s premiums will likely increase upon renewal, even though you were the one behind the wheel.
- Liability Exposure: If the damages exceed the owner's policy limits and you have no secondary insurance, you could be held personally liable for the remaining costs, leading to potential litigation.
Steps to Take Before Borrowing a Vehicle
To ensure you are protected, follow these professional recommendations before you get behind the wheel of another person’s car:
- Verify the Coverage: Ask the owner, "Does your policy cover other drivers?" Do not assume that because they have "full coverage," you are automatically protected.
- Know the Limits: If the vehicle owner carries only the state-mandated minimum liability insurance, the coverage may be inadequate for a serious accident. If you have higher limits on your own policy, consider if the risk is worth it.
- Confirm Deductibles: If you are borrowing the car for an extended trip or period, clarify who will cover the deductible if an accident occurs. It is common practice for the driver to agree to cover the owner’s deductible in the event of a mishap.
- Carry Your Proof of Insurance: Always have your own insurance identification card with you. If an accident occurs, you will need to provide both the owner’s insurance information and your own to the authorities and the other parties involved.
Frequently Asked Questions
Does my insurance cover me if I rent a car? Yes, in most cases, your personal auto insurance policy extends to rental cars as long as you are using them for personal, non-business purposes. However, you should confirm with your provider if your specific policy includes "non-owned" rental coverage before declining the rental company's damage waiver.
What happens if the owner doesn't have insurance? If the vehicle owner is uninsured, you are in a high-risk situation. If you cause an accident, you will be personally liable for the damages. If you are involved in an accident caused by another driver, your own "Uninsured/Underinsured Motorist" (UM/UIM) coverage may protect you, but this varies by state and policy.
Will my insurance rates go up if I have an accident in someone else's car? Yes, it is possible. If your insurance company pays out a claim—either as secondary coverage or under your own policy—that incident may be tied to your driving record, potentially leading to increased premiums at renewal.
Can I get "non-owner" insurance? Yes. If you do not own a car but drive frequently, you can purchase a "non-owner" auto insurance policy. This provides liability coverage when you drive cars you do not own and serves as a safety net if the owner’s policy is inadequate.
What is the difference between permissive and non-permissive use regarding theft? If you drive a car without the owner’s consent, it is generally classified as non-permissive. In legal and insurance terms, this can be considered unauthorized use or theft. Most standard insurance policies will exclude coverage for damages incurred while the vehicle is being used without the owner's permission.
Final Recommendation: Due Diligence
The best practice when borrowing a vehicle is to treat the vehicle as if it were your own regarding responsibility. Before accepting the keys, confirm that the owner maintains an active, valid insurance policy. If you find yourself using someone else's vehicle on a recurring basis, prioritize speaking with an insurance agent to discuss whether you should be formally added to their policy or if you should obtain non-owner insurance to bridge the liability gap.
In the event of an accident, document the scene, collect insurance information from all parties, and contact the owner immediately. Insurance companies prioritize clear, factual reporting; ensuring you have accurate policy information on hand will streamline the claims process and minimize potential disputes.
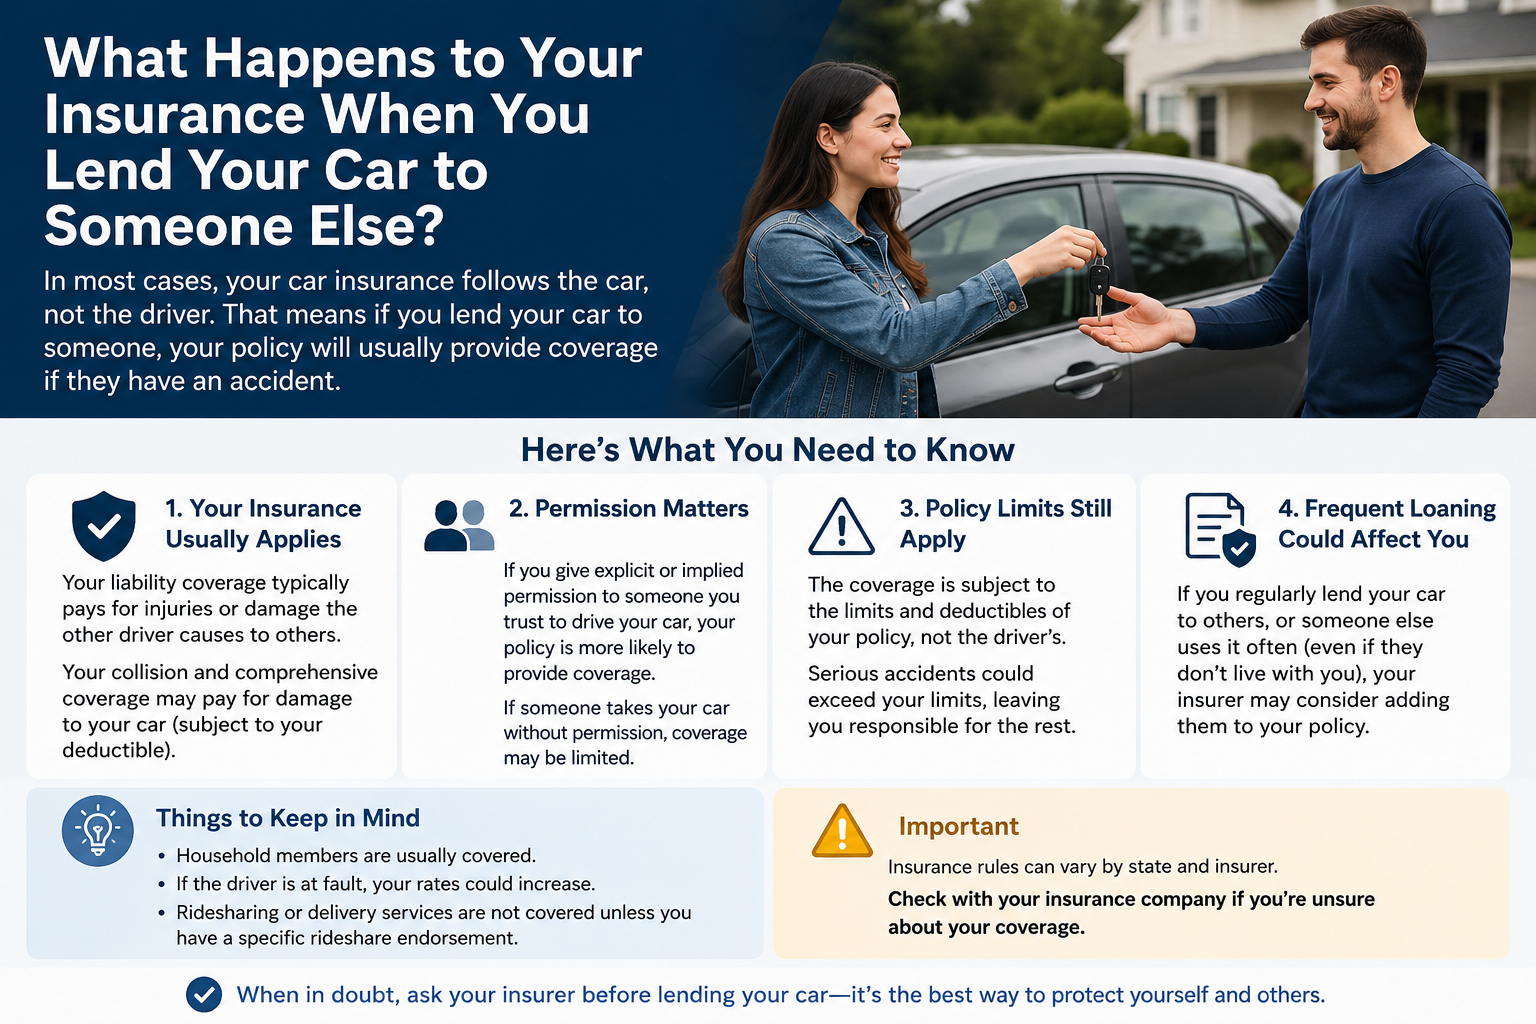
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
