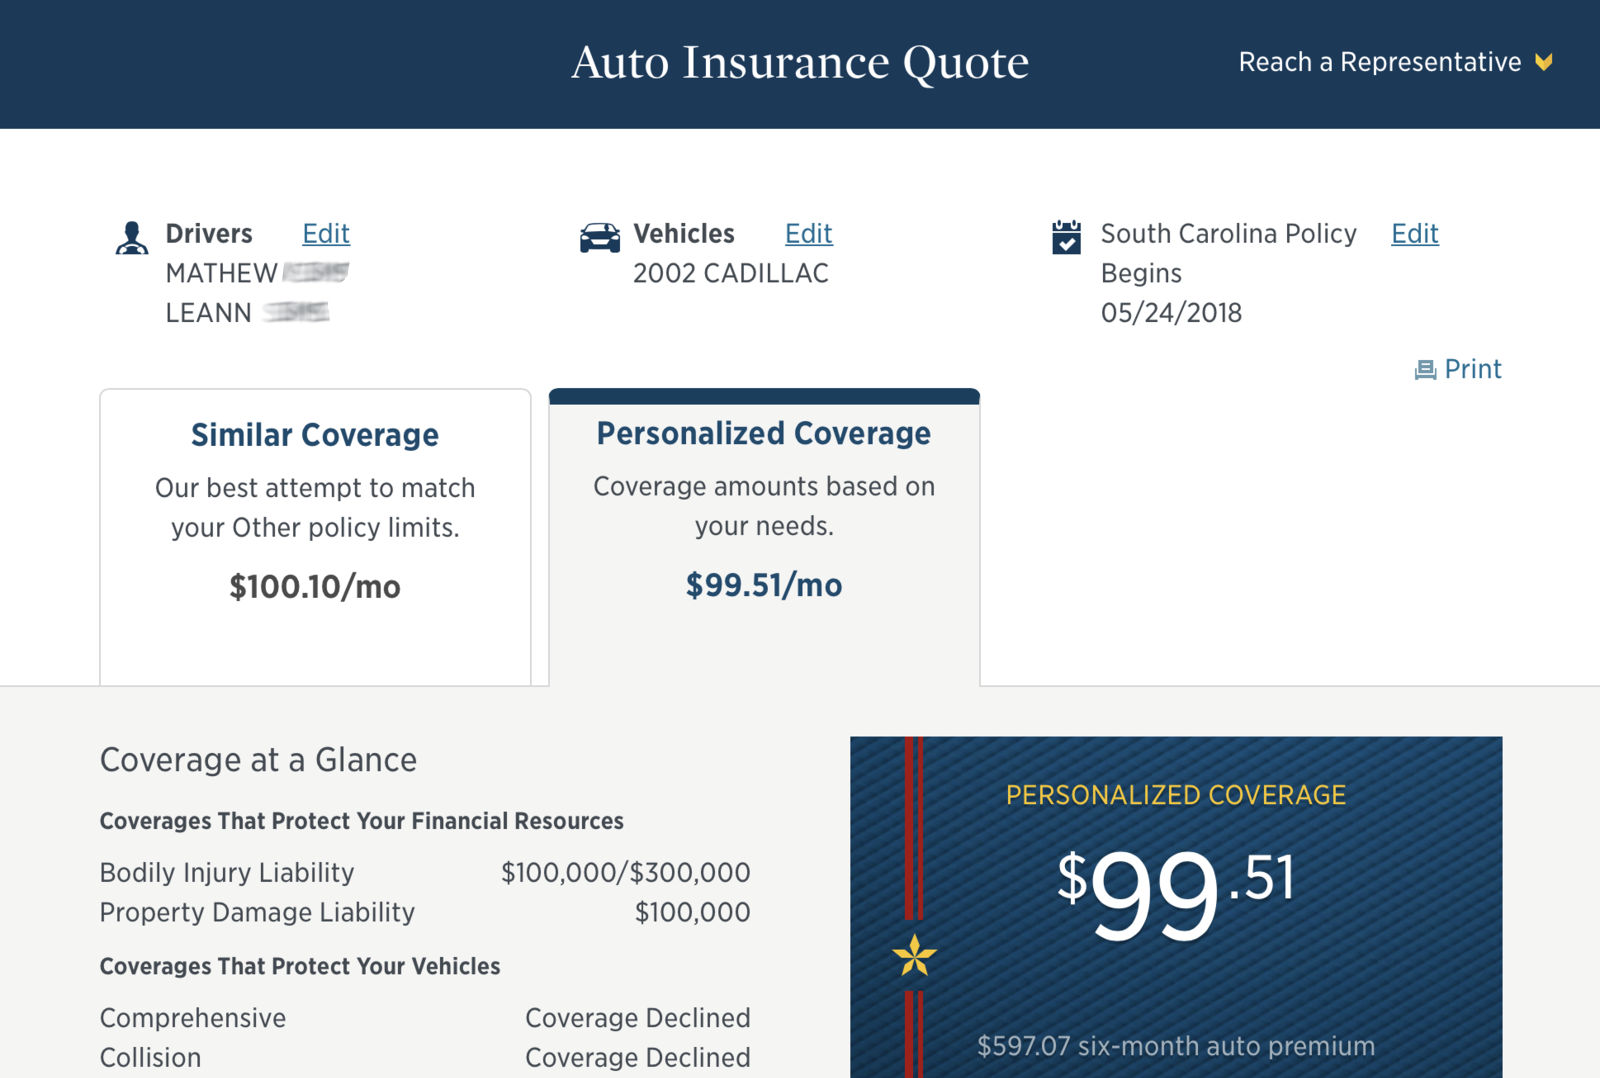
Securing insurance quotes in New Jersey requires understanding state-specific coverage mandates, utilizing online comparison tools, gathering precise personal and asset data, and evaluating quotes based on deductible levels, coverage limits, and carrier financial strength.
Navigating the insurance market in New Jersey can feel complex due to state-specific regulations, dense traffic patterns, weather vulnerabilities, and a competitive landscape featuring numerous regional and national carriers. Whether you are shopping for auto, homeowners, renters, or life insurance, obtaining accurate and favorable quotes requires a structured approach. This guide examines the precise steps, legal requirements, and strategic considerations necessary to successfully gather, compare, and select insurance quotes in the Garden State as of 2026.
Understanding the New Jersey Insurance Landscape
Before requesting quotes, it is essential to understand how insurance markets operate within New Jersey. The state regulates insurance rates and consumer protections through the New Jersey Department of Banking and Insurance (DOBI). DOBI oversees admitted carriers operating within the state, ensuring they maintain adequate capital reserves to pay claims and adhere to state-mandated coverage minimums.
Unlike some states with open rate filing systems, New Jersey utilizes a prior-approval rating system for auto insurance and certain lines of property insurance. This means insurers must file their rate changes with DOBI and receive approval before implementing them. Consequently, rate variations between carriers can be substantial, making active comparison shopping one of the most effective ways for consumers to control their premium costs. Furthermore, New Jersey has unique tort threshold options for auto insurance, which directly influence how quotes are structured and priced.
Identifying Your Insurance Needs and Coverage Minimums
Insurance is not a one-size-fits-all product. Before requesting quotes, you must determine what types of insurance you need and the appropriate coverage limits to protect your financial well-being. Buying only the state minimum required coverage often leaves significant financial exposure after a major accident or property loss.
Auto Insurance Requirements
New Jersey law mandates that every registered vehicle carry specific minimum coverages. However, relying solely on these minimums can be financially risky. The mandatory components include:
- Liability Coverage: Covers bodily injury and property damage you cause to others. New Jersey requires a minimum of $25,000 for injury to one person, $50,000 for injury to multiple people in an accident, and $25,000 for property damage (often written as 25/50/25).
- Personal Injury Protection (PIP): New Jersey is a no-fault state, meaning your own insurance pays your medical bills regardless of who caused the accident. State law requires a minimum of $15,000 in PIP coverage, though higher limits up to $250,000 are available and recommended.
- Uninsured/Underinsured Motorist Coverage (UM/UIM): Protects you if you are hit by a driver who has no insurance or insufficient limits to cover your damages.
Homeowners and Renters Insurance
While mortgage lenders universally require homeowners insurance, renters insurance is optional but highly recommended to protect personal property and liability. When seeking quotes for property insurance, you must decide between actual cash value (ACV)—which subtracts depreciation from your payout—and replacement cost coverage, which pays the actual cost to rebuild or replace items brand new.
Gathering Required Documentation and Information
To receive accurate insurance quotes rather than rough estimates that change later, you must assemble a comprehensive set of personal and asset data before contacting agents or filling out online quote forms. Insurance underwriting relies heavily on risk algorithms that analyze exact details.
| Insurance Type | Required Information & Documents |
|---|---|
| Auto Insurance | Driver’s license numbers for all household drivers, Vehicle Identification Numbers (VINs), current odometer readings, commuting distance and annual mileage estimates, and a 3-to-5-year driving history including accidents and violations. |
| Homeowners Insurance | Square footage of the home, year built, roof condition and material, security and fire safety system details, estimated replacement cost of the structure, and details on any high-value items like jewelry or art. |
| Renters Insurance | Estimated total cash value or replacement cost of personal belongings, building construction type, security features of the rental unit, and desired liability limits (typically $100,000 to $500,000). |
| Life Insurance | Age, height, weight, detailed medical history, smoking status, occupation, and financial asset overview to determine the necessary death benefit amount. |
Methods for Obtaining Insurance Quotes in New Jersey
Consumers in New Jersey have multiple avenues for securing insurance quotes. Each method offers distinct advantages and potential drawbacks depending on your preference for digital convenience versus personalized professional advice.
1. Online Comparison Tools and Aggregators
Digital quoting platforms allow you to input your information once and receive estimated rates from multiple national carriers simultaneously. This method is fast and provides an immediate baseline of market pricing. However, third-party aggregator sites may not always capture complex discounts or tailor coverage limits precisely to your risk profile. When using these platforms, ensure you look at the carrier's direct website to verify the final quote accuracy.
2. Captive Insurance Agents
Captive agents represent a single insurance company, such as State Farm, Allstate, or GEICO. They possess deep, specialized knowledge of their specific company's underwriting guidelines, discounts, and policy structures. The primary limitation is that a captive agent cannot shop the broader market on your behalf; if their single company's rates are uncompetitive for your profile, you will not see alternative options.
3. Independent Insurance Agents and Brokers
Independent agents represent multiple insurance carriers. They can run quotes across several competing regional and national companies simultaneously, matching your risk profile with the carrier offering the best combination of price and coverage. Independent agents in New Jersey are particularly valuable because they understand regional risk factors, such as coastal flood zones or high-traffic corridors along the Turnpike and Garden State Parkway.
Factors That Influence Your Insurance Rates in New Jersey
When you request insurance quotes, carriers evaluate numerous rating factors to price your policy. Understanding these factors helps you identify areas where you can improve your risk profile and lower your premiums over time.
- Location (Rating Territory): Where your car is parked or your home is situated significantly impacts your rate. Urban areas in New Jersey with higher traffic density, greater accident frequencies, or higher property crime rates generally see higher premiums than suburban or rural counties.
- Credit History: In New Jersey, insurance companies are permitted to use credit-based insurance scores (where permitted by state regulations and underwriting guidelines) to help determine auto and property insurance rates. Maintaining a strong credit history often results in lower quoted premiums.
- Claims History: Your past insurance claims record is a major pricing metric. Multiple at-fault accidents or property claims within a three-to-five-year window indicate higher future risk, leading to higher quote amounts.
- Deductibles and Limits: Choosing a higher deductible (e.g., raising a homeowners deductible from $1,000 to $2,500) reduces your monthly or annual premium, but increases your out-of-pocket financial burden in the event of a claim.
Evaluating and Comparing Competing Quotes
Receiving multiple quotes is only the first step; analyzing them correctly ensures you do not sacrifice vital protection for a marginally lower price. When placing quotes side by side, verify that you are comparing identical coverage limits and deductible structures. A quote that appears significantly cheaper may have stripped away vital coverages, such as comprehensive and collision on an older vehicle, or lower liability limits that leave your personal assets vulnerable.
Furthermore, examine the financial stability ratings of the insurance carriers providing the quotes. Independent rating agencies like AM Best evaluate insurer financial strength, indicating their ability to pay claims during catastrophic events. Choosing a remarkably cheap policy from an unstable carrier introduces unnecessary risk. Finally, research customer satisfaction reviews regarding the claims-handling process for each shortlisted company.
Common Mistakes to Avoid When Shopping for Insurance
Navigating the quoting process efficiently requires avoiding several pitfalls that can cost you money or leave you underinsured:
- Providing Inaccurate Information: Omitting a household driver, a past speeding ticket, or an insurance claim to secure a lower initial quote will result in a corrected, higher premium once the carrier runs official motor vehicle and claims reports during underwriting.
- Focusing Solely on Price: Selecting the absolute cheapest quote without reviewing the exclusions, deductibles, and endorsement options can lead to severe financial distress during a claim.
- Failing to Bundle Policies: Many carriers offer substantial discounts (often 10% to 25%) if you purchase your auto and homeowners or renters insurance through the same company. Quoting policies separately without checking bundle discounts is a missed savings opportunity.
- Ignoring Available Discounts: Failing to ask about discounts for paperless billing, defensive driving courses, anti-theft devices, or hybrid/electric vehicle ownership can leave money on the table.
Next Actions and Recommendations
To begin getting insurance quotes in New Jersey efficiently, compile your personal documents, vehicle details, and property specifications. Decide whether you prefer the speed of online comparison tools or the personalized guidance of an independent insurance agent. Request quotes from at least three different carriers, ensuring each quote reflects identical coverage limits and deductible choices. Review the financial ratings and customer service reputations of the top contenders before committing to a policy. For complex property or liability situations, consulting a licensed New Jersey insurance professional is strongly recommended to ensure full compliance with state regulations and comprehensive personal asset protection.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
