The Financial and Personal Cost of No Medical Life Insurance for Parents Over 50
For parents over the age of 50, the absence of life insurance—specifically policies designed to cover medical costs, end-of-life expenses, or potential care transitions—creates significant financial vulnerability. Without this coverage, families often face sudden, out-of-pocket burdens including funeral costs, outstanding medical debts, and potential gaps in long-term care funding that can destabilize the financial future of surviving children and dependents.
Understanding the Life Insurance Landscape After 50
As individuals reach their fifties, the primary purpose of life insurance often shifts. While younger parents typically seek coverage to replace income and pay off mortgages, those over 50 are often looking to mitigate "legacy risk." This refers to the financial cleanup required when a parent passes away or experiences a significant health decline.
When we talk about "no medical life insurance," we are referring to the lack of a policy that accounts for the reality of aging. This includes life insurance that features "living benefits" (accelerated death benefits) or policies that specifically provide liquidity to cover final medical bills, hospice care, or nursing home transitions. Without such a safety net, the responsibility for these costs defaults to the estate or, failing that, the next of kin.
The Direct Financial Impact on Families
The most immediate cost of not having coverage is the depletion of personal savings. When a parent dies without insurance, existing bank accounts, retirement funds, or real estate assets are frequently liquidated to cover final expenses.
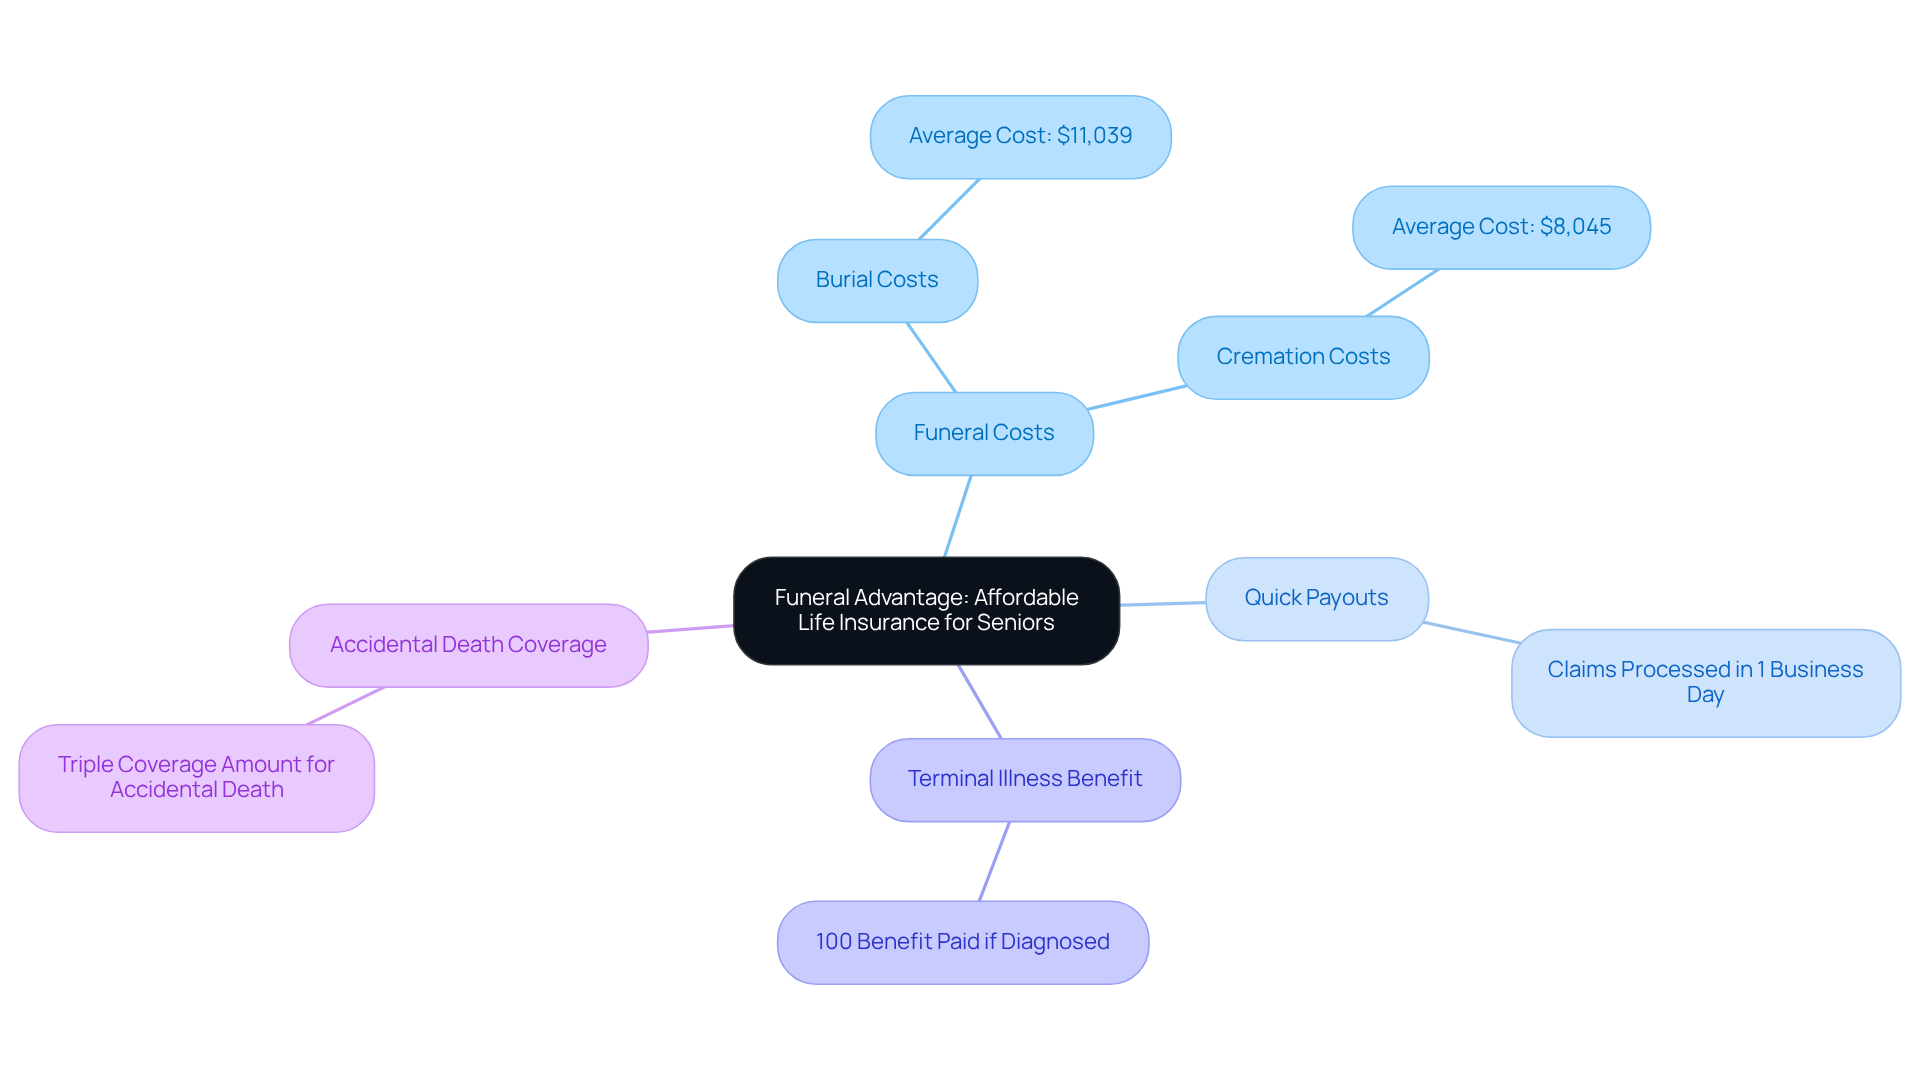
- Funeral and Burial Costs: As of 2026, the average cost of a traditional funeral in the United States ranges between $8,000 and $12,000, depending on the region and the level of service chosen. Without a dedicated life insurance policy, this cost is paid immediately by surviving family members.
- Unpaid Medical Debt: While federal law often prohibits the transfer of debt to children, medical bills can still be claimed against the assets of the parent's estate. If the estate has to sell a home or exhaust a brokerage account to pay medical providers, the inheritance intended for the children is reduced significantly or eliminated.
- The "Care Gap": Many parents over 50 face a transition period where health declines but life continues. A policy that lacks a chronic or terminal illness rider means that if a parent becomes unable to live independently, the family must pay for home health aides or facility care entirely out of pocket.
Comparison: Insured vs. Uninsured Financial Trajectories
The following table illustrates the potential disparity between having a structured insurance policy and relying on personal assets when a health crisis or death occurs.
| Expense Category | Scenario A: Insured (With Rider) | Scenario B: Uninsured |
|---|---|---|
| Final Medical Bills | Covered via policy proceeds | Paid from estate/personal savings |
| Funeral Costs | Policy death benefit handles cost | Immediate out-of-pocket burden |
| Living Benefits | Accelerated payments cover care | Costs deplete retirement savings |
| Inheritance Impact | Assets remain largely intact | Assets reduced/liquidated |
| Family Stress | Fixed financial path provided | Administrative and financial chaos |
The Psychological Cost of Financial Uncertainty
Beyond the hard math of bank balances, there is an intangible "cost of worry." When aging parents do not have insurance, adult children often find themselves in the position of being their parents' financial underwriters. This dynamic can shift the parent-child relationship into one of financial stress.
Adult children may choose to work extra hours, delay their own retirement contributions, or skip their own life insurance premiums to ensure their parents have adequate funds for emergencies. This creates a ripple effect, where the lack of insurance coverage for the parent results in a lack of financial security for the next generation.
Why Age 50 is a Critical Threshold
Insurance underwriting changes significantly after age 50. Premiums increase because the statistical likelihood of health issues rises. Many individuals avoid looking for coverage because they fear high premiums, but this is a common strategic error.
By avoiding the market, these individuals forfeit the opportunity to lock in rates while they are still in relatively good health. Purchasing a policy at 50 is almost always more affordable than attempting to secure one at 65 or 70. The "cost of waiting" is a verifiable increase in monthly premiums that persists for the lifetime of the policy.
Evaluating Your Options: What to Look For
If you are a parent over 50 or are advising your parents, you must look beyond the standard term life insurance. Focus on the following features to mitigate the risks mentioned:
- Living Benefits (Accelerated Death Benefits): These allow a portion of the death benefit to be paid out early if the policyholder is diagnosed with a terminal or, in some cases, chronic illness. This provides cash exactly when medical costs are at their peak.
- Final Expense Insurance (Burial Insurance): These are smaller, whole-life policies designed specifically to cover funeral costs and minor medical bills. They are often easier to qualify for because they require less extensive medical underwriting.
- Guaranteed Issue Policies: For those with existing health conditions, these policies may have higher premiums, but they do not require a medical exam. They ensure that at least the funeral costs are covered, preventing the total loss of other assets.
Addressing Common Misconceptions
One of the biggest mistakes is the belief that "I have enough savings, so I don't need insurance." However, savings are finite, and medical costs are unpredictable. A major health event can cost hundreds of thousands of dollars, which can easily exceed the liquid savings of the average household. Insurance is not just about the money you have today; it is about protecting that money from being consumed by end-of-life costs.
Another misconception is that employer-provided life insurance is sufficient. Often, this coverage terminates upon retirement or departure from the company. Relying solely on an employer policy leaves the individual exposed at the exact moment they are most likely to need coverage—during their senior years.
Practical Next Actions
To address the risks associated with having no insurance, take the following steps:
- Audit Current Assets: Determine exactly how much liquid cash is currently available to cover a sudden $20,000 to $50,000 emergency.
- Consult a Financial Advisor: Seek out an independent insurance broker who specializes in senior or mid-life insurance. They can provide quotes from multiple carriers to help you understand the price-to-benefit ratio for your specific health profile.
- Review Beneficiaries: Ensure that any existing assets are titled in a way that avoids probate, which can tie up funds for months, making them inaccessible for immediate end-of-life expenses.
- Discuss Needs with Family: Transparency is essential. Ensure that all family members understand what resources are available and where the potential gaps lie.
Frequently Asked Questions
Is it too late to get life insurance at 50 or older? No, it is not too late. While premiums will be higher than they would be for a 20-year-old, many carriers offer specialized products for those over 50. The goal is to secure coverage now before age or further health complications make policies prohibitively expensive or unavailable.
What if I have pre-existing medical conditions? Many insurers offer "simplified issue" or "guaranteed issue" policies for those with health conditions. While these policies may have lower coverage limits and higher costs, they provide a guaranteed financial baseline that protects your family from the immediate costs of funeral expenses and final medical bills.
Do I really need life insurance if my mortgage is paid off? Yes. Even without a mortgage, you will have end-of-life expenses and potential medical debt. If your goal is to leave an inheritance or ensure your spouse is not burdened, insurance acts as the liquidity needed to prevent the forced sale of other assets.
How much does "final expense" insurance typically cost? Costs vary based on age, gender, and health status. As of 2026, a healthy 55-year-old might pay significantly less than someone at 65. The primary cost-driver is the amount of the death benefit; keeping the benefit limited to actual funeral and modest medical costs keeps the monthly premium manageable.
Can I get insurance that covers long-term care? Yes, some life insurance policies allow you to add "riders" for long-term care, which provides a pool of money specifically for nursing home or assisted living costs. This is often more cost-effective than buying a standalone long-term care insurance policy.
Final Recommendation
Do not wait until a health crisis occurs to consider your life insurance needs. The financial stability of your estate and the emotional well-being of your family depend on proactive planning. Contact a licensed insurance professional to review your specific health profile and asset structure. The cost of securing a policy today is a fixed expense, while the cost of being uninsured in the face of an emergency is an unpredictable, potentially devastating, and uncapped liability.

Image Gallery
Select an image to open it in a new tab.

Lars Thomsen
Global Labor Markets and Economic Strategy Editor
